Skip to content
EXCEL CAPITALMANAGEMENT
515 N Flagler Dr, Suite P300
West Palm Beach, FL 33401
Talk to our team877-880-8086
Get Funded

How to Value a Business: A Comprehensive Guide to Properly Valuing Your Business

EXCELCAPITAL - HOW TO VALUE A BUSINESS FEATURED IMAGE 1

How to value a business: How much is your business worth?

Whether it’s to acquire funding via a small business loan or investors or sell the business, properly valuing your business is an important step that needs to be done right. 

The more accurately you can appraise the value of your business, the more funding you’ll be able to generate and the greater chance you’ll have of securing a buyer. 

A business valuation is the process of determining how much your business is worth. 

There are several specific methods that are typically used to calculate a business’s true worth, but these are the 3 main overarching valuation methods which all specific methods fit under: 

EXCELCAPITAL - HOW TO VALUE A BUSINESS

3 Methods to Value a Business:

  1. Income-based: Calculates valued based primarily on income metrics such as revenue and profit. This includes the Discounted Cash Flow method which takes into consideration projected future cash flow value at present compared to risk as well as Capitalization of Earnings, which is a combination of revenue, profit, and cash flow projections.
  2. Asset-based: Calculates value based on a business’s assets.
  3. Market-based: Calculates value based on the sale of similar businesses within your same industry. 

It’s also important for entrepreneurs in the market to buy or invest in to be aware of how business valuations work, so they know how to properly value a business which they’re considering purchasing or making an investment in. 

No matter where you fall in the process, you should invest the necessary time to better understand how business valuations work. 

That’s why the purpose of this guide is to break down how business valuations work, methods for doing so, and tips to help make the process smoother for all parties involved. 

Table of contents

  • Preparing to value your business
  • 3 Primary methods for calculating the value of your business
  • How to value your business example
  • Tips to make the most of your business valuation

First, let’s talk about some important tips for preparing for your valuation:

Preparing to value your business

Before we dive into the major business valuation methods, there are some important steps you should take to prepare for your business valuation.

Appraising the value of your business is a big step no matter what point in the business growth timeline you’re at, so investing a bit of time to prepare beforehand can help make sure things go off without a hitch. 

Here are 4 things you should do before valuing your business:

1. Learn about business valuations

Since you’re reading this, you’re probably already at this step. 

However, it’s important to mention that because business valuations can be complex and are directly tied to the success and/or ultimate monetary value of your business, you should take some time to learn about business valuations. 

Learn about the different valuation methods, what type of business should use which method, why, and all the various details you should take into consideration when valuing the business. 

For example, two of the most important terms you should look into are Seller’s Discretionary Earnings (SDE) and Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA).

SDE and EBITDA are both arguably the two most common types of business valuation methods (which fit into one of the major valuation method buckets we’ll talk about later), though they’re similar in nature. 

Both are essentially methods for calculating a business’s pure net profits, SDE generally being used for small businesses under $500,000 in value and EBITDA for businesses above that.

2. Research your industry

Business valuation methods take more into account than a business’s performance and well-being, they look at the industry as a whole as well. 

For that reason, take some time to research the industry the business is in– if you don’t already do that regularly– to understand its current state and direction.

Financial information for most public companies is easily enough found online and a great way to get an idea of the state of the industry. However, you can also search out potential business sales listings on sites like AngelList for any that might exist within the industry as another great resource. 

3. Get your finances in order

This one might sound like an obvious step in retrospect, but it’s often overlooked until it’s too late. 

If you’re the business owner, chances are, there are things you can do to measurably improve your company’s financial situation within a matter of a few months to a year. 

Take time to review critical reports such as your profit & loss and balance sheet to get an idea of where you can make improvements. 

Also, make sure you have certain financial documents in order which will be necessary for the valuation process:

  • Profit & loss statement
  • Tax filings
  • Licenses and other proprietary documents
  • Other basic business finance reports

We’ll go more into considering a professional appraiser later, but it’s important to mention at this point that a professional business appraiser will run a full financial audit of your company, so while they will cost you they’ll take care of this step entirely (and with accuracy you can count on). 

4. Review your assets

Similar to the previous point, you’ll also want to review your assets. 

This is important for all financial calculations, but most notably for asset-based valuation methods. 

Start by making a list of all your business assets (which essentially includes anything that adds value to your business), including both:

  1. Tangible, and
  2. Intangible assets

Within these two groups exist all kinds of different business assets, including:

Tangible assets:

  • Physical assets such as property/real estate, your production machines, and delivery vehicles
  • Inventory
  • Cash
  • Investments

Intangible assets:

  • Intellectual property such as patents and trademarks
  • Subscriber list
  • Brand reputation

Similarly, don’t forget to take stock of all your liabilities, which can include:

  • Business loans
  • Accounts payable, and
  • Expenses

3 Methods for valuing your business

Now that you’ve taken steps to prepare for your business valuation, whether you’ll be doing it yourself or hiring a professional, it’s time to break down the 3 overarching business valuation methods. 

Each method below calculates the value of your business differently. Some methods are used more often than others, however, each is useful to know as they all have a place depending on the industry and other factors. 

As a final note, if you’re doing the valuation yourself, work to make it as unbiased and accurate as possible. Inflating your numbers will only hurt you in the long run, from giving you an incorrect picture of your business health to turning away potential buyers. 

Also, resist the urge to mesh methods together. Each method’s calculation can be run separately, but attempting to mesh them together is bound to result in skewed results. 

These are the 3 approaches to business valuation: 

EXCELCAPITAL - HOW TO VALUE A BUSINESS

1. Income-driven method

The income method for business valuation uses metrics such as profit and revenue (typically, future projections of those metrics), as the basis for valuation.

There are 2 primary methods used within the income approach bucket:

Capitalization of earnings method

This method takes into account factors such as a business’s cash flow to calculate its future profitability. This method is best for established businesses with stable profit. 

Discounted cash flow method

This method, which calculates the value of a business based on its future cash flow projection, is ideal for new businesses with high growth potential.

EXCELCAPITAL - HOW TO VALUE A BUSINESS

2. Asset-driven method

Asset-driven methods use, as it sounds, a business’s assets to calculate its value. These are especially good for real estate and investment-based businesses. 

Again, there are several different methods within this approach as well, including the Adjusted Net Asset method, which adds up a business’s assets and subtracts its liabilities to find its value.

To use an asset-driven method, you need to have an idea of what monetary value you can place on your assets. If you’re not sure, instead of running a guesstimate, do some research to make sure those estimates are as accurate as possible. 

EXCELCAPITAL - HOW TO VALUE A BUSINESS

3. Market-driven method

The final business valuation method is the market-based approach.

This approach primarily takes into account the purchases of comparable businesses in your industry as a marker of its value. 

This can be a useful method if you’re looking for a quick ballpark estimate as if you know of another similar business in your industry that recently sold, chances are your business will sell for a similar value.

This method is especially useful if your industry is experiencing rapid growth (such as tech) as there are likely examples you can reference in your industry. 

Make sure to gather data on all comparable businesses and don’t just settle on the data from one. The more data you can provide to a potential seller, the more solid you’ll make your case for pricing your business at what you decide it to be. 

EXCELCAPITAL - HOW TO VALUE A BUSINESS

How to properly value your business: Example

While there are many different ways to calculate the value of a business, for the sake of the example, we’re going to use the most common method, the SDE method used often for businesses of <$500,000 in value, for our example. 

Adrianna owns a local family restaurant originally started by her parents when she was a child called Luiz’s Hot Spot. She’s interested in getting a valuation for the business so she can put the restaurant up for sale.

First, Adrianna starts by gathering the basic financial numbers we touched on above for the business:

  • Annual SDE: $95,000
  • Annual revenue: $475,000
  • Assets:
    • Real estate: $175,000
    • Equipment and furnishings: $35,000
    • Inventory: $100,000
  • Liabilities: $50,000

Next, Adrianna will use these numbers to calculate the average value for her business.

Calculating SDE

Using bizbuysell.com’s latest statistics, the restaurant industry as a whole has an average multiplier of 1.98. 

To roughly calculate the value of her business, then, Adrianna takes her $95,000 calculated SDE, found with this equation: 

EXCELCAPITAL - HOW TO VALUE A BUSINESS

Net earnings (before taxes) + Personal earnings + Non-essential expenses for the year (one-time, non-repeating expenses– doesn’t include COGS) – Liabilities = Your SDE

Then runs her SDE through this equation: Business’s SDE x Multiplier, using the multiplier of 1.98 to get her estimated business value:

EXCELCAPITAL - HOW TO VALUE A BUSINESS

$95,000 (SDE) x 1.98 (Multiplier) = $188,100 (Business value, rough estimate)

Keep in mind that this calculation, in particular liabilities and intangible assets, includes things we didn’t cover here such as future prospects, local economy projections, and other elements.

What other factors affect the value of Adrianna’s business?

In addition to the abovementioned factors, there are other factors that can affect the true value of Adrianna’s restaurant that aren’t included in this rough SDE estimate. 

There are a whole collection of additional elements that must be factored in to get an accurate value for the business, including: 

  • How eligible is she for financing? 
  • How loyal are her customers?
  • When will key employees retire?
  • Supplier relationships may change

Several factors influence the final number, including the fact that Luiz’s is a family-owned restaurant and a change in ownership will be specifically impactful to such a long-held local establishment. In addition, the trend away from individually owned restaurants, local business growth, and community response. 

Keep in mind that the above example is only a rough estimation and shouldn’t be used in exactness to run your own valuation. 

Rather, use it to get an idea of what a real business valuation might look like to help you prepare for your valuation. 

4 Tips to make the most of your business valuation

Preparing for and executing a business valuation is a big event. 

You not only want to make sure that you’re properly prepared, but that you do everything you can to make the most of the valuation throughout the process– and give yourself the greatest odds of success at acquiring funds or an eventual purchase. 

Here are some additional tips to help you make the most of your business evaluation.

1. Be realistic (and take emotion out of the equation)

One of the most common mistakes of business owners during the valuation process is to overprice their own business due to bias. 

As the owner, you know how much effort you’ve invested in growing your business. This enormous effort can skew your perception of the value of your business, making you overvalue your business. 

This is all the more reason why one of the accepted evaluation methods is so important, because it takes that emotional aspect out of the equation. 

2. Consider giving your marketing and public appearance a facelift

One of the simplest things you can do to improve your chance of selling the business, and at a desirable price, is to give your marketing and overall public appearance a facelift before putting it up for sale. 

The way the public views your business inevitably plays a big part in the process of acquiring a buyer as they will see your business first the way everyone else does.

Taking a bit of time to update your marketing campaigns, branding, advertising, even simple things that might be a bit out of date such as your business cards, signage outside your business, and your facility itself will go a long way toward securing a buyer. 

3. Get key employees on board

It’s common for key employees to stay in place after selling. After all, it’s easier for the buyer to keep an already well-oiled team in place rather than hire and train their own. 

For that reason, it’s important to make sure you can secure those key employees now and get them on board with the eventual sale and transition.

When you decide to reveal this information is up to you, perhaps you decide not to reveal anything until a prospective buyer is in place, but it’s something you’ll want to do sooner than later to reduce surprises. That way, you can communicate who from the team the buyer can count on staying when the transition occurs. 

Secure not only letters of intent from those key employees but also any vital vendors as well. The more you can guarantee your potential buyer that these key elements will remain in place, the more you’ll reassure them of the return on purchasing your business. 

4. Consider hiring a professional appraiser

At this point, it might be obvious that appraising your business yourself is risky at the very least.

Between the natural bias that business owners experience and tendency to overvalue when it’s their own business and the complexity of business evaluation methods, appraising the value of your business may be in better hands with a professional. 

A professional appraiser can be costly, up to several thousand dollars for a full appraisal, but they’ll run a full audit on your financials to make sure that your valuation is accurate. 

In addition to this, having a record of a professional valuation will give credibility to your valuation that is indisputable during negotiations.

A personal valuation is definitely faster and saves you money, but not only may that valuation be incorrect, a buyer is more likely to negotiate the price down without evidence of a professional appraisal.

It’s your business– get the most from it

Valuing your business is a big step in any entrepreneur’s career, whether it’s your first or fifth and your business is worth $200,000 or $2 million (or more). 

You not only want to make sure you’re properly valuing your business but that you make that valuation and sales process as smooth as possible and put yourself in a position to maximize your return from that sale or to acquire the maximum amount of funding for the business. 

Use the above tips to prepare for your valuation, consider which method might be best for you, apply the additional tips for making the most of the process, and consider hiring a professional appraiser. 

It’s your business. You worked hard to grow it into what it is today, so don’t skimp on the details. Get the most you possibly can from your time and hard work.

Mezzanine Financing Definition

EXCELCAPITAL - MEZZANINE FINANCING FEATURED IMAGE (1)

What is mezzanine debt financing? 

Mezzanine debt, also called mezzanine financing, is a type of financing that got its name due to the fact that it’s a debt-equity hybrid. 

Mezzanine financing gives the lender the ability to convert to an equity interest in the company in the case of a default, which makes it a frequent option during acquisitions and buyouts. 

While as a type of debt it has the highest risk, high mezzanine loan interest rates also offer the highest potential returns for lenders, though with flexible repayment terms for borrowers.

Is a mezzanine loan debt or equity?

Mezzanine loans are a hybrid of both debt and equity, which can make them a bit a difficult at first to understand. 

The best way to understand them is that they’re a form of debt financing that has equity options built in, which allows it to take on the form of an equity investment if those options are exercised.

Mezzanine debt isn’t commonly used, as roughly only about 10% of debt is mezzanine debt, and therefore it’s often considered lower priority than senior debts. However, its unique qualities make it a useful option in the right situation. 

EXCEL-WHAT-IS-MEZZANINE-FINANCING

How does Mezzanine debt work? 

Mezzanine debt creates a new level of flexibility for borrowers and lenders that otherwise wouldn’t be possible. 

Mezzanine lending is often sought-after as an aid to companies with specific acquisition goals. Mezzanine lenders also tend to be long-time investors in the company, making them a trusted partner to make those projects a reality. 

Mezzanine loans often have a few unique qualities, including:

  • As opposed to traditional bank loans, mezzanine loans typically have a higher return than senior debt and are often unsecured
  • Mezzanine debt is subordinate to senior debt but higher priority than pure equity
  • There is no principle amortization
  • A portion of the return on a mezzanine loan is fixed, differing from pure equity

Explaining mezzanine financing can be a bit confusing even with a thorough explanation, so let’s look at an example. 

EXCEL-Mezzanine-Financing-Example

Mezzanine financing: Example

Bill is looking to purchase a company worth $10 million, so he goes to a lender he’s hoping will finance the purchase. 

Bill isn’t approved for the full amount, but he gets $5 million toward the purchase. To bridge the gap and get the remainder of the financing he needs to make the purchase, he looks to get mezzanine financing.

He acquires mezzanine financing for $4 million, making his direct investment just $1. That breaks down to:

  • $5 million basic loan
  • $4 million mezzanine loan
  • $1 personal investment

On the repayment side, the mezzanine lender then charges a 16% interest rate as opposed to just 6% with the bank loan. However, as opposed to paying interest charges monthly or annually, Bill has the option to add those charges to the cost of his loan, giving him added flexibility. 

Pros and Cons of mezzanine debt financing

With a more thorough explanation of what mezzanine debt is, let’s talk about why you might want to consider using mezzanine debt as well as the drawbacks of doing so. 

Mezzanine financing has the unique ability to offer lenders a way of obtaining equity in a business, something no other type of debt financing can do. It can have a considerable impact on a lender’s rate-of-return in some cases.

However, it’s not without its cons for both lenders and borrowers. Here’s a breakdown of both the pros and cons of mezzanine debt for lenders as well as borrowers:

EXCEL-MEZZANINE-FINANCING-PROS-AND-CONS-FOR-BORROWERS

Pros and Cons for borrowers

The greatest pros exist in what mezzanine financing can do for borrowers. However, mezzanine loans offer their own cons as well. 

Pro: Leverage

A mezzanine loan offers borrowers financing they otherwise wouldn’t have been able to acquire, giving them more purchasing power and the ability to earn a higher return on equity optimal cases. 

Pro: Looks better on your balance sheet

Because mezzanine financing often appears as equity on a company’s balance sheet, it makes your debt level appear lower than it is, making it easier for you to qualify for financing. 

Pro: Tax-deductible interest

Interest payments on a mezzanine loan are typically tax-deductible, which can account for a large amount of savings over the course of a year. 

Pro: Flexible repayment options

Repayment options with mezzanine debt are often highly flexible, with the ability to add interest charges to your loan’s balance or even pay those charges with cash. 

Con: Using a mezzanine loan for purchasing leverage is risky

While mezzanine loans have unique benefits for borrowers, they also come with their own set of cons. The primary con of mezzanine loans doesn’t inherently exist in the loan itself but in the way they’re typically used.

Using a mezzanine loan for purchasing leverage comes with a high level of risk. There’s no guarantee the company is going to be a success, or even break even on your investment, so that loan may become a significant debt. 

Con: Equity interest

If you as the borrower default on a mezzanine loan, you could be required to provide equity interests to lenders.

EXCEL-MEZZANINE-FINANCING-PROS-AND-CONS-FOR-LENDERS

Pros and Cons for lenders

The pros and cons of mezzanine loans for lenders are more direct and typical as they relate to lending, but they’re significant nonetheless. 

Pro: Equity benefits

There are just a few pros of mezzanine lending, but they’re significant. 

First, lenders can potentially gain equity, giving them the ability to take advantage of the growth of a business and the resulting equity. 

Pro: Interest income

Another pro is that mezzanine loans typically have very high interest rates, which gives mezzanine financing a high potential return. 

Con: Subordinate debt

Because mezzanine debt is considered subordinate to pure debt, a mezzanine debt from a lender may not be secured by any hard collateral. 

If a business defaults, by the time all senior debt is paid, there may be no more collateral or cash-equivalent to pay repay the loan. 

A unique type of financing

Mezzanine financing is entirely unique among the wide-ranging collection of business financing solutions. 

It serves an important role that other financing vehicles can’t fill, making it a useful tool for both lenders and borrowers. 

What Is Decision Logic? Bank Verification, Loans and Safety

DecisionLogic logo above the title What Is Decision Logic? A Complete Decision Logic Review

Asked to connect your bank account through DecisionLogic before a loan can move forward? It is reasonable to want to know who will see your information and what happens after you connect.

DecisionLogic is a bank-verification and financial-data platform used by lenders and other institutions. With your permission, it helps the requesting company review account information and activity. It does not lend you money or approve your application.

Some institutions we work with use DecisionLogic, and we help facilitate their bank-verification requests. This guide explains both the merchant’s steps and the institution’s review.

Business owner checking a bank-verification request before connecting an account

Decision Logic login: borrowers and lenders

The right login depends on why you are here. A borrower completing a verification request follows a different path from an employee signing in to an institution’s account.

Search results also include an unrelated restaurant-management product called Decision Logic. Check that you are using the bank-verification provider at decisionlogic.com. For request-link guidance, see DecisionLogic’s borrower FAQ.

Decision Logic loans: what the verification means for your application

“Decision Logic loans” usually means loans offered by institutions that use DecisionLogic during their review. There is no single DecisionLogic loan product, interest rate or approval requirement. The lender or funding provider sets those terms.

For a business owner, a verification request may help an institution check the account associated with an application, review available transaction history and understand how money moves through the business. DecisionLogic describes these uses in its business-lending materials.

A bank balance is only a snapshot. An underwriter may also consider recurring receipts, payment obligations, seasonal changes and low-balance periods. A large deposit could be sales revenue, a transfer between accounts or proceeds from another financing agreement. Those distinctions matter when assessing the business’s ability to make payments.

What types of lenders use DecisionLogic?

The platform serves different institutions, including business lenders, consumer lenders and equipment-finance providers. A provider’s use of DecisionLogic does not tell you whether it offers the financing you need or whether you qualify. Confirm the provider’s identity, products and terms directly before applying.

If you are comparing small business loans or a business line of credit, focus first on the amount needed, repayment schedule, total cost and the business’s cash flow. The bank-verification platform is one part of that process.

How do you pass DecisionLogic bank verification?

First, separate completing the bank connection from qualifying for financing. To complete verification, use the correct request, connect the account the institution asked for, and finish your bank’s authentication prompts. If the connection fails, use the troubleshooting steps below.

For the lending review, ask the institution which records it needs and be ready to explain transfers, unusual deposits, existing payments or missing activity. There is no universal DecisionLogic minimum balance, overdraft limit or passing score that guarantees a loan. Any financing requirements come from the institution reviewing your application.

Does completing DecisionLogic mean you are approved?

No. A successful connection means the verification step completed. The institution still needs to review the information, resolve any questions and make its decision. Contact that institution for approval status, funding timing or an explanation of an offer. DecisionLogic cannot provide those answers for it.

If a different institution requests a new verification, do not assume an earlier link covers the new application. Ask which business account and request you should use.

How does DecisionLogic bank verification work?

The basic exchange is straightforward: the institution requests information, you authorize the connection, and the institution receives a report. The exact screens and available records depend on the bank connection and the products the institution has enabled.

From verification request to application review

Two participants, with different responsibilities at each stage.

  1. 1
    Institution sends the request

    A lender or other institution supplies a link associated with your application.

  2. 2
    Merchant checks the request

    Confirm the sender and read what information the connection will share.

  3. 3
    Merchant connects the bank

    Follow the authentication prompts and any bank security challenge.

  4. 4
    Verification completes

    Look for the completion message and follow the return instructions.

  5. 5
    Institution reviews the report

    The reviewer checks available account data and follows up on missing context.

  6. 6
    Institution gives the next step

    Application review, an additional request or a funding decision comes from the institution.

A completed bank connection is not a loan approval. Source: DecisionLogic’s process overview and FAQ.

How to complete DecisionLogic as a merchant or borrower

Before starting, have access to the online banking for the account the institution requested. If your business has several accounts, ask whether it needs the operating account, a deposit account or more than one account. Connecting the wrong account can lead to another request.

Your checklist before and after connecting

Before you begin

  • Confirm the request with your known contact if it is unexpected.
  • Check that you can sign in to your bank directly.
  • Have your bank’s authentication device or phone available.
  • Read the permission and account-selection screens.

Before you close the window

  • Complete any bank security prompts within the connection flow.
  • Check for a success message or instructions to try again.
  • Return to the requesting institution for application updates.
  • Keep the institution’s contact details for follow-up questions.

Never email or text your online-banking password to a representative.

Follow the request through the connection screens

  1. Open the institution’s link. If the request does not match an application you recognize, verify it through a contact method you already trust.
  2. Find your financial institution. Choose the bank and the correct online-banking connection, including a business-banking option when applicable.
  3. Authenticate and review permissions. Follow the prompts presented for your bank. A supported connection may take you to your bank’s own sign-in or authorization screen. Complete any multi-factor authentication there.
  4. Select the requested account when prompted. Review the account details rather than choosing the first account automatically.
  5. Finish and return to the institution. A success screen confirms the connection step. Ask your contact whether anything else is needed for the application.

The examples below come from DecisionLogic’s published walkthrough, reviewed October 17, 2026. They are the provider’s screen examples in device mockups, not a live customer application. Your bank, connection method and institution may show different screens. Select an image to see it larger.

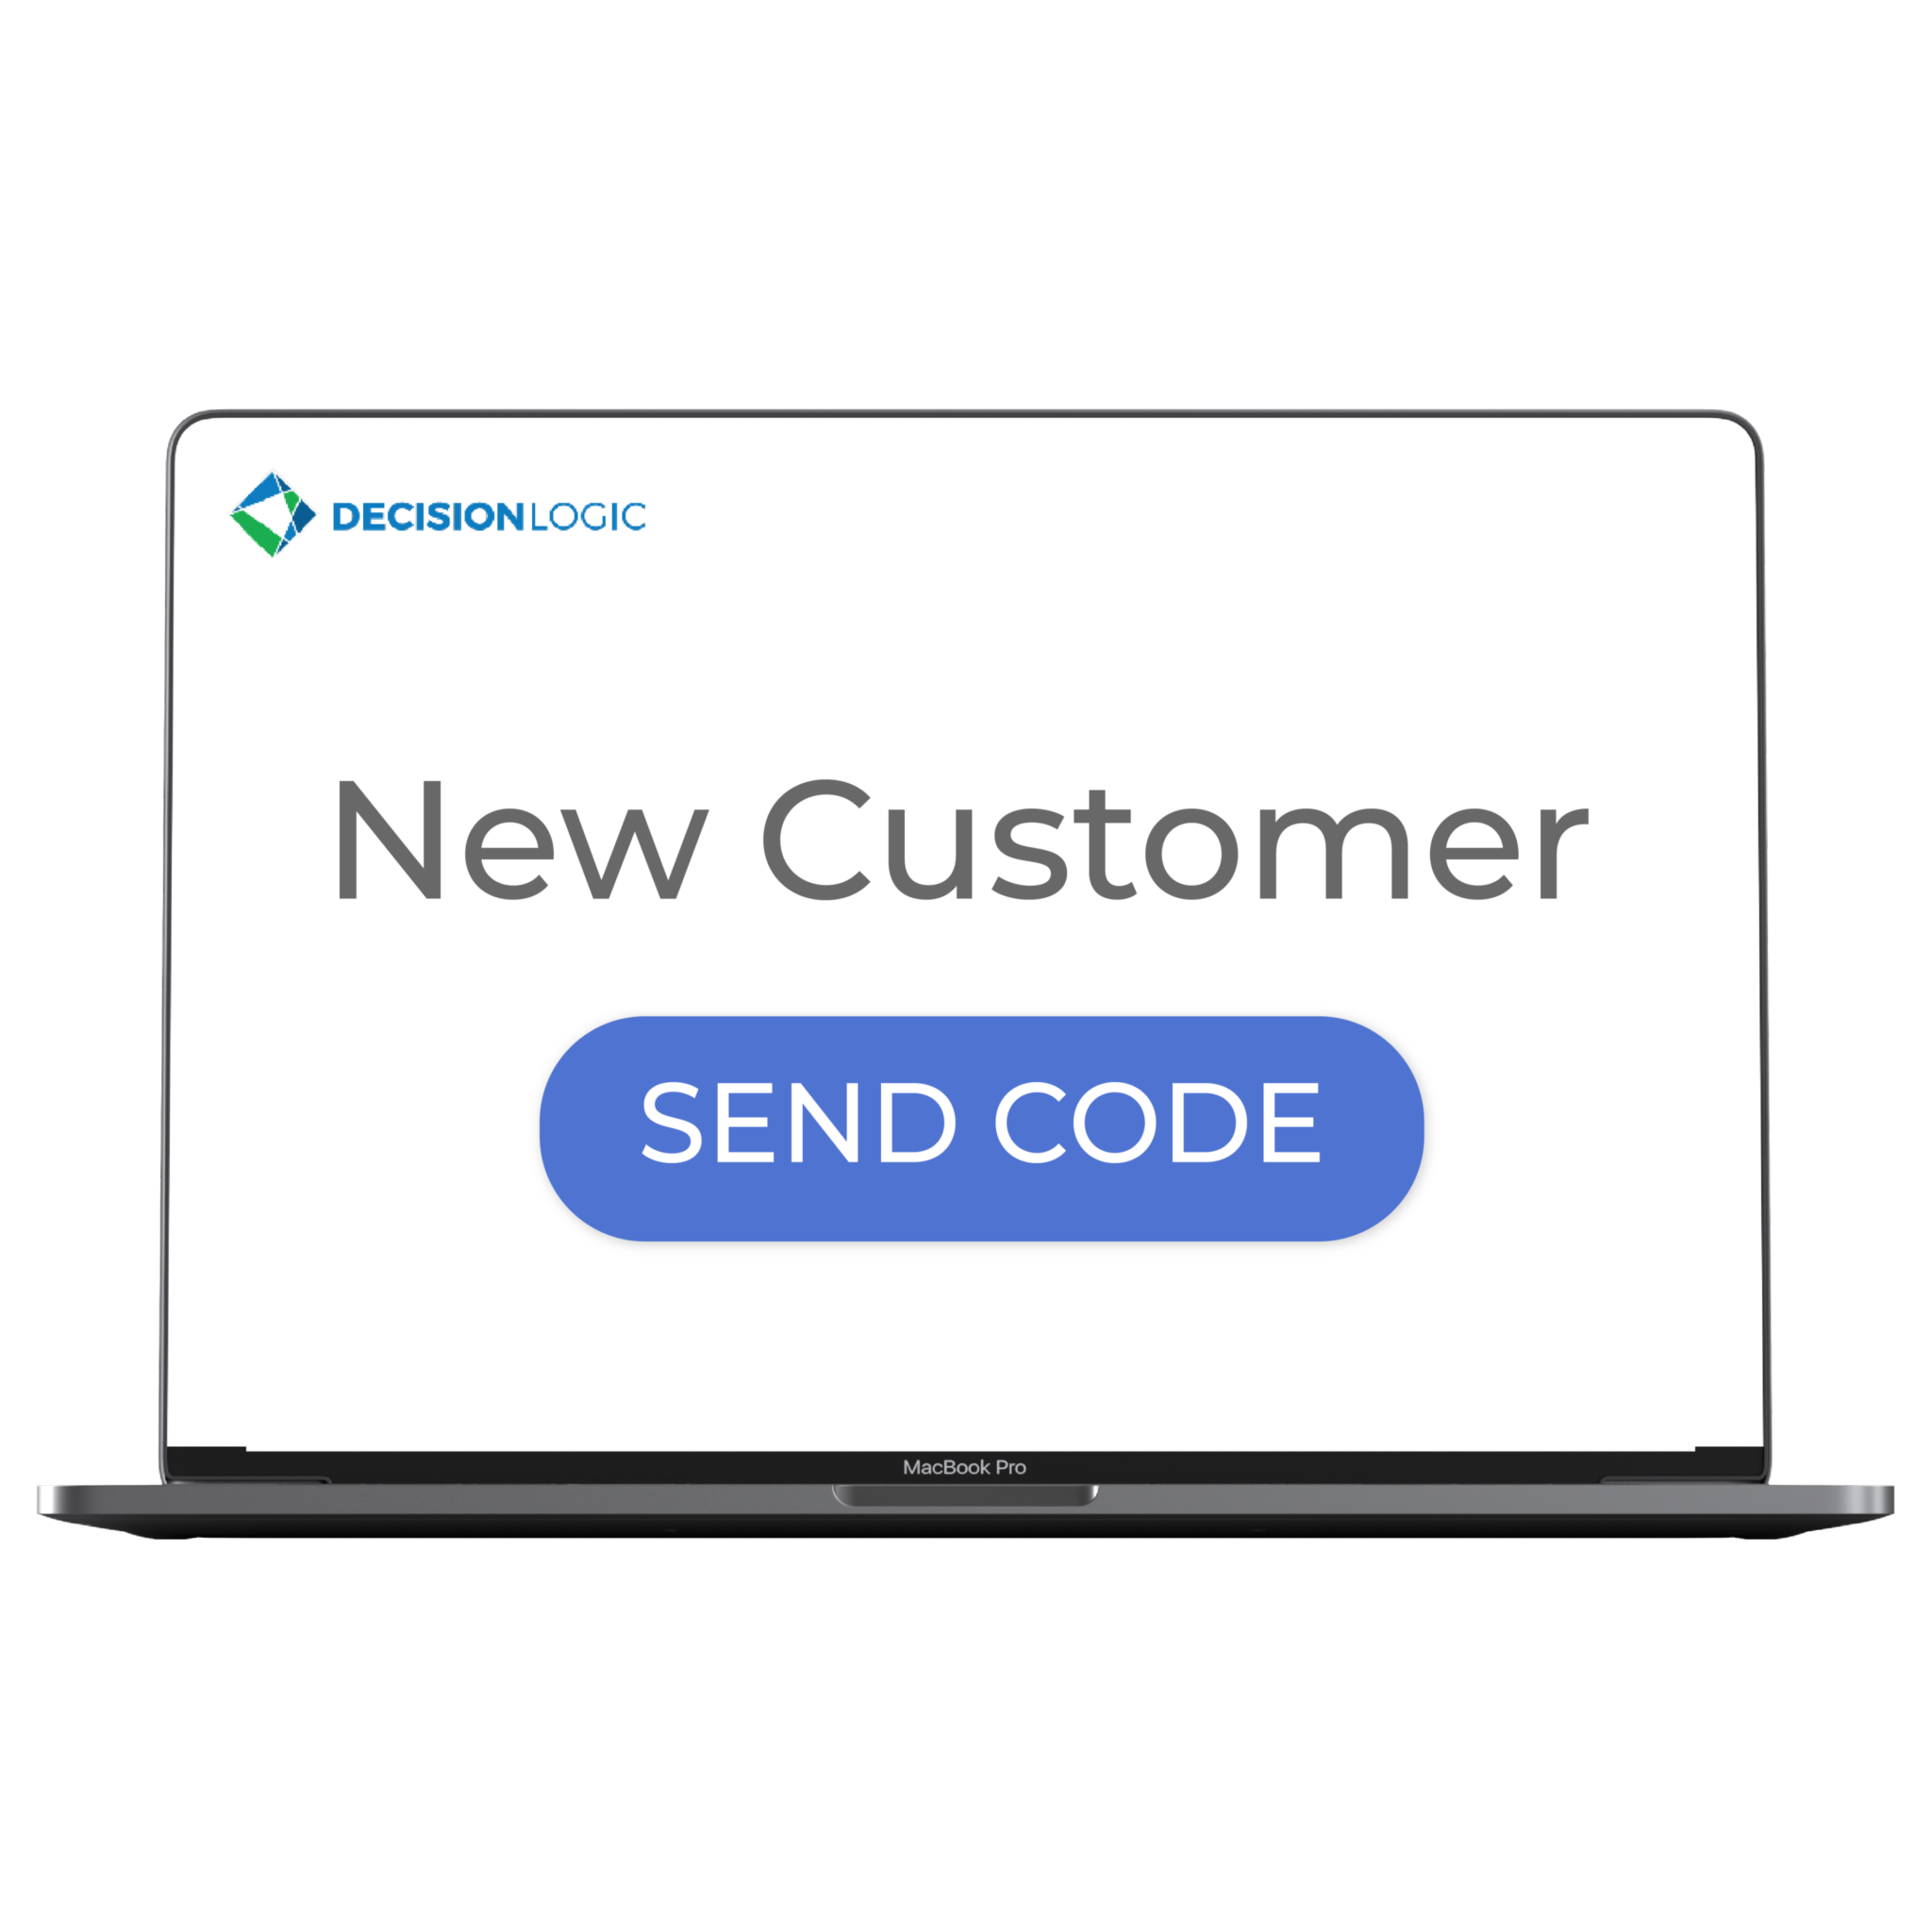
1. The institution sends the request

DecisionLogic published example of an institution sending a new customer request

The provider’s example shows the institution starting a new customer request. The merchant receives the corresponding link by text message or email.

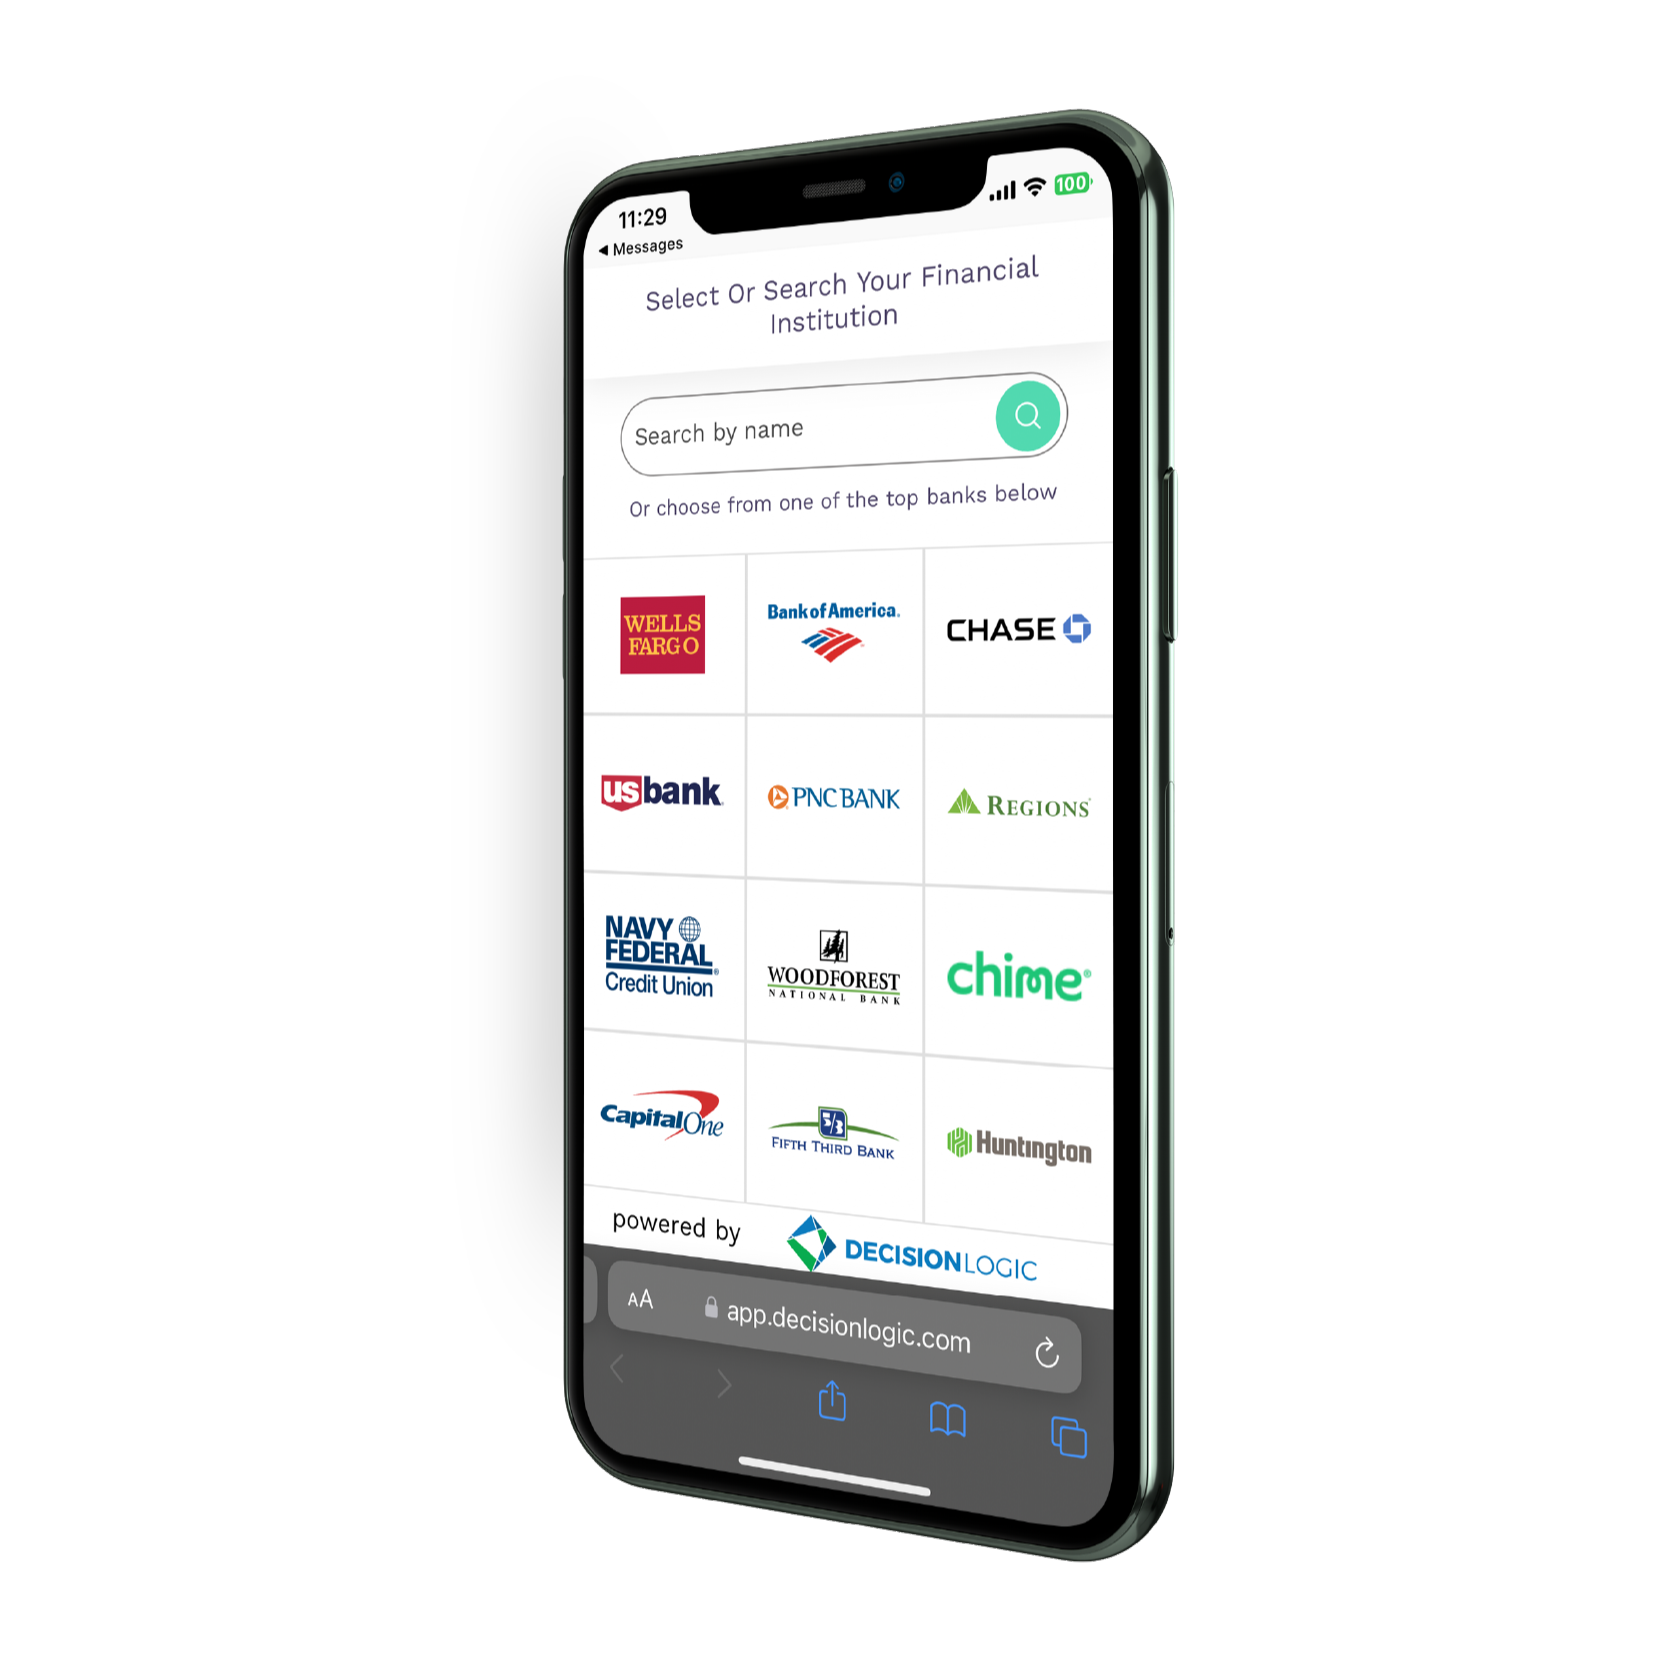
2. The merchant selects the bank

DecisionLogic published bank-selection screen for a merchant

This published screen shows bank selection. Continue through the authentication and permission steps shown for your bank.

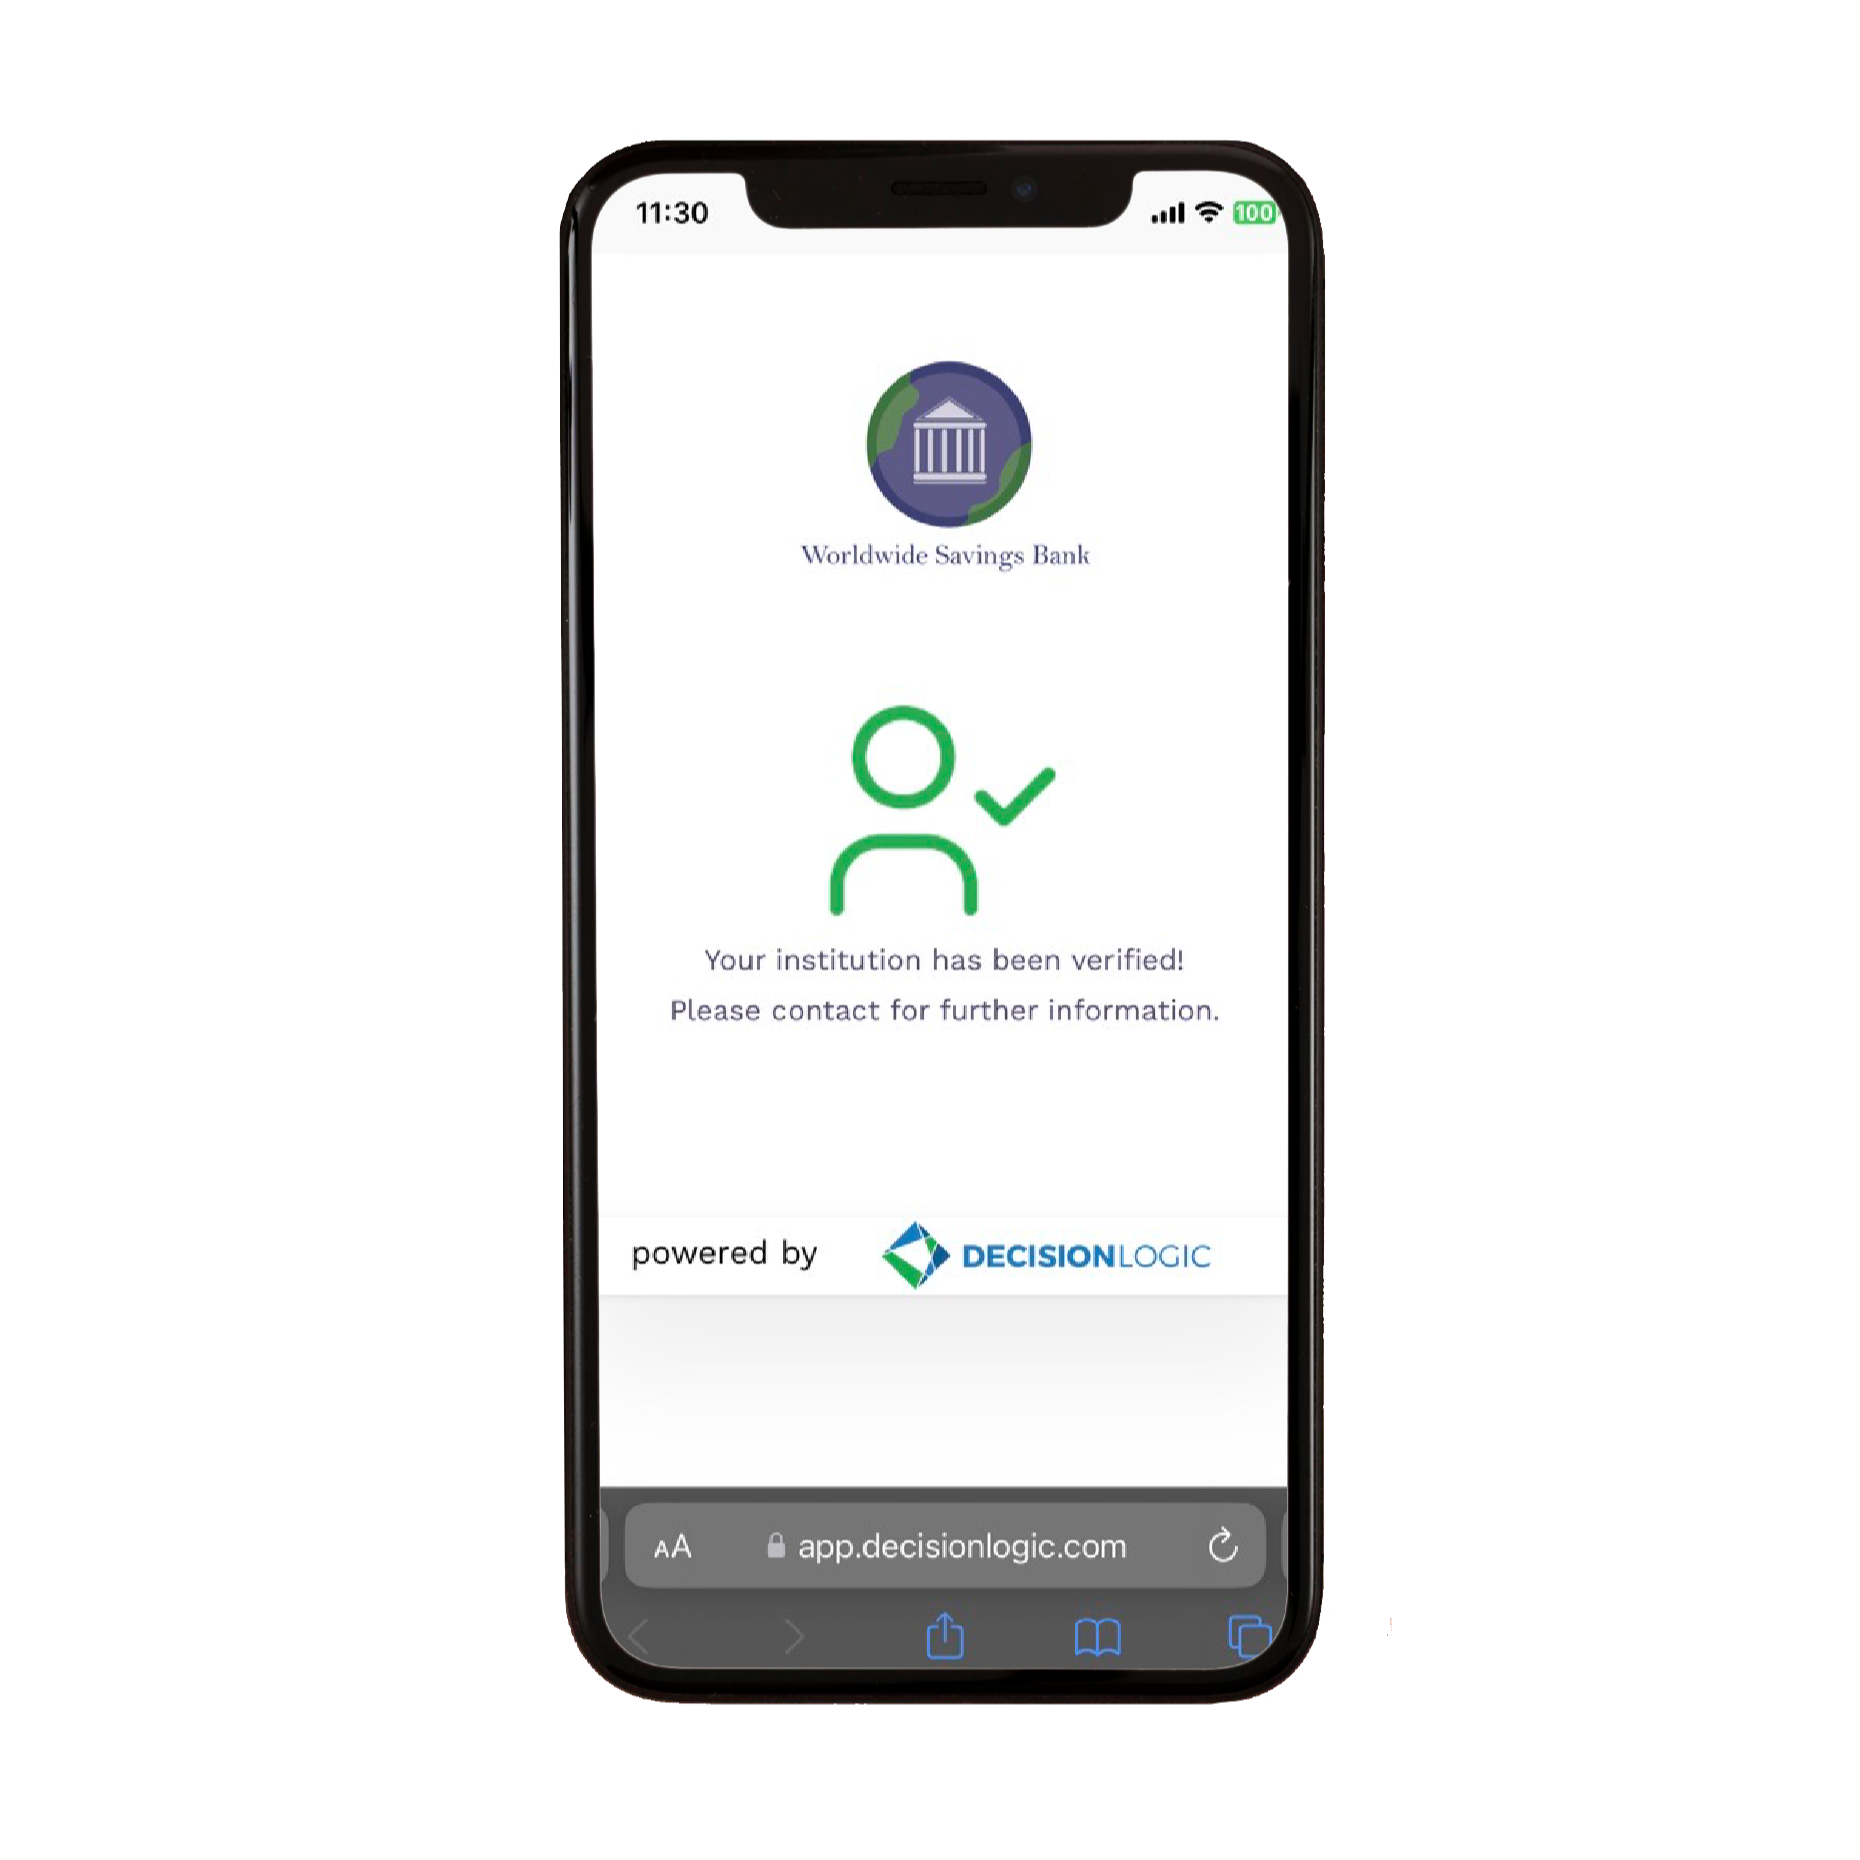
3. The merchant receives confirmation

DecisionLogic published screen confirming successful bank verification

The completion message concerns bank verification. It does not confirm that a loan has been approved or funded.

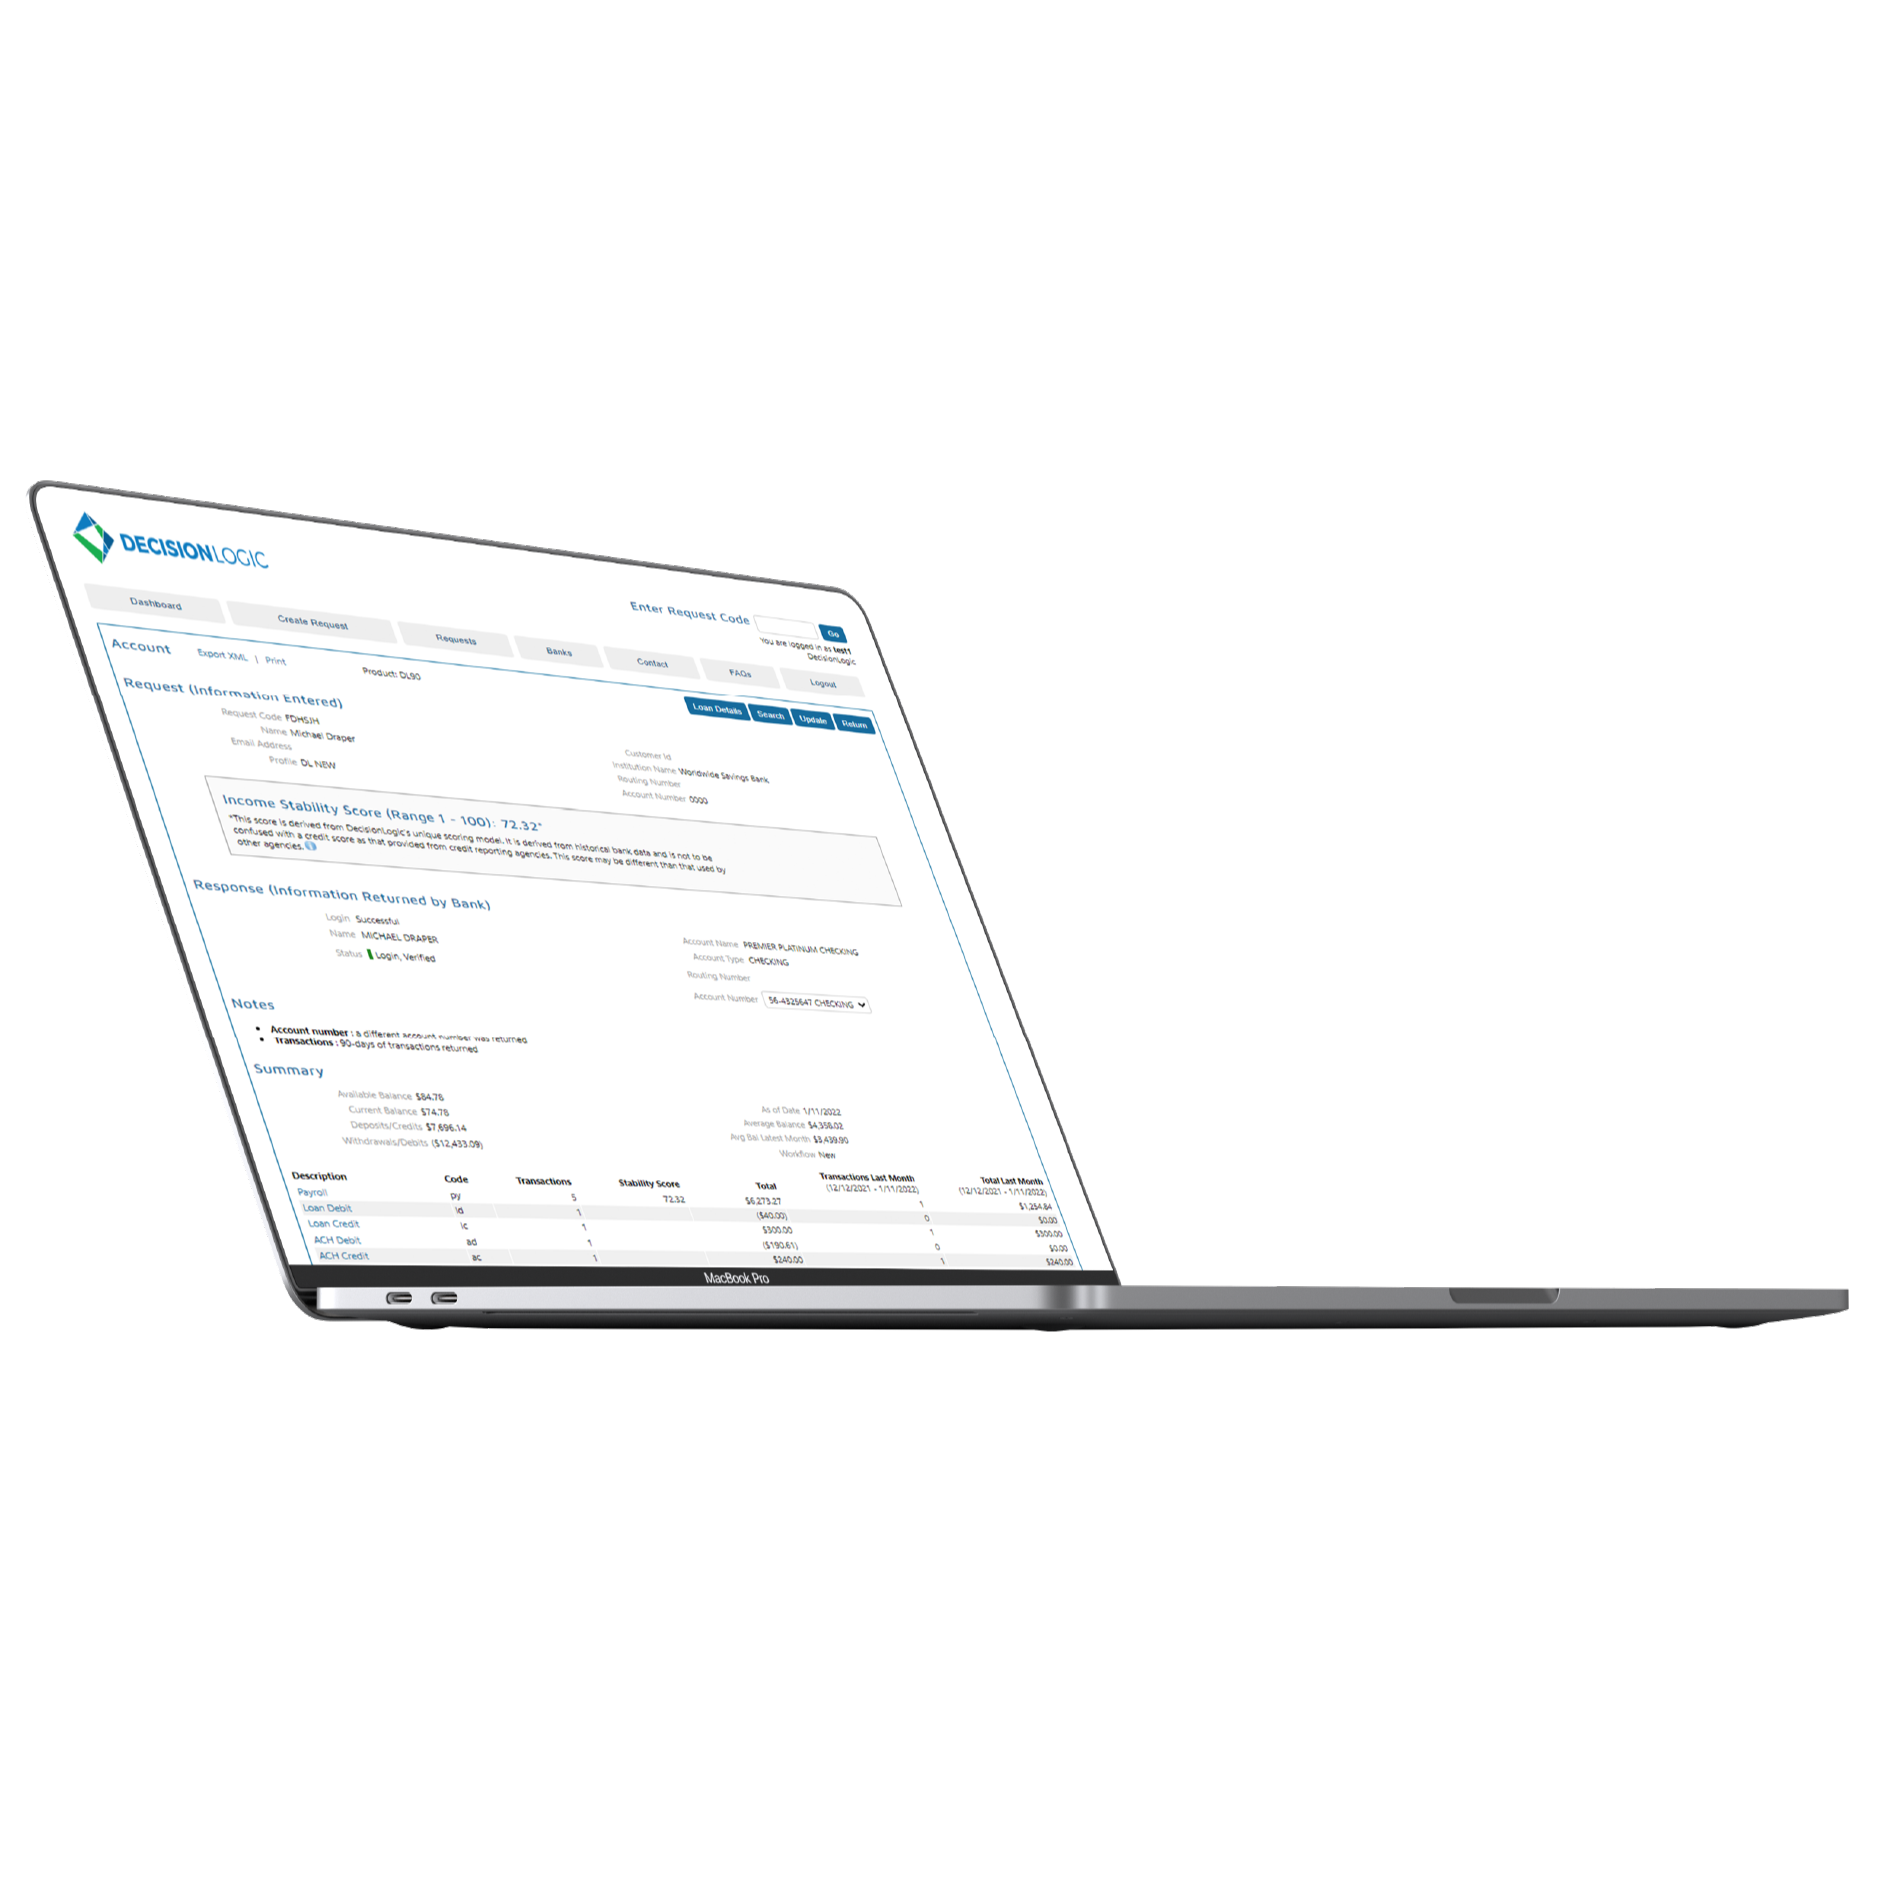
4. The institution opens the report

DecisionLogic published example of an institution viewing a verification report

The requesting institution receives a read-only report. The screen example includes account information, balances and transaction summaries.

What the lender and underwriter do with DecisionLogic

From the institution’s side, the first job is to create the right request and explain it clearly. A merchant should know which institution needs the information, which application it relates to and where to get help.

Lender initiating a bank-verification request for an applicant

Sending and managing the verification request

DecisionLogic offers a lender portal as well as integration options. A portal user can manage the request in the provider’s interface; an integrated institution can incorporate the workflow into its own systems. That choice affects the experience the merchant sees.

The institution’s workflow

The report supports a decision. The institution remains responsible for the application.

  1. Request the right information

    Associate the request with the application and tell the merchant which account is needed.

  2. Review the returned data

    Check the connection result, available history, account details and relevant activity.

  3. Resolve questions and respond

    Ask about missing records or unusual activity, then communicate the next application step.

An institution may use a portal, an API integration or additional analytics. Not every institution enables the same features.

Reading the report in context

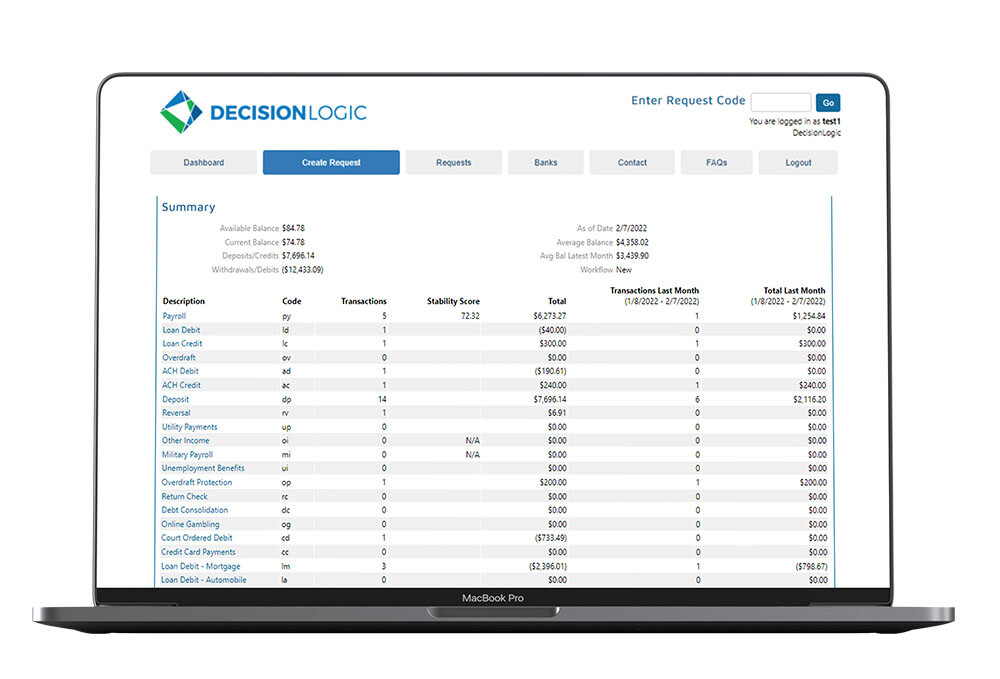
The published report below illustrates categorized transactions and summary information. It is a provider sample containing historical example data. Its dates, balances and score are not current customer information or lending thresholds.

DecisionLogic published report sample with categorized transactions and account summaries
Source: DecisionLogic’s published report example. Historical sample data, not a current customer or an approval standard. View the provider’s original walkthrough.

An underwriter needs to understand the story behind those records. A slow month may reflect seasonality. Transfers can inflate deposits without creating new revenue. A recurring debit may be an existing obligation that needs to be considered alongside a proposed payment. A report makes those questions easier to identify; it does not answer all of them on its own.

Underwriter reviewing account activity and cash-flow information
  • Account and ownership details: check that the returned information matches the account and applicant being reviewed.
  • Balances and cash-flow patterns: look beyond a single day’s balance and consider the available period.
  • Incoming transactions: distinguish operating receipts from transfers, refunds and financing proceeds.
  • Outgoing transactions: understand recurring expenses, debt payments and other commitments.
  • Missing information: clarify gaps or categorization issues before relying on the report.

A business cash-flow example

Suppose an account shows $40,000 in incoming transactions: $25,000 from customers, $10,000 transferred from another business account and $5,000 from new financing. The $40,000 total is not the same as $40,000 in sales. A reviewer needs to separate the sources and consider the payments attached to that new financing.

This hypothetical example explains why a lender may ask follow-up questions after verification. It is not a customer case or a DecisionLogic scoring formula. These are practical review considerations, not a claim that every institution applies the same underwriting rules.

Is Decision Logic legit and safe to use?

DecisionLogic is a real financial-data service operated by Clarilogic, Inc. It publishes product information, security practices, consumer resources and support channels. That establishes the provider’s identity. It does not establish that every message bearing its name came from a legitimate lender.

If you receive an unexpected link, call the institution using a number from your existing records or its verified website. Confirm the application and the reason for the request before entering information. A familiar logo alone is not enough.

Merchant and institution sharing authorized records through a permission gateway

How DecisionLogic made sharing bank information safer

In some older business-funding workflows, funders asked applicants for a month-to-date (MTD) screenshot or required a manual bank-login call with an underwriter. The goal was to check recent account activity and confirm that the statements submitted during underwriting were authentic. In a manual-login call, the applicant gave the underwriter access to online banking so the underwriter could pull the records and compare them with what had been submitted.

Both methods had drawbacks. A screenshot could be edited, cropped or leave out transactions, so it was not fraud-proof. Letting someone into an online-banking account introduced a different concern: the applicant was giving another person account access to complete what should have been a request for financial records.

DecisionLogic helped make that exchange safer. The applicant completes the verification flow and authorizes the connection, while the requesting bank, funder or other institution receives a read-only report. As DecisionLogic’s borrower FAQ explains, the institution can review the returned information without seeing the applicant’s online-banking login credentials or logging in as the applicant.

For the borrower, this reduces the need to hand account access to a representative. For the underwriter, records obtained from the financial institution provide a stronger basis for checking submitted statements than a screenshot alone. That reduces opportunities to pass off altered screenshots as genuine bank activity. It does not eliminate every form of fraud, and applicants should still verify the requesting institution and understand what information they are authorizing it to receive.

What security protections does DecisionLogic describe?

Its security page describes encryption in transit and at rest, role-based access controls, security testing and employee security training. These are the provider’s published practices, not an independent security audit by Excel Capital. No bank-data service can promise zero risk.

According to DecisionLogic’s borrower FAQ, neither DecisionLogic nor the requesting lender sees or stores your online-banking login credentials. This is the provider’s statement about credentials, not a claim that no financial data is retained. An institution can still receive and retain a report under the applicable terms.

What can an institution see?

Depending on the bank connection, the products used and your authorization, the returned information can include account identifiers and ownership details, balances, transaction records and derived summaries. Read the request rather than assuming it shares only your current balance.

Four things that should not be confused

Banking credentials
The information used to authenticate. DecisionLogic’s FAQ says the provider and lender cannot see these credentials.
Financial records
The account information and activity returned through an authorized connection. A read-only report still contains sensitive information.
Refresh access
An enabled feature can retrieve newer available data without another borrower interaction. Ask about scope, duration and how to stop access.
Payment authorization
Permission to debit an account is a separate matter. A verification report alone does not establish that you agreed to a payment.

Read the verification consent and any separate financing or payment agreement. Sources: FAQ, Refresh product description and service terms.

Can the institution check the account again?

DecisionLogic advertises a Refresh feature for obtaining newer available data without another borrower interaction. Do not assume that completing a single link means access can happen only once. Ask the institution which permissions apply to your request, whether ongoing access is enabled and how you can withdraw that permission.

Disconnecting a connection and deleting information already received are different actions. For questions about a DecisionLogic report, access, disputes or deletion requests, start with its consumer information page and the requesting institution. DecisionLogic’s website privacy policy has scope limitations, so the terms and notices associated with the actual service also matter.

Does DecisionLogic let someone withdraw money?

Its published verification process gives the institution a read-only bank report. Reviewing that report is different from initiating a debit. If a lender also asks you to authorize payments, read that separate authorization and repayment agreement carefully. Ask the institution to explain any wording you do not understand before agreeing.

DecisionLogic products and what each means for your application

DecisionLogic offers more than one bank-verification workflow. Its products page groups the core offering into Instant Account Verification, Identity Verification and Summary Analytics. Institutions can add capabilities around those products.

Instant Account Verification (IAV)

IAV is the part most merchants encounter when a lender requests bank information. DecisionLogic describes a blended connection approach using data partners and open-banking APIs. It supplies account and transaction information for the institution’s review. The available records and history depend on the connection and request; there is no reason to assume every bank returns the same period or fields.

Identity Verification (IDV) and DL Match

DecisionLogic’s DL Match identity-verification tool is powered by Experian. It checks key personal information and flags risk factors. This is distinct from signing in to a bank account. An institution decides whether to use it. A DecisionLogic bank request does not automatically mean you will be asked for a selfie or a document upload.

Summary Analytics and Income Stability Score

Summary Analytics categorizes income and expenses and applies proprietary scoring to highlight patterns. The separately listed Income Stability Score draws on available account data to assess payroll and income patterns. It is a provider-specific measure, not a FICO score or a universal loan-approval threshold. Consumer payroll patterns also need different interpretation from a business’s revenue.

Refresh, portal access and integrations

Refresh retrieves newer available data without another borrower interaction, subject to the applicable connection and authorization. Portal access gives institutions a way to manage requests without building a custom integration. Integration and automation options include APIs, custom rules and automated workflows that institutions can configure around their review process.

What you do, and what the institution may use

Some products operate behind the scenes. They are not all separate steps for the merchant.

Connect the requested bank account

Institution tool: IAV through a portal or integrated workflow.

Purpose: Receive available bank information for review.

Provide identity details if requested

Institution tool: IDV.

Purpose: Validate personal information separately from the bank connection.

Answer questions about the records

Institution tool: Summary Analytics and relevant scores.

Purpose: Interpret transactions and investigate patterns.

Understand any continuing access

Institution tool: Refresh or monitoring features, if enabled.

Purpose: Review newer information under the applicable authorization.

Excel Capital does not claim to use every product shown. The requesting institution determines its own setup.

Other named offerings and support features

DecisionLogic also promotes DL NextCheck for automated refresh and monitoring. Its NextCheck overview describes using updated account information throughout the lending process. The provider also advertises a First Payment Default Score on its homepage and DL Precision Engine as an automated-decisioning offering that does not require an integration. Institutions should confirm the available scoring, decisioning capabilities and terms directly with DecisionLogic for their intended use.

The products page lists live support, free workflow reviews, free integration and support, unlimited free training, and no contracts or monthly minimums. Its process overview also describes ongoing support for institutions and their borrowers, with customer and technical support included at no extra charge. These are the provider’s advertised service features; they do not mean every report or product is free. Institutions should confirm current pricing and what is included.

Decision Logic reviews: benefits, limitations, and our assessment

Our assessment focuses on what a business owner needs to understand before completing a request. Excel Capital facilitates DecisionLogic requests for institutions that use it. We are not presenting this article as an independent technical audit or a test of every DecisionLogic product.

Where it can help

  • A clearer document exchange: an authorized bank connection can give an institution structured records to review.
  • Less manual statement handling: available bank data can reduce the back-and-forth involved in collecting records.
  • A more organized review: transaction categories and summaries can help an institution identify questions earlier.

Where friction remains

  • Bank connections can fail: access, authentication or connection issues can interrupt the process.
  • Permissions deserve attention: a quick connection can still involve substantial financial information or continuing access.
  • Reports need interpretation: categorization and balances cannot explain every business circumstance.
  • Verification is not approval: a completed request does not settle the lender’s remaining requirements.

Third-party review sources

When checked on October 17, 2026, DecisionLogic’s BBB profile listed accreditation and an A+ business rating. A BBB rating is different from an average customer star rating and is not a technical security assessment. You can use the profile to examine the company’s identity and any available customer reviews or complaints.

DecisionLogic’s G2 profile provides feedback about the financial-data product. Look at the reviewer’s role, review date and number of reviews before drawing a conclusion. An institution user’s experience can help explain the reporting tools, but it does not predict a merchant’s loan outcome.

Reading reviews of lenders that use DecisionLogic

Separate a complaint about connecting a bank account from a complaint about a lender’s rate, approval decision or funding delay. They concern different parts of the experience. When reading third-party reviews, check the company name, website, date and whether the reviewer describes the bank-verification service. Search results also include restaurant software and employer reviews with similar names.

For merchants, the useful question is whether the requesting institution has explained the purpose, permissions and next steps clearly. For institutions, evaluate bank coverage for your applicants, data quality, support, consent handling and integration fit. A generic star rating cannot answer those questions for your particular workflow.

DecisionLogic vs. Plaid and other bank-verification platforms

DecisionLogic is not the only platform that can connect to bank information. Plaid and Mastercard’s open-finance services are other examples. Products, connections, data access and institution workflows differ, so it is misleading to call one service the only secure way to verify a bank account.

Our Plaid review and bank-verification walkthrough explains the provider Excel Capital uses directly. Our Plaid safety guide looks more closely at its permissions and security questions. Mastercard describes its own options in its small-business open-finance overview.

For an existing application, use the verification method requested by the institution. You generally cannot replace a DecisionLogic request with a Plaid connection on your own. Ask whether an alternative is available if you are uncomfortable connecting or your bank is not supported.

Decision Logic not working? Where to start

A failed connection does not tell you whether your application qualifies for financing. First identify where the process stopped, then contact the party that can resolve that step.

Match the problem to the next step

No link, wrong request or expired link
Ask the requesting institution to confirm the application and send a replacement link.
Bank sign-in does not work
Check your access on the bank’s own website. Resolve a locked account or password problem with the bank.
Security code does not arrive
Check the phone or authentication method registered with your bank. Complete the bank’s security prompt through the connection flow.
The connection keeps spinning
DecisionLogic’s FAQ directs users to support if loading continues for more than three minutes. Describe the error without sending passwords.
Your bank or requested account is unavailable
Tell the institution what is missing and ask which supported connection or alternative documentation it accepts.
Verification succeeded, but there is no loan update
Contact the lender or funding representative. DecisionLogic does not control the application decision or disbursement.

Official help: DecisionLogic FAQ and service status.

DecisionLogic lists (858) 586-0202 and support@decisionlogic.com for support. For an application facilitated by Excel Capital, your funding representative can help identify the requesting institution and next step. Avoid sending account passwords or authentication codes in support messages.

Frequently asked questions

What is Decision Logic bank verification?

It is an authorized connection that supplies bank-account information to a requesting institution. The institution uses the returned records as part of its own review. DecisionLogic is the service provider, not the bank holding your deposits or the lender deciding your application.

Why does a lender want my bank login?

The connection process authenticates access to the account whose records you are authorizing. Follow the verification flow rather than sending credentials to the lender. DecisionLogic’s FAQ says the lender and DecisionLogic cannot see your online-banking login credentials.

How long does DecisionLogic take?

Authentication and data retrieval can complete quickly, but bank security prompts, connectivity and missing information can cause delays. Do not confuse connection time with loan-review or funding time. Ask the institution for its application timeline.

How far back can DecisionLogic see?

The available transaction period depends on the connection and request. Ask the institution which history it needs and check the permissions presented. Older references to 90-day or 365-day products should not be treated as a universal limit for every current request.

Does DecisionLogic check my credit?

Bank verification and a credit-bureau inquiry are different activities. An institution may have separate identity, credit or other application checks. Ask which checks it will perform and review their authorizations. Do not treat a proprietary income score as your credit-bureau score.

Can I use bank statements instead?

Ask the requesting institution. Some may accept an alternative process; others may require a supported electronic verification. Do not assume that emailing a statement completes the existing request.

Can I use DecisionLogic without online banking?

The bank-connection process requires the appropriate access to your account. DecisionLogic’s FAQ directs users without online banking to the lender to discuss another option.

Why am I being asked to verify again?

The institution may need a different account, a new request or newer information. Confirm the reason with your contact. A second request does not, by itself, establish approval or a problem with the application.

Get help with verification or explore business financing

Already completing a request? Contact the institution that sent it. If Excel Capital is helping with your application, contact our team so we can clarify the request and direct you to the right next step.

Still comparing business financing? You can explore funding options with Excel Capital. The appropriate verification process depends on the institution involved. Connecting a bank account does not commit an institution to approve or fund an application.

About this review

Product and process information checked October 17, 2026 against DecisionLogic’s products, walkthrough, FAQ, security information, terms and consumer resources. The four editorial illustrations were created with AI to explain example roles; they do not depict actual clients or staff. The product screens are DecisionLogic’s published examples. Products and connection screens can change.

How to Write a Business Plan: A Step-by-Step Guide

HOW TO WRITE A BUSINESS PLAN FEATURED IMAGE

Want to know how write a business plan? Not sure what needs to go in each section or how long it should be? Read on to find out.

How to Write a Business Plan

Every small business has a beginning. It’s an exciting time with a lot to look forward to.

But the launch of every small business is not created equal.

If you want to make sure your business gets started off on the right foot, you need to make sure that launch includes a critical element: a well-crafted business plan.

Creating a business plan is an integral part of starting a business. It’s an A-to-Z guide to running your business the way you want (and need, for it to be successful).

That’s why in this guide, we’ll show you everything you need to know about writing a business plan, including:

  • What is a business plan? 
  • The 8 steps to writing your business plan
  • How long should a business plan be?
  • Business plan examples

So, let’s start with the obvious question:

What Is a Business Plan?

A business plan is a guide of sorts, both for you and those interested in your business (i.e. potential investors), that lays out your plan for growing and developing your business. 

It tells the story of who you are as a company, what your goals are, and how you’re going to get there. And it does all that while being as thorough as possible. 

What is a business plan?

Goals should have dates, a detailed marketing plan to back that up.

A product strategy that makes it clear why you’re selling what you’re selling and how you’re going to make it better.

And, finally, a financial plan that shows how you’re going to manage all that money your business is going to be making.

If there is any part of running a business that you’re unfamiliar with, this will be the point that you’ll want to start doing some research, as you’ll need a basic grasp of everything from marketing, product development, financials, and your organizational structure to create a good business plan. 

What Needs to Be In a Business Plan? 8 Steps to Writing a Business Plan

Now that we’ve got that out of the way, what are you supposed to put into your business plan? 

There are 8 things every good business plan should have.

They are:

8 Steps to Writing a Business Plan

  1. Executive summary
  2. Company overview
  3. Market analysis
  4. Organizational structure
  5. Product strategy
  6. Marketing strategy
  7. Financial plan
  8. Appendix

With a thorough description of each of these areas, you’ll have a detailed business plan in place that should not only guide you in your business’ development but make you look good with investors. 

How to Write a Business Plan: A Step-by-Step Guide

Creating a business plan can seem a bit overwhelming when you consider everything that goes into one. 

But if you take it one part at a time, you’ll find the plan coming together before you know it. 

Now, let’s jump into those 8 steps we just talked about and do just that: break each part down into easy steps to follow.

And remember: If you’re unsure of anything right now, just write down what you do know about each section. Later, you can come back and flesh that section out. 

With that said, here are the 8 parts of every business plan:

1. Write an executive summary

HOW TO WRITE AN EXECUTIVE SUMMARY

First, you’ll want to write your executive summary.

An executive summary is a summary of where your business is now and where you want it to go. If you’re trying to interest investors, this is also a good place to add a little bit about what makes you stand out as a company and why your company is going to be a success.

How long should it page? About a page is fine, though it could be longer.

If that feels impossible, consider that your executive summary is exactly that: a summary. It’s not a thorough breakdown.

Think of your executive summary as the prelude to the rest of your business plan. Later, you’ll go more into your product, marketing, positioning, and financials. For now, just give them an effective and concise summary of the most important parts.

What are those? The SBA recommends the executive summary of a business plan includes these 6 pieces of information:

  1. Mission statement: Describe your business and its goals in a paragraph.
  2. General company information: This includes the date of your company’s formation, the owners/founders, their roles, and how many employees you have.
  3. Highlight successes: Place any notable data (in visual form such as a graph) regarding the growth of your business. Remember, your business plan should impress potential investors (unless you’re solely doing it for your own use, in which case this can be skipped), so you’ll want to offer something that signals you’re bound for success if you have it or other positive notes about why you’ll be successful if you don’t have that.
  4. Products and/or services: Describe your product or service and your market.
  5. Financials: This section is important if you’re looking for investors as you’ll list your funding goals as well as anyone you’ve already worked with in the past to secure funding. 
  6. Plans and goals: What are your goals for the future. The last part of your executive summary should mention what those goals or plans are.

This first section might seem like a doozy, but keep in mind that it’s arguably the most important section of your business plan because it summarizes everything that will come after it. 

The great part about starting with this too is that it will help give you a better idea of what you’re going to put in each of the proceeding sections, making the rest of the business plan go smoothly. 

2. Complete your company overview

Next is your company overview. Consider this the basic information that those interested in your business will need to know about how you function.

That includes: 

  • What does your business do? You spent a lot of time selling your business in the previous section, now you need to make it crystal clear what your business does. 
  • Your market: Who do you sell to? What is the need you’re serving? How are you serving that need?
  • Your business type (legal structure): Explain what business structure you are and why you’ve decided to choose that structure. Also, list how ownership is divided and managed. 

Make sure your answers to these points are to the point. This is an overview, like the last section, so you don’t have to spill all the details (not until later). 

However, you also want to make sure it paints an attractive view of your company if you’re preparing this to acquire funding.

3. Do a market analysis

HOW TO DO A MARKET ANALYSIS

Next on the list is a market analysis. This is an analysis of your industry, your competitors, and any other important information relative to your market. 

Now is when we move from concise overviews to more detailed breakdowns of the major areas of a business, so you’re going to want to make sure to get into the nitty-gritty here and show that you understand the market you’re stepping into. 

And if you’re just doing this for your own use, it’s a great exercise it making sure you know enough about your industry and market as a whole. 

Make sure to include this information in your market analysis:

  • Industry summary: List the basic information about your industry: its size, growth, current health, and any data connected to it related to trends or anything else. 
  • Target market demographics: Now focus in on your target market: who specifically are you selling to? Beyond that, you’ll want to talk about who your customers are, where they’re located, and any other information relative to demographics.
  • Target market size: How big is your target? How fast is it growing? These are also questions you’ll want to answer in this section. 
  • Target market behavior: Where does your target market make purchases? When do they buy? List anything related to your market’s behavior. 
  • Market share: How much market share do you predict being able to capture? 
  • Pricing tolerance: You’ll also want to know everything you can about what you can and should be pricing your product at. 
  • Market entry conditions: What barriers are there to entering your target market? You need to be aware of these before jumping in, whether it’s licensing, regulations, expertise in personnel, etc. 
  • Competitors: Who are your competitors? What makes them stand out? How will you be better than them and/or stand apart? What are their strengths and weaknesses?

As you might be able to tell already, this is possibly the most research-intensive part of the entire business plan.

However, having said that, the research you’ll be doing to complete this section is invaluable, even necessary, to your business’ success. 

Leave out even one of the above sections and you’ll be flying in dark without all the information you’ll need to make smart decisions as your business grows and is presented with challenges. 

4. Define your organizational structure

Moving on from your market analysis, the next deep-dive is into your organizational structure. 

This section is all about defining what kind of system your business uses to manage itself. 

Who does what? Who reports to who? How do your teams break up? These are just some of the questions you’ll want to answer. 

Here’s everything you’ll need to define:

  • Organizational structure: Create a visual document/chart of some kind that shows how your business is structured, including who has what role and who is in charge of managing what part of the business. 
  • Ownership: If you have partners, how does ownership break down? Who is responsible for what? 
  • Backgrounds: Detail the backgrounds of all notable team members including partners, managers, and your board of directors. This section can be quite long, and that’s okay. Make sure not to leave anyone out. 
  • Future hires: How does your team need to expand in the future? What key roles do you need to fill on the way to accomplishing your goals?

5. Define your product strategy

Now let’s move on to your product strategy. This mostly has to do with product development and the research involved in positioning your product within your market. 

Here’s everything to include in this section:

  • A general overview of the product and/or service: What product or service(s) do you offer? What need does it fill in your market for your target customer?
  • Product development stage: Is your product complete and ready to ship? Have you sold units/acquired customers already? Is it just in the ideation stage? If it’s the latter, describe what you’ll be doing to complete the product or service offering to have it ready to ship. 
  • Patents / Intellectual property: If your product or service depends upon a patent or some kind of intellectual property, explain what where they stand. 
  • Sourcing and fulfillment: Who is making the product? Where are you shipping it from? Make sure this is clear to you now there are no problems down the line when it’s time to start selling. 

Remember that as you craft this section, like all the other sections, you want to show that you know what you’re talking to if you’re preparing your business plan for potential investors. 

Make your product, service, or idea look good and explain why you believe it will be successful. 

6. Define your marketing strategy

HOW TO DEFINE YOUR MARKET STRATEGY

Next, with your market and product sections complete, you’re well-prepared to move on to defining your marketing strategy.

In this section, include any and all relevant information related to how you’re going to market your product or service. 

This includes: 

  • Advertising and promotion: How will you market your product or service? This section is likely to be on the longer end as you should be detailing not just how but why. 
  • Positioning: How will you be positioning your product or service? What is your reasoning supporting this decision? 
  • Sales strategy: How will your sales team function? Will you have one at all? How will they work with marketing? At what stage will they begin interacting with the customer and what kind of overall sales process will be implemented? 
  • Validation markers: You should have several hypothesis or tests in place to validate your offering, it’s positioning, and marketing and sales efforts. Without these things in place, there’s no way to know if your product or service is a success or failure and no reference point to come back to to make improvements. 

This is one of the main sections you may yet have quite a few question marks on. As we mentioned earlier, don’t worry. Just do your best to fill out as much of this section as possible, do the necessary research, then come back and finish it later if necessary. 

7. Write your financial plan

The final step in terms of the written information you need to provide for your business plan, it’s time to dive into the financial side of things.

How much does your product cost to source? How much are you selling it for? How many units can you move in a month? What is your overhead and other costs? These are just some of the questions you’ll want to answer.

If your business has been around for a bit, the best place to start is your current financial reports. Things like your profit and loss report, income and revenue statements, accounts receivable and payable, and any other financial reports.

And if you don’t have anything, create something that shows projections for important financial figures such as sales and revenue. Just make sure you’re not making numbers up out of thin air. Support these projections with market and competitor research. 

These are some of the documents you can include relevant to projecting future financials:

  • Cash flow forecast
  • Projected income
  • Capital expenditure budget

If including projections, make sure to include them for the next 12-month period as well as either 3 or 5 years at least for a more long-term view.

With those projections out of the way, you’ll also want to include a section on funding. If you’re looking to acquire investors or will be investing a portion of your own funds, here is where you’ll outline exactly what you’ll need.

Make sure to include:

  • How much funding you’ll need to get started
  • Projected future funding needs
  • And what those funds will be used for

After reading this section of your business plan, an investor should come away with a clear understanding of why you need funding and what acquiring that funding will allow you to do for the business.

8. Include an appendix 

The final step in good a business plan is less new information as it is the place where you stuff all those things that are important but might not have fit anywhere else: an appendix.

In this appendix, you’ll want to stash any and all important data or other supporting information you didn’t include throughout your plan already. 

That includes additional: 

  • Data: Charts, graphs, you name it.
  • Details: Anything relevant to your business that may not have fit anywhere else.
  • Legal documents
  • Additional images: If you’re a restaurant, additional menu item images, you get the idea. 
  • Resumes: If your plan may have been lacking in supporting data or you simply think it will help, you can include your resume and the resume of any of your founders or key managers as a supporting document.

Anything that you feel is important or valuable but just didn’t quite fit in the plan should go here. And since it’s a gathering of somewhat random items, make sure to include a table of contents to make this section easier to navigate. 

How long should a business plan be?

At this point, one of the questions you might be left with is: exactly how long does my business plan need to be?

Fortunately, that’s an easy question to answer:

As long as it needs to be to succinctly outline or define each major aspect of your business. 

The SBA suggests a business plan be no more than 50 pages. However, that all depends whether you’ll have investors reviewing that plan or not. If it’s just for your own personal use, even a few pages can suffice. 

Your marketing plan might be a few detailed paragraphs. Then again, it might be a bit more involved and require several pages. 

Ultimately how long each section will be will depend on what you need to say and your ability to break down that information as succinctly as possible (without leaving out any vital information). 

Business plan examples: What does a business plan look like?

Now that you know how to write a business plan, let’s go over some business plan samples.

We know that was a lot of steps, and it might not be entirely clear what your business plan should look like, so we’ve gathered some great samples as additional resources that you can review to get a better idea of what your business can look like.

Keep in mind that if you use any kind of software that allows you to put together a business plan, such as:

then you won’t need to worry about looking over samples as they will guide you through the process. Still, it can be nice to see an example to make sure you’re creating your business plan right. 

With that said, here are a few business plan examples to help you get a better idea of how your completed plan should look: 

For the most part, business plans are the same across industries, with only small differences.

Keep in mind that once your business plan is complete, take some time to show it to everyone from your business partners to key personnel to get their feedback. 

The more eyes who are directly connected to your company’s goings-on who look at it, the better it will be and the more buy-in you’ll be able to get right from the get-go in terms of your company mission and direction of each major moving part.

Get the Startup Capital Your Business Needs with Excel Capital

Now you know how to write a proper business plan, there’s only one thing left to do: create it.

Take the steps we’ve broken down here and start writing a business plan of your own one step at a time, making sure that each section is as comprehensive as possible.

After all, this is going to serve as a guidebook of sorts that will help direct your entire business’ dealings for years to come, so it’s worth taking some time to make it right.

Getting things right is also important with regards to funding.

With the right funding in hand, you can grow and establish your business faster and keep things running smoothly.

At Excel Capital, we offer a variety of business funding tools, many which you can be approved on with low or no credit and fund in as little as 24-48 hours.

Apply to get the funding your business needs with Excel Capital today:

Get the capital your business needs without the hassle. Apply for a small business loan with Excel Capital: Apply Now

Bizfi Secrets Finally Revealed – Everything You Need to Know!

EXCELCAPITAL - BIZ FI

Bizfi: The Rise (and Fall) of a Fintech Trailblazer

The year was 2005. 

A brand-new company– Merchant Cash and Capital (MCC), later known as Bizfi– was shaking up both the financial and technology industries in the United States with a revolutionary new approach to conducting business (especially online).

The mission for Merchant Cash and Capital was simple and straightforward in these early days. MCC would act as a purchaser of future credit card sales, a brand-new concept in 2005 and a move that laid down the foundation for the future financial technology movement of today.

Growing rapidly in the first five years of its existence, Merchant Cash and Capital founder Stephen Sheinbaum decided to establish a secondary operation– Next Level Funding– that acted as a broker for small business owners and entrepreneurs that were having a tough time getting financing in the middle of the Great Recession. 

Next Level Funding was going to help drive business to Bizfi, still then Merchant Cash and Capital, and accelerate the growth of their unsecured business loans through direct calling or telemarketing and other online sales channels.

The fintech movement takes off

At this stage in the early history of the fintech movement, online businesses were beginning to take off, opening up a world of opportunity for entrepreneurial endeavors that simply hadn’t existed before. 

Shopping online had finally “gone mainstream” and people were familiar with– and maybe more importantly comfortable with– sending their personal, private, and payment information to strangers over the internet.

On the flip side of things, traditional lenders and business owners were anything but familiar with these online enterprises. 

They remembered the Dot Com Bubble of the 1990s– and the way it blew up in many business owner’s faces– and looked more than a little bit skeptically at what people were calling the true power of the Internet and how it might revolutionize business forever.

Combine that with the fact that the Great Recession was in full swing (peaking in 2008, three years after Merchant Cash and Capital was founded) and traditional businesses were folding left and right and creditors were finding more people defaulting on their loans than ever before, and it’s easy to see why a company like Merchant Cash and Capital was able to swing in on a chandelier and start gobbling up market share.

Bizfi is formed

It took 10 years of rapid expansion to decide that it was time to bring both Merchant Cash and Capital and Next Level Funding under the same roof, operating them as a new single entity.

Under the leadership of founder Stephen Sheinbaum, the organization was restructured and reorganized, offices were consolidated, and the workforce was brought under a single roof. And, at the same time, there was rapid expansion. 

Ten years from MCC’s founding, 2015 saw Merchant Cash and Capital and Next Level Funding merge under the same roof of the Bizfi moniker. 

And, as it would have it, success for the company formally known as Merchant Cash and Capital came very, very easy.

By the time 2016 rolled around even the most old-school and traditional of lenders recognized just how powerful, important, and influential the fintech industry was going to be. 

Bizfi had a huge head start on the rest of the pack, as according to industry reports they were one of the largest originators of merchant cash advance packages in existence at the time.

And then, just like that… the company disappeared almost completely. 

What drove Bizfi out of business?

Within less than a year of the time that it seemed inevitable they would take their place as a top player in a quickly growing industry, Bizfi was out of business. 

Journalists that had been following the meteoric rise were stunned. Industry experts couldn’t figure out what had happened and even those that had been working with Bizfi were shocked to learn that they were going to be shuttering their doors forever just when things looked like they were poised to take off like a rocket.

A postmortem is still being conducted on the company formerly known as Bizfi, partly due to the fact that it didn’t cease operations until late 2017, and much of what happened during the period between 2016 and 2017 that could have changed the company’s fate so drastically remains unclear.

One thing, however, is certain: Between 2016 and early 2017, Bizfi had grown too large far too quickly and that led to several factors that would eventually spiral out of control. 

Several factors likely contributed to driving Bizfi out of business, but there were primary red flags among those factors. 

Here are some of the primary factors that led to Bizfi going out of business:

They hired too many too quickly that did not have enough underwriting experience

Prioritizing closing deals, Bizfi hired quickly but not effectively, choosing to hire many who didn’t have enough underwriting experience. This led to a cascade of negative effects. 

First, underwriting managers were incentivized to fund as many deals as possible.

That might sound obvious, but they were encouraged to close deals to cover up their default percentage even if the deal didn’t make sense business-wise. 

As a result, they funded too many large deals with too high a risk. 

They funded deals for brokerages, also known as ISO shops, that shouldn’t have been funded, especially considering the size of the deal.

They lent heavily to young businesses

Bizfi was known at the time for offering entrepreneurs that only had six months of business experience under their belt and monthly revenues of at least $15,000 highly favorable financial packages that likely didn’t befit their financial or business standing. 

They found many new entrepreneurs who wanted to take advantage of their services, but those same deals quickly ran their businesses into the ground. 

After all, nearly 75% of all new businesses will eventually fail. Lending to such young businesses large cash sums was unheard of due to the risk, and unfortunately, Bizfi became a reason why that’s the case. 

They lent heavily in high-risk industries

Similarly, Bizfi also became a popular financing option with some of the riskier industries in the entrepreneurial world:

  • Brick-and-mortar retail shops
  • Restaurants and bars
  • Health and fitness centers
  • And business service operations 

These together made up the bulk of the Bizfi clientele, though each of those industries is considered high risk, high turnover, and has a high likelihood of failure in the first five years (SBA).

Eventually, Bizfi was sending more money out the door than they were bringing in, even though the bulk of their loans were short-term with sky-high interest rates. 

Compared to traditional lenders with 10% APR packages, Bizfi routinely offered loans that carried an APR of 150% or more– interest rates that most entrepreneurs found next to impossible to meet with any real consistency or regularity.

Eventually, Bizfi began searching for outside investment, especially as the business markets started to cool across the globe. Institutional interest in the fintech industry continued to remain strong, but many of these larger operations had little to no interest investing in a company as overextended as Bizfi had become.

And by July of 2017, the Bizfi party was officially declared over.

Bizfi closes its doors

In July of 2017, according to sources close to the company, all remaining employees were given a 90-day notice that the company was to cease operations and terminate their employment. 

It was the culmination of a series of layoffs, this the largest at more than 200 layoffs– many of which had been original employees at Merchant Cash and Capital or Next Level Funding.

In a CNBC interview in 2015, Bizfi founder Stephen Sheinbaum said that they had hopes of securing an equity investment that would allow them to go public by the following year in 2017. However, that investment never became a reality. 

July 2017: Bizfi sells its marketplace and other assets to World Business Lenders

Following the wave of layoffs, the assets held by Bizfi were divvied up and sold off, with many of them purchased at deeply discounted prices by World Business Lenders or WBL (formerly one of the top competitors for Bizfi in the fintech space). 

According to Bizfi founder Stephen Sheinbaum, who joined WBL as a managing director in July of 2017, WBL purchased the Bizfi brand, marketplace and other pieces of the company. 

August 2017: Bizfi sells its portfolio to Credibly

One month later, in a separate deal, Bizfi sold the servicing rights to its $250 million dollar portfolio and 5,200 merchants to another fellow competitor, Credibly.

“Acquiring the servicing rights of BizFi’s portfolio is a testament to our data-driven approach and laser focus on the working capital needs of small businesses,” Credibly founder and Co-CEO Ryan Rosett said in a press release. “We welcome our new customers and are committed to ensuring that their growth capital needs are met.”

According to a Bloomberg report, the deal allows Credibly to offer additional capital to that existing 5,200 customer base.

Quicken vs. QuickBooks: A “Quick” Comparison

EXCELCAPITAL - QUICKEN VS QUICKBOOKS

If you’re looking for accounting software that makes doing your own business accounting easier or looking to replace your accountant, both QuickBooks and Quicken are tried-and-true options that can’t be overlooked.

But which is better? And how do you know which is specifically better suited for your needs? 

That’s the purpose of this guide: to give you a detailed breakdown of both QuickBooks and Quicken so you know what their strong points are and which you should choose. 

Table of contents:

  1. QuickBooks vs. Quicken: A “Quick” Summary
  2. When Quicken is better
  3. When QuickBooks is better

QuickBooks vs. Quicken: A “Quick” Summary

Before we dive into our detailed review, for those who want the summarized version (or a “quick” summary– pun intended), we’ve broken down the essential points below.

If you rather not wade through a list of benefits and features and just want to get the short of it, this is for you: 

QUICKEN VS QUICKBOOKS

When to use QuickBooks

QuickBooks is by far the more robust accounting software. If your only reason for needing business accounting software is for, well, accounting, then QuickBooks is the better option by far.

QuickBooks is perfectly suited for small businesses while also having the necessary features to support you as you grow, no matter what direction your business goes. 

Check out QuickBooks.

QUICKEN VS QUICKBOOKS

When to use Quicken

While QuickBooks is the more expansive business tax software, Quicken has a niche that is sure to be attractive to some small business owners: it’s a great personal finance tool.

If you’re a sole proprietor, or just a solo business owner, an accounting + personal finance software might be a good fit for you. 

Quicken is also well-suited for those who own rental property as it gives you the ability to track tenants and manage your lease terms and rental rates. 

However, if these odd benefits aren’t of value to you, QuickBooks is hands-down the better software. 

Check out Quicken.

Quicken vs. QuickBooks: A summary of features

Here’s a breakdown of all key features available with QuickBooks/Quicken: 

QUICKEN VS QUICKBOOKS

Quicken Home & Business

Quicken’s Home & Business version is ideal for small business owners who need basic business accounting software but who also want to take advantage of Quicken’s useful personal finance features. 

On the business accounting side, Home & Business offers reports such as profit & loss and cash flow, helps you maximize tax savings, and will categorize your expenses. 

In addition to these business accounting features, you’ll have an effective personal finance manager as well. You’ll be able to create personal budget goals, track your spending, and even manage any financing you have.

Quicken Home & Business has one version and costs $100 for one year, as opposed to QuickBooks’ monthly setup. 

QuickBooks Small Business

QuickBooks Small Business, or QuickBooks Online, is the online version of QuickBooks accounting software. As opposed to Quicken’s Home & Business version, which offers a balance of basic personal and business features, QuickBooks offers a comprehensive suite of business features. 

There are several versions of QB’s online software, each proceeding plan offering a few additional features you may or may not care for, from adding additional users onto your account to printing 1099’s.

Depending on which plan you go with, QuickBooks by intuit will cost from $20 to $150 per month, including a $25 Simple Start, $40 Essentials, $70 Plus, and a $150 Advanced plan. 

Quicken vs. QuickBooks: When Quicken is better

So far, we’ve summarized the main takeaway of the comparison between QuickBooks and Quicken. 

However, if you’re looking for a more specific breakdown of what key benefits and drawbacks each software has, we’ll cover that in these next two sections. 

First, here’s where Quicken shines over QuickBooks:

Quicken is more affordable

One of the biggest differences between Quicken and QuickBooks is the fact that QB charges monthly, while Quicken’s software is an annual license.

What that means is you’ll only be paying $100 a year for Quicken’s Home & Business, but you’ll need to purchase it every year. However, with QuickBooks, you’ll likely be paying between $25-70 each month, which can quickly add up to far more than what you would pay with Quicken.

Quicken can track your finances (both business and personal)

If you need, or want, a single software that tracks both your business and personal finances, Quicken is a great option. 

With its mix of key personal finance and business accounting features, if you’re a solo business owner that works from home (or some equivalent), Quicken might give you everything you need in a single software. 

With Quicken, in addition to its basic accounting features, you can track investments, loans, and spending while managing your business accounting, though only if you do a few minor transactions here and there (otherwise it can get very messy). 

Quicken vs. QuickBooks: When QuickBooks is better

While Quicken is more affordable and offers the ability to track personal finances and do your business accounting in one place, QuickBooks stands above it in most regards.

Here’s when QuickBooks is better: 

QuickBooks has more robust accounting features

While Quicken has some definite positives, if you’re looking for a true business accounting software, it falls short in many ways.

QuickBooks offers business accounting features such as payroll, time management, inventory management, purchase orders, and automated invoice features.

In addition to these features, with QB you also have access to a slew of integrations for various accounting software that can make the software even more powerful. 

QuickBooks has better accessibility and usability

Of the two, QuickBooks is generally the more polished. The interface is cleaner and simpler and it’s easier to find what you need. 

Quicken, on the other hand, can seem a bit busy mostly because of its personal finance features, which just become an obstacle to wade through if you have no use for them. 

In addition to this, QuickBooks lives in the cloud, whereas Quicken is a basic desktop software. That means whatever happens to your computer, your information is safe. It also means you can access your software with QuickBooks even if you’re offline, something you can’t do with Quicken.

Quicken or QuickBooks: What is better for your business? 

Whether Quicken vs. Quickbooks is better mostly depends on how much use you can get out of their personal finance features.

If you have no use for personal accounting features, and instead just want the best business accounting software available, QuickBooks is the perfect option.

However, if you’re a solo business owner who manages all their own finances, something like Quicken can be incredibly useful in bringing everything together into one interface, making it easy to manage everything. 

Just make sure to remember the importance of keeping your business and personal finances separate. 

How Business Financing Changes During the Business Life Cycle

Finance has an integral part to play in a business. At a basic level, sufficient financing ensures that businesses have enough cash flow to maintain daily operations. This also assists in investment-related decisions, and facilitates smooth spending. A business’s ability to secure financing is essential for realizing tactical and strategic objectives.


Money greases the wheels of all businesses; it’s imperative that finances are carefully managed to ensure uninterrupted business activity, access to capital, and the ability to leverage opportunities as they arise. In an ideal world, businesses would generate sufficient revenue streams from sales of goods and services to cover costs. Businesses routinely face challenges in the marketplace, particularly with capital investments which require loans and other forms of financing.


The infancy stages of a business

Companies either succeed or they fail. What happens is largely dependent on a business’s ability to finance itself during the different stages of its life-cycle. There are typically 3 phases in a business life-cycle, notably the start-up phase, the growth phase, and the maturity phase. During the start-up phase of a business’s operations, financing comes from a variety of sources notably the owner/founder’s personal savings account, assistance from friends and family, small bank loans, and even credit cards.


If the business plan is ironclad, the business owner may be able to attract significant investment from angel investors, venture capitalists, and other sources of financing. For example, an entrepreneur may be willing to relinquish equity in the company for capital financing. This is a commonly used method by business owners who have a great business plan and investors who are eager to hitch their wagon to the business.


The growth phase of a business

During the growth phase of the business life-cycle, financing is equally important. Growth a.k.a. expansion necessitates significant investment in a business’s operations. Further, human resources are needed and this requires significant investment.


It is possible for businesses to tap into cash flow, but this precludes shareholders from taking dividends. External capital sources are essential during this phase of operations. Several options currently exist, including venture capital firms, but they can be detrimental to the owner’s equity and control over the company.


Fortunately, entrepreneurs who opt for this method of financing will receive a substantial advance upfront. Other options include bank loans. It is worth pointing out that interest can be deducted from all taxable income, meaning that debt-financed capital is inexpensive. If a business is listed on the stock exchange, the issuance of shares serves as an effective way to generate a stash of cash. A word of caution is advised: the business must be a proven performer.


During the growth phase, there is another method of generating financing, particularly for companies involved in selling high-end products including vehicles, machinery, equipment, luxury goods and the like. Unlike a convenience store cash business, luxury items or big-ticket items are typically paid off over time.  Assuming an invoice value of $100,000 on day 0, a company may not want to ‘carry’ the customer’s debt obligation for several weeks or months.


An effective way to obtain financing during the growth phase and the mature phase of a business is invoice financing. This financing method is primarily geared towards B2B organizations where the terms are 30, 60, or 90 days in duration. Invoice financing is a product of the invoices that are due to be paid to a business.


It is highly effective at maintaining a stable cash flow. Invoice financing comprises multiple different products for financing accounts receivable. This typically takes the form of invoice factoring – a form of invoice financing. Assuming a company is owed $100,000, invoice factoring can ensure that 80% of that amount is paid upfront by the invoice factoring company ($80,000) and the balance is paid back over time (30, 60, or 90 days) less the factoring fee (for example 0.5% – 2%).


The reason why businesses use invoice financing is to boost cash flow immediately so that day-to-day operations can be taken care of and the business doesn’t run into a negative cash flow situation. Invoice financing isn’t that difficult to implement, provided the debtors are trustworthy and have an established and verified relationship with the SME.


The mature phase of a business

During the mature phase of a business’s life-cycle, it typically has a proven track record of performance. This means that it is likely a creditworthy business, and able to tap short-term capital loans and financing from a variety of sources. If the business has a healthy balance sheet and income statement, it is much easier to access capital from a variety of markets such as equities markets, capital markets, and bond markets.


Other forms of financing such as peer-to-peer financing and investment financing remain on the table. As a rule, you can expect the infancy stage of the business to be funded primarily by the owner, close friends and family. As the business grows, other financing options open up, including bank loans, business loans, non-bank lenders, angel investors, and invoice financing options too. Once a business has an established presence with credible clients, invoice financing is a particularly attractive option available to business owners.

How General Contractors Benefit From Contractors Insurance

Working as a contractor has a lot of things going for it. You get to work flexible hours, the income is typically better, and you’re basically your own boss.


As a contractor, you also happen to carry specific responsibilities, among them purchasing contractors insurance.

Some states and industries may not require contractors insurance, but if you care about your business, you should get insurance protection regardless of whether it’s a requirement or not.

And if you’re a general contractor, then it’s even more imperative to have contractors insurance coverage. As the prime contractor of a construction project, a general contractor stands to benefit immensely from having the right contractors insurance policies.

The responsibilities of a general contractor

The overall operations of a construction site fall under the supervision of a general contractor. The management of employees,  acquiring construction business loans , dealing with contractors and suppliers, and reporting on a project’s progress to those that commissioned the project are also part of a general contractor’s responsibilities.

Being the one in charge of an entire construction project means a general contractor is responsible for lots of workers, subcontractors, equipment, tools, and materials. The job is so massive in scope that not getting the proper type of contractors insurance coverage for any of them would be the height of irresponsibility, at the very least.

So what benefits can a general contractor get from contractors insurance?

Protection from claims

Construction is one of the most dangerous professions in the world. Thousands of construction workers worldwide suffer injuries while on the job. Workers can also cause injuries or property damage to third parties within the construction site when, say, a tool slips from their hands. If you’re the general contractor of a project when the things mentioned above take place, you can expect claims and lawsuits to head in your direction.

However, if your company has workers’ compensation insurance, any employee injured while working for you won’t have to worry about the expenses for their medical treatment. And if they lose wages because of their inability to work, workers’ compensation will cover it. With workers’ compensation, there would be no need for you to pay what is due them out of pocket.

As for third parties that suffer injuries or sustain property damage in the middle of your construction project, any claim they make can be paid for by general liability insurance, if you have one. Even if claims turn into lawsuits, your general liability policy will cover your legal expenses as well as the compensation the court might award your employees if it rules in their favor.

Protection for tools, equipment, and materials

The tools, equipment, and materials in a construction site can prove to be tempting for thieves. In fact, theft is not uncommon in construction sites. You wouldn’t want to lose them to these people. You wouldn’t want them to suffer any kind of damage as well. You are, after all, responsible for all of them, being the general contractor.

However, if you have a builders risk insurance policy that provides protection for tools, equipment, and materials, you will have one less thing to worry about. Builders risk insurance also provides coverage for the structure itself. So if fire, wind, lightning, hail, explosion, vandalism, and vehicles or aircraft cause any damage to the structure, you can rest assured that most builders risk insurance policies will pay for it

Compliance with state requirements

As mentioned above, not all states require contractors insurance, but most of them do. As a general contractor, you would want your entire project to be compliant with regulations set forth by the state within which you’re operating. Having general liability insurance, workers’ compensation insurance, and other types of contractors insurance is resounding proof that you are, indeed, following state laws.

Reputation boost

Clients, in general, will always want protection for any project they’re paying for, and that’s why they usually hire contractors with the proper insurance coverage. In all likelihood, they’ll only choose from a pool of insured contractors, and ignore everyone else. Having the right contractors insurance policies assures you then that your company’s name will be in that shortlist for any major construction project.

Peace of mind

Few things can give a general contractor peace of mind better than proper contractors insurance coverage. Considering the risks involved in construction, you’ll be more at peace knowing that if anything untoward ever happens with your ongoing construction project, your contractors insurance provider will always have your back.

While no one purchases contractors insurance and actively wishes that they get to use it, having that kind of coverage prepares you for any complications that might take place. In an industry that can be particularly stressful for its players, having contractors insurance policies can make you feel confident that your business will go on, even when somebody gets hurt or property gets damaged, stolen or lost.

Understanding Your Business Credit Report

EXCELCAPITAL - BUSINESS CREDIT REPORT

Why should you check your business credit report?

Unlike your personal credit report, business credit is a bit more of an unknown.

How does it work? When does it come into play? How do I read my business credit report (because, if you haven’t seen yours yet, it’s somewhat different from a personal credit report)?

Your business credit report works largely the same way your personal credit report does: it serves as a tool for obtaining financing, in this case for your business, and sometimes for obtaining supplies from vendors. 

For those reasons alone, your business credit report is critically important to your business. 

Without a good business credit score, it will be much more difficult to obtain funding for your business when it needs it and it could cripple your ability to obtain supplies at ideal prices depending on your industry and type of business. 

So, you should not only check your business credit report now for potential errors and so that you understand what might be affecting your score, but make it a habit of checking up on it annually. 

But you probably have a few more questions about how your business credit report works. So, below, we’ll be covering:

  1. The 3 major business credit reports
  2. How to pull your business credit report
  3. Reading your business credit report 
  4. 3 Tricks to improve your business credit

First, let’s talk about the 3 major business credit bureaus and how they score your business.

The 3 major business credit reports

When it comes to your business credit report, there are 3 primary agencies and their associated credit reports: 

  1. Dun & Bradstreet
  2. Experian
  3. Equifax

Each of the above agencies provides a form of business credit report to gauge your business’ creditworthiness. However, each does so a bit differently (with its own entirely unique scoring model), and that’s really where business credit reports vary from personal credit.

Here’s more information about each agency and how their scoring system works: 

Dun & Bradstreet

Dun Bradstreet, or D&B, offers a comprehensive report that offers your D&B rating and D&B PAYDEX Score in addition to several other metrics. 

PAYDEX is D&B’s business credit scoring method, which uses a number system from 1 to 100, the higher the score the better. 

Preferably, you want a score of 80 or above, which means that your business generally makes payments on time and is in good standing. If your score is 49 or below, you’re considered a high credit risk.

Experian

Experian has several reports including its Business Credit Advantage Report, which provides financial scores, payment history, and even tips for improving your score. For the differences in score models, report access and monitoring costs, see our Dun & Bradstreet vs. Experian business credit comparison.

No matter which report you get, they use what they call their Intelliscore system, which uses a similar 1-100 scoring model as D&B’s but takes into account a wider range of factors than either D&B or Equifax:

BUSINESS CREDIT REPORT 1

However, these differences aside, a score of 76 or higher– almost identical to D&B’s 80– is the number to shoot for as it signifies that you’re at a low risk of defaulting on your loans. 

Experian also offers a financial stability risk score, which scores your business from 1 (best) to 5 (worst) based on the stability of the business as a whole:

BUSINESS CREDIT REPORT 2

Equifax

Equifax’s Small Business Credit Report collects your company’s payment history, credit utilization, score, and other information. 

Their scoring model is more similar to the personal credit scoring numbering system in that numbers range from 101-992, the higher the number the lower the risk and therefore better. 

Similar to Experian financial stability risk rating, Equifax also offers a Business Failure Score that measures how likely your business is to close within the next 12 months, with scores ranging from 1,000-1,880. Again, the higher the number the lower the calculated risk, so you want as high a number as possible for both scores. 

How to pull your business credit report

Unlike personal credit, there is no federal program in place that requires agencies to offer you one free credit report annually.

That means you’ll need to pay for your business credit report no matter how you slice it, but the process is simple and straightforward and you can obtain it directly from each of the three reporting agencies. 

Alternatively, you can sign up for free updates to your business credit report in many places (such as D&B here). However, you’ll probably still want to get that first business credit report copy so you know how you’re looking. 

Reading your business credit report 

All three main business credit reporting agencies offer some form of business credit report which you can obtain at a price. 

No matter which agency you go with, they’ll include mostly the same basic information, though there will be some differences.

Keep in mind that if your business is too recent, there may be no information listed. Similar to 9002 or 9003 credit with personal credit reports, you may simply not have enough credit history to have generated a score yet. 

Here’s an overview of the primary information you should find on your business credit report no matter who you go with:

Company information

Your business credit report will typically list information such as your business name, address, phone number, type of business, and parent companies.

However, in addition to that information, you’ll also find SIC/NAICS codes that specify your industry, key employees, and annual revenue/sale volume numbers.

Payment history

Your payment history will likely be separated into several sections such as commercial payment history (loan payments, leases, insurance) and supplier payments, though it may also be a summary:

BUSINESS_CREDIT_REPORT_3

Just as with your personal credit, your payment history plays a critical part in calculating your business credit score. Which, in turn, affects your ability to be approved with lenders. 

For that reason, this is one of, if not the, most important section to pay attention to. What does your payment history look like? Are there any smudges? Does everything show as on-time or do you have payments that show as past-due or, worse, in collections? Are you being consistent in paying down any balances? 

BUSINESS CREDIT REPORT 4

No matter what your situation, work on getting back to current and stay there with all your vendors, lenders, and other payments.

Public records

Another important part of your business credit report that mirrors a personal credit report is public records.

BUSINESS_CREDIT_REPORT_3-1

This includes items such as:

  • Judgments
  • Liens
  • Bankruptcies
  • Lawsuits

Each of these can negatively affect your business credit, so it’s important to which of these items you can take care of, which it’s having the item removed, paid off, or other. 

As with your payment history, public records and legal issues are used to determine your risk status for financing, so make sure to clean up or get rid of any of these that might show up as soon as possible. 

If you have any kind of lien of bankruptcy on your report, lenders may use that as an automatic rejection or, if nothing else, it may serve as a major check against your perceived creditworthiness. 

3 Tricks to improve your business credit

Once you have checked the report, use our guide to improving your business credit score to plan payment, reporting and error-correction steps. It also explains how PAYDEX works and includes a free follow-up tracker.

Here are 3 tricks you can use to improve your business credit: 

1. Use vendors that report to the business credit bureaus

It’s harder to find ways to improve your business credit than it is with personal credit. With personal credit, anything you finance is likely going to be reported to the major credit bureaus. 

However, with business credit, that’s not necessarily the case. 

The answer? Search out vendors in your industry who are known to report to the business credit bureaus.

Most industries have at least one major vendor who reports. For example:

  • Cintas for restaurants, healthcare, and more
  • Snap-on for automotive and other mechanical industries
  • John Deere for landscaping
  • Uline for shipping supplies
  • Quill for office supplies

By ordering the supplies your business needs regularly from a company that reports to the business credit bureaus, you can start building your credit through purchasing the supplies your business needs to operate on a regular basis. 

2. Open a business credit card 

Personal credit cards improve your personal credit. Business credit cards do the same for your business credit. 

If you’re running a business, it’s best to take advantage of every benefit available to you. Business credit cards often have special perks that personal credit cards don’t have. 

Plus, while many credit card companies that offer business credit cards also report to the personal credit bureaus, some don’t. That means you can safely work on your business credit without risking your personal credit. 

To find out more about the best business credit cards and which report to the personal credit bureaus, read our guide on the best business credit cards. 

EXCEL CAPITAL - WHAT IS A UCC FILING- Types of UCC Liens
Learn more about the different types of UCC liens in our guide.

3. Have old UCC’s removed or terminated

A UCC lien is typically filed on your business when you receive a business loan or other type of financing. Simply, a UCC lien is a claim on certain assets by a lender in the event that you can’t fulfill your debt.

In particular, pay attention concerning any UCC liens on your business credit as these may be there in error. 

If the lien is for a debt you’ve paid off, your lender may not have requested the removal of the UCC filing from your report. In that case, it’s a simple matter of requesting its removal. 

Stay on top of your business credit

Business credit is foreign to most new business owners, and because it functions a bit differently, it can be confusing.

However, the basic idea is the same: your business credit is an important factor that will determine your ability to obtain financing (in this case, for your business). 

As a result, you should do everything you can to not only find out what the condition of your business credit is but take steps to improve it and then continue to monitor it for changes moving forward. 

To succeed in business, you need every edge you can get. Staying on top of your business credit is an easy way to do just that. 

To learn more about improving your credit to get approved for business financing, read What are the 4 C’s of Credit For Getting a Business Loan?

How to Get a Business License: A Guide to All 50 States

EXCELCAPITAL - Business License

Starting a new business is exciting, but it’s easy to forget some of the more technical work that needs to get done.

Things like getting a business license and figuring out your business taxes might not be fun, but they’re essential to the long-term success of your business. 

The only problem is, the path for obtaining a small business license in your state isn’t always clear. Every state is different, from having an online portal to requiring applications be submitted to a specific authority.

However, if you know where to look and what you need to apply, the whole process becomes much easier. Hence, this guide. 

Below, we’ll cover everything you need to know about getting a business license, including:

  • What is a business license?
  • Industries that require business licensing
  • How much does a business license cost? 
  • Applying for a business license 
  • How to get a business license (in all 50 states)

Let’s get started.

What is a business license? 

If you’re new to starting your own business and you’re not exactly sure what the purpose of a business license is, this section is for you.

A business license is a legal document that gives you the authority to operate a business in your chosen state. That’s about all there is to it.

However, when it comes to actually acquiring a business license, it’s not quite so simple.

That’s because, in many states, there is no “business license”. Instead, it might be a “business permit”, “seller’s permit”, or even a collection of 2-3 licenses and permits you need to obtain to operate your business all depending on your state and industry.

We know, that can make the whole process sound a bit confusing. Fortunately, we’ve simplified everything in this guide, so you’ve got nothing to worry about (read on). 

Industries that require business licensing

As mentioned above, what licenses you need to operate your business depend partly on what state you’re operating in, but also what industry. 

For example, a business which offers alcohol will likely need to obtain a liquor license, a restaurant may need that in addition to a food service license, and a construction company will probably need a general contractor license.

Because each state is different, it’s important to contact your local state authority (or use their online resources) to find out what you’ll need for sure (see your corresponding state’s section below). 

Here are some industries that typically require special licensing:

  • Spirits and alcohol
  • Transportation
  • Radio and T.V
  • Firearms
  • Nuclear energy
  • Agriculture
  • Commercial fishing

How much does a business license cost?

Because the type of business licensing required changes based on state, in addition to countless other unseen factors, the price of obtaining a business license varies from state-to-state as well.

There are two factors which come into play (typically) when it comes to paying for a business license: 

  • The initial license cost: $50-100 for a business license in most states
  • And renewal

Renewal fees tend to be the same as the initial license cost, but they can be less in some cases. 

When you’re getting a business license, it’s typically just for 1 year, with renewal required every year thereafter.

However, as with everything else, this is all dependent upon the type of license(s) and the state. So, check with your local authority to know exactly how much your licensing needs will cost. 

How to apply for a business license

As we’ll talk about in a moment, the application process is a bit different for each state. However, the overarching steps involved are roughly the same. 

Here’s a simple breakdown of the steps involved to apply for a business license in most states:

  1. Check your state’s regulations before applying for a business license. Depending on your type of business, other licenses and documents may be required to operate. Learn everything you’ll need to get your business started in advance so you’re well-prepared. 
  2. Submit application with additional documentation. You’ll likely need to submit additional documentation along with your application. Check what those documents are to make sure you have them in order. After that, make sure you’re submitting your application in the right place. 
  3. Wait for approval. For most states, after applying you’ll need to wait for word of your approval. During this time, state business licensing authorities will double-check the application and additional documentation you provided. 

Now, let’s talk about how to get a business license in your state.

How to get a business license in your state: A guide to all 50 states 

Obtaining a business license, no matter the state, typically only requires a few basic steps.

However, because it’s different for each state, the whole process can be incredibly confusing. 

That’s why we’ve done the work for you. We’ve found out exactly how to apply for a business license in each of the 50 states. So, no matter what state you live in, you’ll find the information you need to get your business license below. 

To find out how to get your state’s business license equivalent, click on the map, dropdown, or text summary below: 

Or you can click the dropdown below to select your state:

Here’s a summary of instructions for obtaining business licensing in all 50 states (listed in alphabetical order): 

How to get a business license in Alabama

Use Alabama’s official AtlasAlabama for information on licenses, business tax numbers, and other useful resources for getting your business started. 

How to get a business license in Alaska

Visit Alaska’s Department of Commerce to find out everything you need for obtaining your business license as well as to apply for and renew your license online. 

How to get a business license in Arizona

Arizona’s Department of Revenue website has information on everything from what licenses you’ll need to how much you’ll pay. You can also apply using their online portal. 

How to get a business license in California 

Use California’s official CalGold portal to get specific instructions on how to get a business license in CA. Simply enter your information and the portal will give you relevant instructions. 

How to get a business license in Colorado 

Colorado’s Business Express online portal offers all the information you’ll need to apply for business licenses online as well as having instructions for manual application. 

How to get a business license in Connecticut

Connecticut’s New Business Checklist is a detailed guide that offers steps for applying for a business license in Connecticut. 

How to get a business license in Delaware 

Delaware has a great One Stop Business Registration & Licensing portal with a useful questionnaire that will direct you to the necessary documents and application resources. 

How to get a business license in Washington D.C.

D.C.’s Business Center has a great guide for figuring out exactly what licenses you’ll need to obtain to become fully established. Once you’ve reviewed that, use their Business License guide to apply for a business license online. 

How to get a business license in Florida

You can obtain information on types of business licenses and apply online at Florida’s Department of Business and Professional Regulation and online portal. To get started select your type of business from the drop-down and the site will guide you through instructions for your industry. 

How to get a business license in Georgia 

Most businesses can apply for business licensing online through Georgia’s online portal licensing service. For more information on what licenses you need and whether you can apply online, see Georgia’s official business license page. 

How to get a business license in Hawaii 

Hawaii’s Business Express is one of the better online portals among the states. Simply follow the instructions and you’ll be guided to which types of licensing you need and how to apply.

How to get a business license in Idaho 

Start by getting information on what licenses and permits your business needs at the official Idaho state website. Once you’re done, you can apply online for your necessary licensing and permits at their official online portal. 

How to get a business license in Illinois 

Check Illinois official state site for information on your specific licensing needs. If you’re having trouble finding the licensing information you need (the page is a bit of a pain to scroll through), you can use the search icon at the top right.

How to get a business license in Indiana 

Indiana’s licensing regulations are a bit more complicated than most states, but their official state website has put together a well-organized Business Owner Guide that makes it pretty easy to find the information you need as well as instructions for how to get started (and links where relevant). 

How to get a business license in Iowa

Most businesses need a unique type of license based on the industry in Iowa, which their Business License Information Center helps you identify and find next-steps for. 

How to get a business license in Kansas 

Kansas’ Business Center provides all the information you’ll need to get your licensing squared away. However, if legal structures are a bit confusing, check out this guide for more information. 

How to get a business license in Kentucky 

Kentucky has a great One Stop Business Portal that will help you get information on what exact licenses and permits you need as well as help you apply online.

How to get a business license in Louisiana 

Louisiana’s Business Services resource has all the information you’ll need to figure out what licenses and permits you’ll need. To gain access to their online application services, you’ll need to create a separate account to access their online portal. 

How to get a business license in Maine 

Unlike most states, Maine handles its business licensing at the city level. However, Maine’s local government resource will help you identify the right town/city that your business resides in to help get you pointed in the right direction.

How to get a business license in Maryland 

Maryland’s Department of Commerce has a great one-stop portal that makes it easy to identify which licenses you’ll need and apply online. They even have a great welcome video to get you started that helps break everything down. 

How to get a business license in Massachusetts 

Massachusetts’ licenses and permits page will help you find which licenses you’ll need to operate. Once you’ve reviewed that, use their Starting a New Business guide for additional resources for getting started. 

How to get a business license in Michigan 

Some businesses don’t need licensing in Michigan. To find out if you’ll need licensing to operate, check Michigan’s official licensing search. For additional information, review Michigan’s official Guide to Starting and Operating a Small Business. 

How to get a business license in Minnesota

Minnesota’s online licensing tool will help you find out which licenses and permits you need to operate in Minnesota. You search by topic, agency, or alphabetically.

How to get a business license in Mississippi 

Getting licensed in Mississippi can be a bit confusing as some businesses need both state and local licensing, some only state licensing, and others no licensing at all. To find out what licenses you may need and whether you’ll need to get licensed at the state and/or local level, see Mississippi’s official Small Business Development Center’s FAQ.

How to get a business license in Missouri 

Missouri’s online portal offers information on getting licensed in the state as well as the ability to apply online. 

How to get a business license in Montana

Review Montana’s official state licenses by industry list to find out when licensing you’ll need. You may also need to get licensed at the city level depending on your industry. 

How to get a business license in Nebraska 

Nebraska’s Licensing Division has information on what industries need state-level licensing. If your business doesn’t require state-level licensing, check with your local city governance for information on whether you need to get licensed at the city level. 

How to get a business license in Nevada 

Nevada’s SilverFlume Business Portal has everything you’ll need, including a complete guide to what licensed you may need and how to get licensed 

How to get a business license in New Hampshire 

Review this list at NH’s official Department of Revenue licensing FAQ. If your business doesn’t show up, contact your local city government to find out what licensing you may need beyond that. 

How to get a business license in New Jersey 

New Jersey’s Business Action Center is a complete guide and resource for getting licensed in the state. For more information on where you need to go to obtain specific licenses and permits, see their License and Certification Guide.

How to get a business license in New Mexico 

New Mexico’s licensing portal allows you to apply online. However, keep in mind that licensing may differ between industries and the state vs. local level, so you should also check with local authorities to find out for sure what you’ll need to have in place. 

How to get a business license in New York 

New York’s business wizard has information on what licenses and permits are needed to operate in the state as well as instructions for applying. 

How to get a business license in North Carolina 

NC has an easy-to-use state website and a great business planning checklist to help get you started towards getting licensed and set up in general. 

How to get a business license in North Dakota 

All information regarding licensing, including which licenses are necessary for your business and how to apply, can be found on the North Dakota state website here. 

How to get a business license in Ohio 

Ohio’s Small Business Development Center has everything you need to find out which licenses you need, how to get licensed, and how to register with the Secretary of State (a requirement for Ohio businesses). 

How to get a business license in Oklahoma

Oklahoma has more varied license requirements, which you can find instructions for obtaining on the Department of Commerce’s Business Licensing and Operating Requirements page. 

How to get a business license in Oregon 

If you’re in need of more information than just licensing, Oregon’s starting a business guide will help walk you through several important steps to getting yourself established (#6 explains licensing). 

How to get a business license in Pennsylvania 

The Pennsylvania Licensing System is Penn’s one-stop portal for everything related to licensing. Using the portal, you’ll be able to find out which licenses you need to get started as well as steps to applying for all relevant licenses and permits. 

How to get a business license in Rhode Island 

Rhode Island has two great resources for getting your business started. Their starting a business guide walks you through everything you’ll need to start your business. Second, the Department of Business Regulation has a handy list of license needs and the ability to apply online. 

How to get a business license in South Carolina 

Like many states, SC runs their licensing on the city level. However, you can visit South Carolina’s licensing, permits, and registration page for information on getting licensed and their one-stop portal to get the process started. 

How to get a business license in South Dakota 

South Carolina doesn’t have a central portal for information on licensing, but they have a handy PDF guide on licensing and registration here. Visit South Dakota’s official state website for more information on getting your business started. 

How to get a business license in Tennessee 

Tennessee’s business registration and licensing page has all the information you’ll need to figure out which type of license you’ll need to operate (there are a few unique types of licenses) and how to apply. 

How to get a business license in Texas 

The official Texas state website has information on getting licensed via their home page (under Work). For more information on how to get a license and what licenses and permits you might need, see their guides and resources page. 

How to get a business license in Utah 

Utah’s official Business Licensing and Registration guide has specific instructions for getting licensed in the state. For more information on getting your business started in Utah, check out their Government Requirements page. 

How to get a business license in Vermont 

Start by looking at Vermont’s professional regulation page for information on what licenses you’ll need to get set up in the state. Vermont doesn’t have an official licensing portal, they instead direct you to the SBA’s Apply for licenses and permits page. 

How to get a business license in Virginia 

For steps on launching a business in Virginia, read their business one stop guide which gives information on starting a business in Virginia. Step number 4 will get you started with specific instructions for getting licensed. 

How to get a business license in Washington 

Washington state’s online business licensing portal offers a simple but straightforward guide to everything you’ll need to get licensed, including when you’ll need a license and how to apply. 

How to get a business license in West Virginia 

West Virginia’s online business portal can help you figure out the specific licenses you’ll need as well as direct you to where you need to apply to get started obtaining those licenses. 

How to get a business license in Wisconsin 

Review Wisconsin’s online business portal to find out what licenses and permits you might need. In addition, you can use their portal apply online and find additional resources.

How to get a business license in Wyoming

Wyoming business permitting and licensing has the perfect online guide that will get you started on the process to getting a business license in Wyoming. For additional questions which the page does not answer, contact the Wyoming Business Outreach Coordinator.

Obtaining your business license– simplified

Obtaining a business license can seem complicated. And, if you don’t know where to look for information on your state’s business license application process, it definitely can be. 

However, with specific information for getting a business license based on your state, the process becomes much simpler.

Just getting your business started? Check out these guides:

Ready to Fund Your Business?

Explore small business loan options, including business lines of credit and term loans. Complete a simple application to see which funding options may fit your business.

Check Your Funding Options