

FINANCING FOR NEW AND USED BUSINESS EQUIPMENT
Put the right equipment
to work for your business
Finance up to 90% of your equipment purchase price, with down payments as little as 10%. Keep cash available for payroll, inventory, and the everyday costs of running your business.
An equipment loan spreads the cost of a new or used machine over time. Excel Capital helps you explore options through lending partners, whether you are replacing an essential machine, adding capacity, or upgrading the tools your team uses every day.
See my equipment financing optionsWhat Is Equipment Financing?
Equipment financing helps a business buy or use new or used equipment while spreading the cost over time. An equipment loan is one option: your business buys the asset, and the equipment typically secures repayment. Equipment finance agreements and leases offer other structures, with different ownership and payment terms.
Business equipment financing can support a replacement machine, a commercial vehicle, or an upgrade that adds capacity. The right choice depends on what you need, how long you expect to use it, and the payment your cash flow can support.
Start with the cash purchase price, then compare the down payment, scheduled payments, fees, and any final purchase obligation. The calculator below helps you see those costs together before reviewing a written offer.
Equipment Financing Calculator
Use this equipment finance calculator to compare a loan with common lease structures. Change the purchase price, down payment, annual rate, or term to see how the payment and total cost change.
The starting example uses a 10% down payment. Change the assumptions to compare offers. Calculator input ranges are not financing limits or qualification requirements.
Estimated monthly loan payment
- Amount financed
- Modeled cash due at signing
- Total interest
- Total scheduled loan payments
- End purchase option
- Outlay without purchase, before return charges
- Financing cost before other charges
- Total paid, including down payment
Estimates are not offers or approval. The 14% starting annual interest rate is not a fee-inclusive APR or a promise of the rate available to a 550-FICO applicant. The example uses a $100,000 purchase, $10,000 down payment, and 60-month term. Loan mode uses fixed interest and monthly payments in arrears. Lease modes use an assumed financing rate and discounted end value; actual lease pricing may differ. Taxes, insurance, deposits, maintenance, return charges, and other costs outside the modeled payments are excluded. Totals use unrounded payments; the final payment can vary by cents. Seasonal schedules, TRAC adjustments, and interest-only periods are not modeled.
Explore early payoff and the payment schedule
This standard-loan illustration assumes interest stops when principal is repaid. A fixed-charge equipment finance agreement or lease may require different payoff amounts. Ask for a written payoff quote.
- Remaining principal owed
- Future interest avoided
- Net savings after payoff charge
- Total outlay with early payoff
View payment-by-payment breakdown
| Payment | Opening balance | Payment amount | Interest | Principal | Closing balance |
|---|
Compare payment examples and repayment terms in our equipment loan calculator guide.
Equipment Loans vs. Equipment Finance Agreements
Equipment financing is the broader term; a business equipment loan is one structure within it. An equipment finance agreement, or EFA, can also finance a purchase while your business holds title and the provider has a security interest. Read its payment and early payoff provisions carefully: a fixed finance charge may work differently from interest on a conventional loan.
Get Equipment Financing with Excel Capital
Equipment financing doesn't have to be complicated.
Finding a lender you can trust, with clear applications, terms, and costs, makes the decision easier.
If you need to replace a critical piece of equipment fast, let us help.
Tell us what equipment you need, whether it is new or used, and when you need it in service. Have an itemized seller quote ready, including delivery and installation costs.
Explore financing for new or used equipment. Apply for equipment financing with Excel Capital:
Types of Equipment Financing Options
Several forms of business funding can be used to purchase equipment. The right fit depends on what you are buying, how long you plan to use it, and whether you want to own it. Here is a quick comparison of common options; availability varies by provider.
Traditional Equipment Loans
You borrow money for a specific equipment purchase and repay it over an agreed term. With a typical secured loan, your business holds title while the lender has a security interest until repayment. Fixed-rate loans can provide predictable monthly payments. The amount financed and any down payment depend on the asset and your qualifications.
Equipment Finance Agreements (EFAs)
An EFA is a secured loan for an equipment purchase. Your business owns the equipment, and the lender takes a security interest. Unlike a lease purchase option, you generally do not need to buy the asset again at the end. Check the payment schedule for any final balance or balloon payment.
Equipment Leases
A lease lets your business use equipment for a set period. Depending on the contract, you may be able to return, renew, or buy it at the end. Compare the full cost, including any purchase option and return charges. A lower payment does not always mean a lower overall cost. See the loan-versus-lease comparison below.
Equipment Lines of Credit and Master Commitments
A line of credit can help with equipment purchases made at different times. A revolving line lets you draw, repay, and borrow again within its limits, but some equipment facilities convert individual purchases into term loans. Confirm how draws work, what purchases qualify, and when each balance must be repaid.
For several purchases over time, ask about a master equipment commitment or capital expenditure (CapEx) line. An approved facility can support successive equipment purchases within its limits and conditions. Confirm the availability period, requirements for each purchase, and whether repayments restore borrowing capacity. Master commitment lines are one example of this structure.
SBA Equipment Loans: 7(a) and 504
SBA 7(a) loans can finance equipment purchases and installation alongside other eligible business needs, including working capital. The 504 program supports eligible fixed-asset projects, including equipment with at least 10 years of remaining useful life. 504 loans cannot fund ordinary working capital or inventory. These programs have specific eligibility, documentation, and project requirements. Confirm the application timeline before committing to a purchase.
Business Term Loans
Term loans offer a lump sum of cash in exchange for repayment with interest over a specified period of time or “term”. A business term loan may suit an equipment purchase that is part of a larger project. Check permitted uses, collateral, and guarantee requirements.
Can You Get Cash From Equipment You Already Own?
Yes, eligible equipment can support financing even when you are not buying another machine. You do not necessarily have to sell it to access its equity. The main choices differ in who owns the equipment, how existing debt is handled, and what you owe afterward.
Equipment Equity Loans and Cash-Out Equipment Loans
You keep ownership and borrow against the equipment, giving the lender a lien. The amount available depends on the lender's valuation, existing liens, and your qualifications. Equity does not mean you can borrow the asset's full value. Ask for the net cash you would receive after any debt payoff and fees.
Equipment Sale-Leaseback
With a sale-leaseback, you sell equipment your business already owns to a financing provider and lease it back for continued use. This can release cash tied up in the asset, but it also transfers ownership and creates a lease payment obligation. Review the valuation, total lease cost, and end-of-term options. Regaining ownership depends on the purchase provisions in the lease.
Equipment Refinancing
A new loan pays off an existing equipment obligation. It may change the payment or repayment period, and some approvals include additional cash. Refinancing does not automatically mean cash out. Compare the current payoff, new fees, total remaining payments, and any final balloon. A smaller monthly payment can still cost more over a longer term.
Asset-Based Lending With an Equipment Term Loan
Equipment may secure a term loan within a larger asset-based lending arrangement. For example, a business might have a revolving line supported by receivables and inventory alongside a separate equipment loan. The equipment portion can require scheduled principal payments even when the working-capital line allows reborrowing.
If keeping ownership matters, compare a cash-out secured loan with a sale-leaseback. Look at net cash received, total payments, liens, and the cost of owning or returning the equipment at the end. These are structures available in the wider market; confirm which programs are available for your business and asset.
Further reading: equipment cash-out loans, the OCC guide to EFAs and sale-leasebacks, and equipment term loans within asset-based lending.
Equipment Lease and Usage Options
The end-of-term clause matters as much as the monthly payment. Here are the main structures you may encounter when comparing equipment financing offers.
- $1 buyout lease: Payments are structured toward ownership, with a nominal final purchase price. Confirm the ownership terms and any additional charges.
- Fair market value (FMV) lease: Typically offers return, renewal, or purchase at the equipment's then-current value. The eventual purchase price is not fixed at the start.
- Fixed purchase-option lease: Sets an optional purchase price, such as 10% of original cost. Check that purchase is optional and understand the return conditions.
- Purchase Upon Termination (PUT): Requires a predetermined final purchase payment. Include that obligation in your budget.
- TRAC and modified or split-TRAC leases: Commonly used for commercial vehicles. A stated residual and end-of-term adjustment affect the final cost. Ask who covers a resale shortfall and how any proceeds are allocated.
- First Amendment or purchase-or-renew arrangements: At a specified decision point, you may need to buy or extend the lease. Do not assume you can return the equipment at that point.
- Rental with a purchase option: Starts as a rental with a contractual path to ownership. Ask how much, if any, of the rental payments counts toward the purchase price.
- Pay-per-use or equipment-as-a-service: Charges can follow usage or output, with service sometimes bundled in. Check the usage measure, minimum commitments, maintenance responsibilities, and termination terms.
Use the equipment loan and lease calculator above for standard loans, $1 buyouts, fixed options, FMV assumptions, and mandatory purchases. Specialized resale adjustments and usage-based charges require a provider's quote.
Structure references: lease purchase options and PUT, TRAC and equipment refinancing, purchase-or-renew leases, rental purchase options, and pay-per-use financing.
Equipment Loan and Lease Payment Options
A payment schedule can sometimes be adjusted to match your business's cash flow. These are variations within a loan or lease, rather than separate ways of owning equipment. Availability depends on the provider and approval.
- Seasonal payments: Smaller payments during slower months and larger payments during busier periods.
- Skip payments: Specified months with no scheduled payment, as agreed in the contract.
- Step-up payments: Smaller payments initially, followed by scheduled increases.
- Deferred-start payments: The first payment begins after an agreed delay.
PNC lists these customized payment structures. A payment delay does not by itself mean financing costs stop accruing. Ask whether interest or other charges continue, whether they are added to the balance, and how the arrangement changes later payments and total cost. Get the full schedule in writing before comparing offers.
Specialized Equipment Financing Arrangements
Synthetic leases involve specialized tax, accounting, and residual-value considerations. Fulton lists synthetic leases among its equipment finance structures. Have your accountant and legal adviser review the actual agreement; the product name alone does not establish its balance-sheet or tax treatment.
Dealer floorplan financing supports equipment held for resale. It serves equipment dealers rather than a business buying a machine for its own operations. Review when sales trigger repayment and any scheduled principal reductions while inventory remains unsold. DLL's Hyundai inventory finance program illustrates this dealer-focused category.
How Does Equipment Financing Work?
A secured loan gives the lender a claim on an asset to help protect against nonpayment. This asset is known as collateral.
With a secured business loan, collateral may include property, cash, or a vehicle, depending on the agreement.
If you cannot repay the loan, the lender may have the right to repossess the collateral, subject to the agreement and applicable law.
With an equipment loan, the equipment being purchased typically provides that security.
The lender may record a UCC filing to give public notice of its security interest in the financed equipment.
The equipment may provide enough collateral for a particular transaction. However, a personal guarantee or additional security may also be required. Read those provisions before signing.
The amount you can borrow depends on underwriting as well as the purchase. Some programs can include eligible delivery, installation, or other costs; others require you to pay those separately.
How to Apply for an Equipment Loan
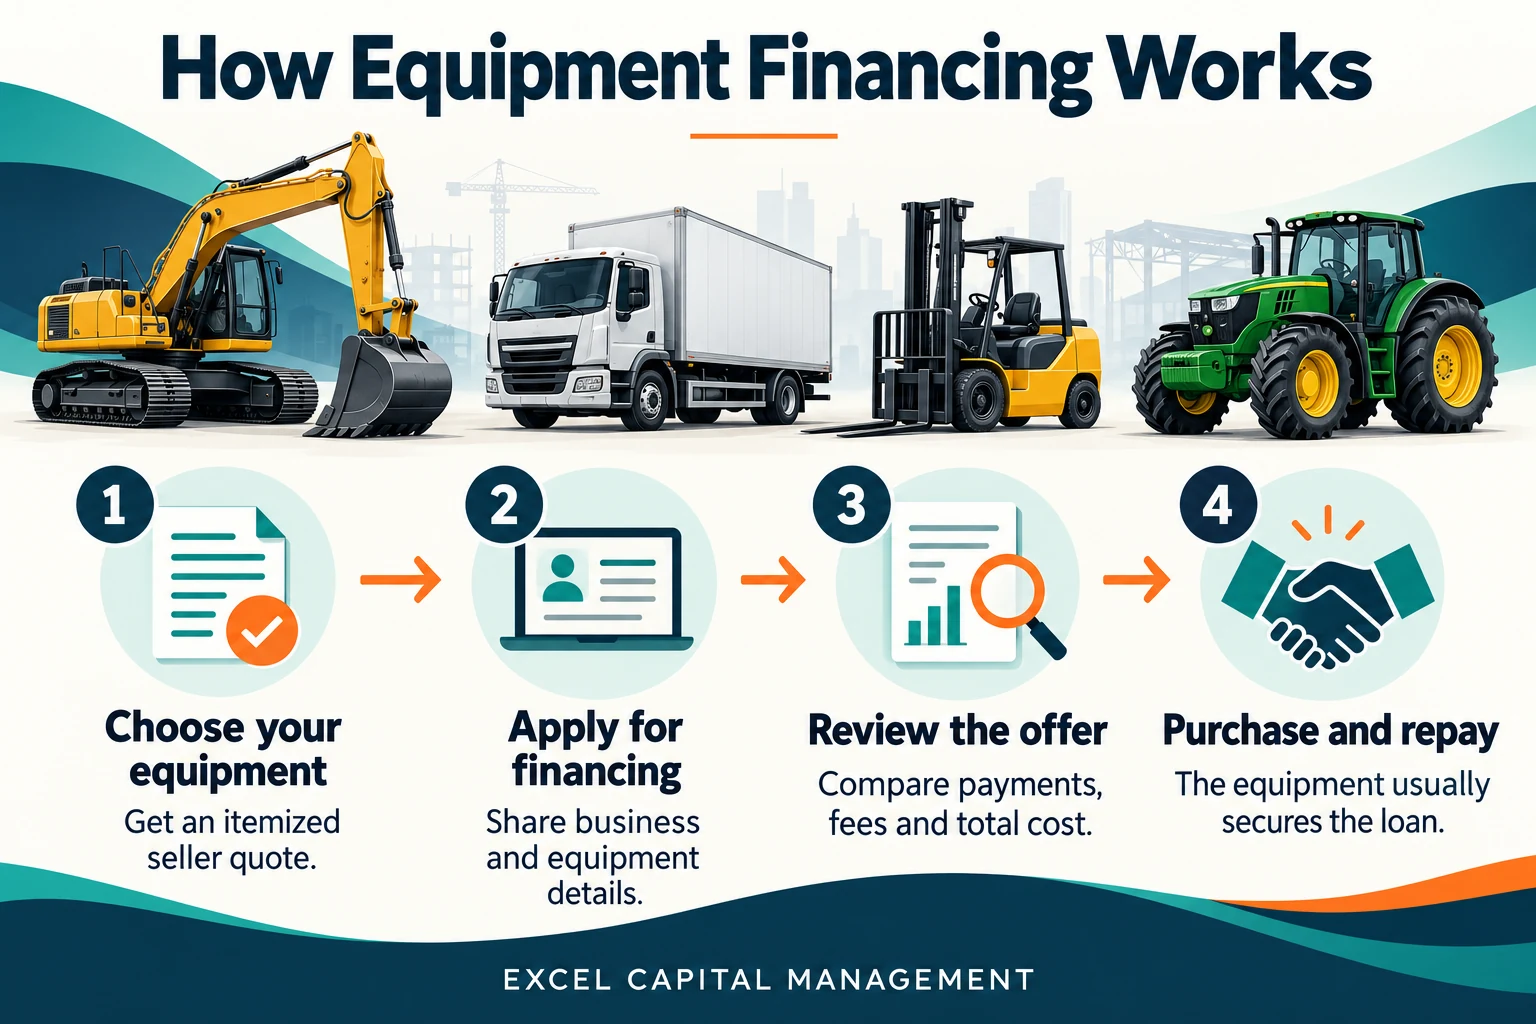
- Choose the equipment. Get a quote with the model, condition, price, seller details, and expected delivery date.
- Work out the full purchase cost. Add taxes, freight, installation, and any immediate work needed to put it into service. Ask which costs can be financed.
- Provide business and equipment information. The financing provider reviews your application, financial information, and the asset.
- Compare the written offer. Review payment frequency, term, total cost, security, and early payoff provisions.
- Complete the purchase. Confirm how the seller will be paid, what acceptance documents are required, and when your first payment is due.
An initial decision is different from completed funding. Missing seller documents, title issues, inspections, or delivery conditions can affect the schedule.
Used Equipment Financing
Yes, used equipment can be financed. A used machine may let you add the capacity you need at a lower purchase price than a comparable new model. The financing decision still depends on the equipment, the seller, and your business.
A lower asking price is only part of the calculation. A machine that needs repairs before its first job can use up the cash you expected to save. Look at the purchase price, financing cost, expected maintenance, and likely downtime together.
What lenders review on used equipment
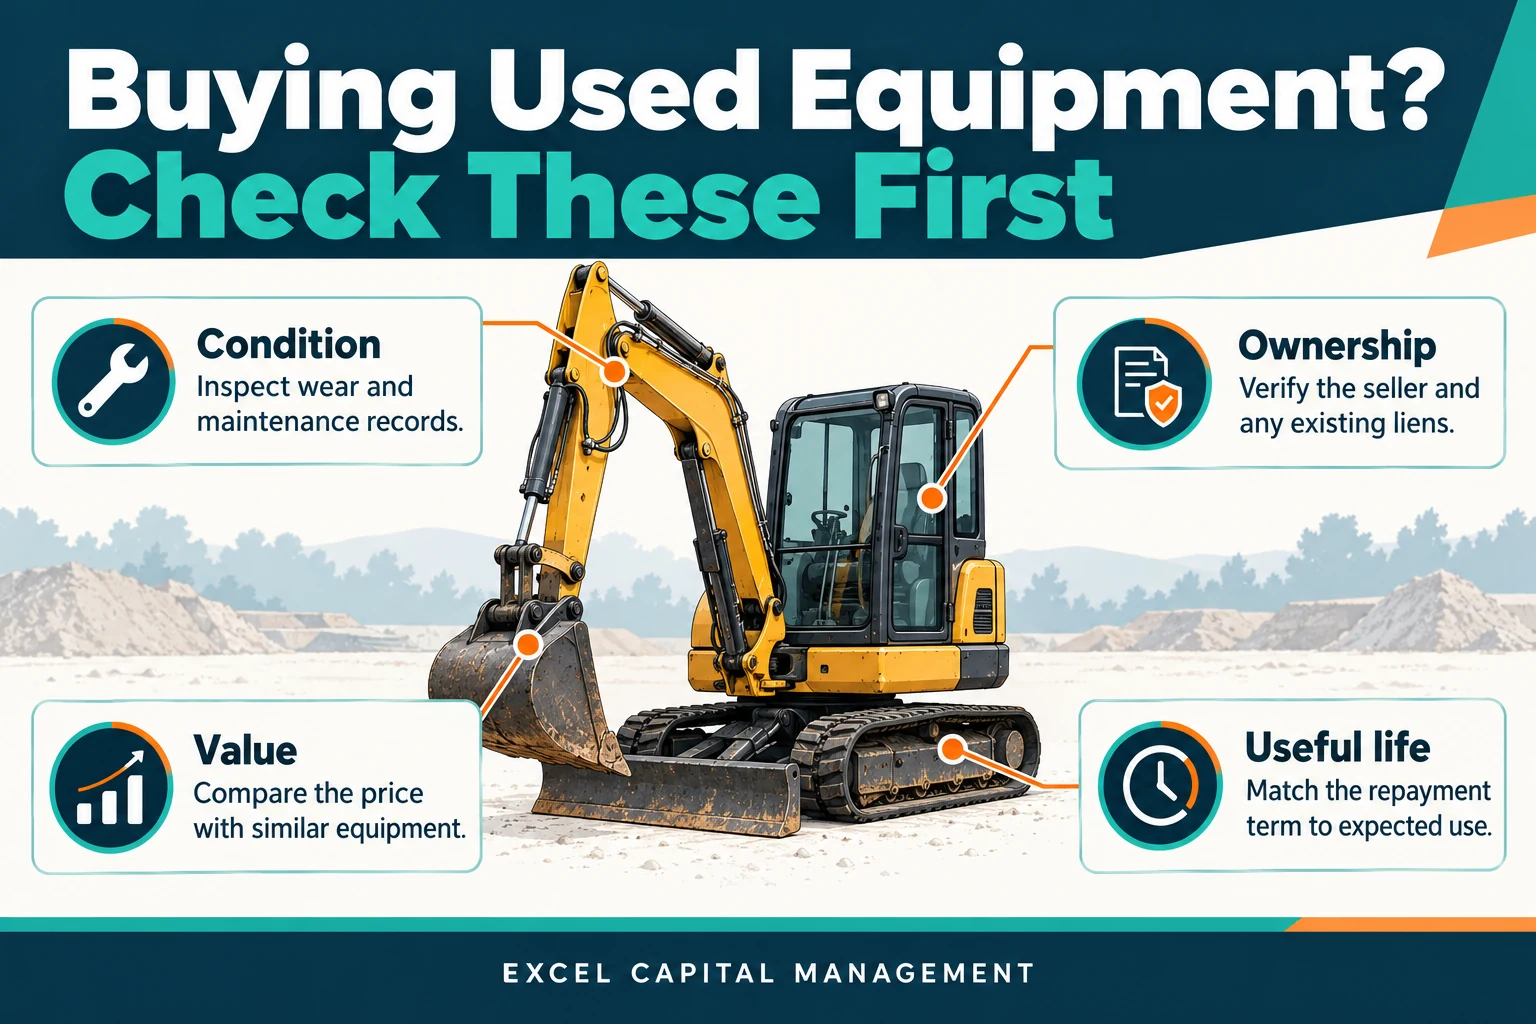
Lenders may consider the equipment's age, condition, resale value, and remaining useful life alongside your cash flow and credit history. Operating hours or mileage can matter as much as the model year.
Ask the seller for the information that helps establish what you are buying:
- Make, model, year, and serial number or VIN, where applicable.
- Itemized invoice or purchase agreement and seller contact details.
- Photos, operating hours or mileage, and available service records.
- Details of previous repairs, current defects, and any remaining warranty.
- Title or ownership documents where applicable, plus information about existing liens.
- An inspection or valuation if the financing provider requires one.
Requirements vary. You do not need to assume that every transaction requires an appraisal, but find out before promising the seller a closing date.
Buying from a dealer, private seller, or auction
Tell the financing provider where you intend to buy. Some programs accept private-party purchases or auctions; others have seller restrictions. Get that answer before paying a nonrefundable deposit or bidding.
For a private sale, ownership and any existing financing need particular attention. Ask how an outstanding lien will be paid and released. At an auction, check the payment deadline and whether financing can be completed within it.
Match the loan term to the machine
A smaller payment is not always the better deal. Consider how long the machine can reasonably keep doing the job, whether replacement parts are available, and the cost of a major repair while payments remain due.
For example, a used commercial oven may cost less than a new one, but the savings narrow if you must replace a major component and lose several days of service. Compare that possibility with the warranty, delivery time, and payment on a new model. This is a purchase comparison, not a reason to rule out used equipment.
Used equipment financing rates and down payments
There is no single rate or down payment that applies to every used machine. The business's financial position, the amount financed, and the asset all affect the offer. Age alone does not tell you what the financing will cost.
Ask for the amount due at signing, the full payment schedule, fees, and total payments. Keep money available for insurance, maintenance, and costs that the financing does not cover.
Equipment Financing vs. Equipment Leasing: What’s the Difference?
Equipment leasing is another option to consider when your business needs equipment.
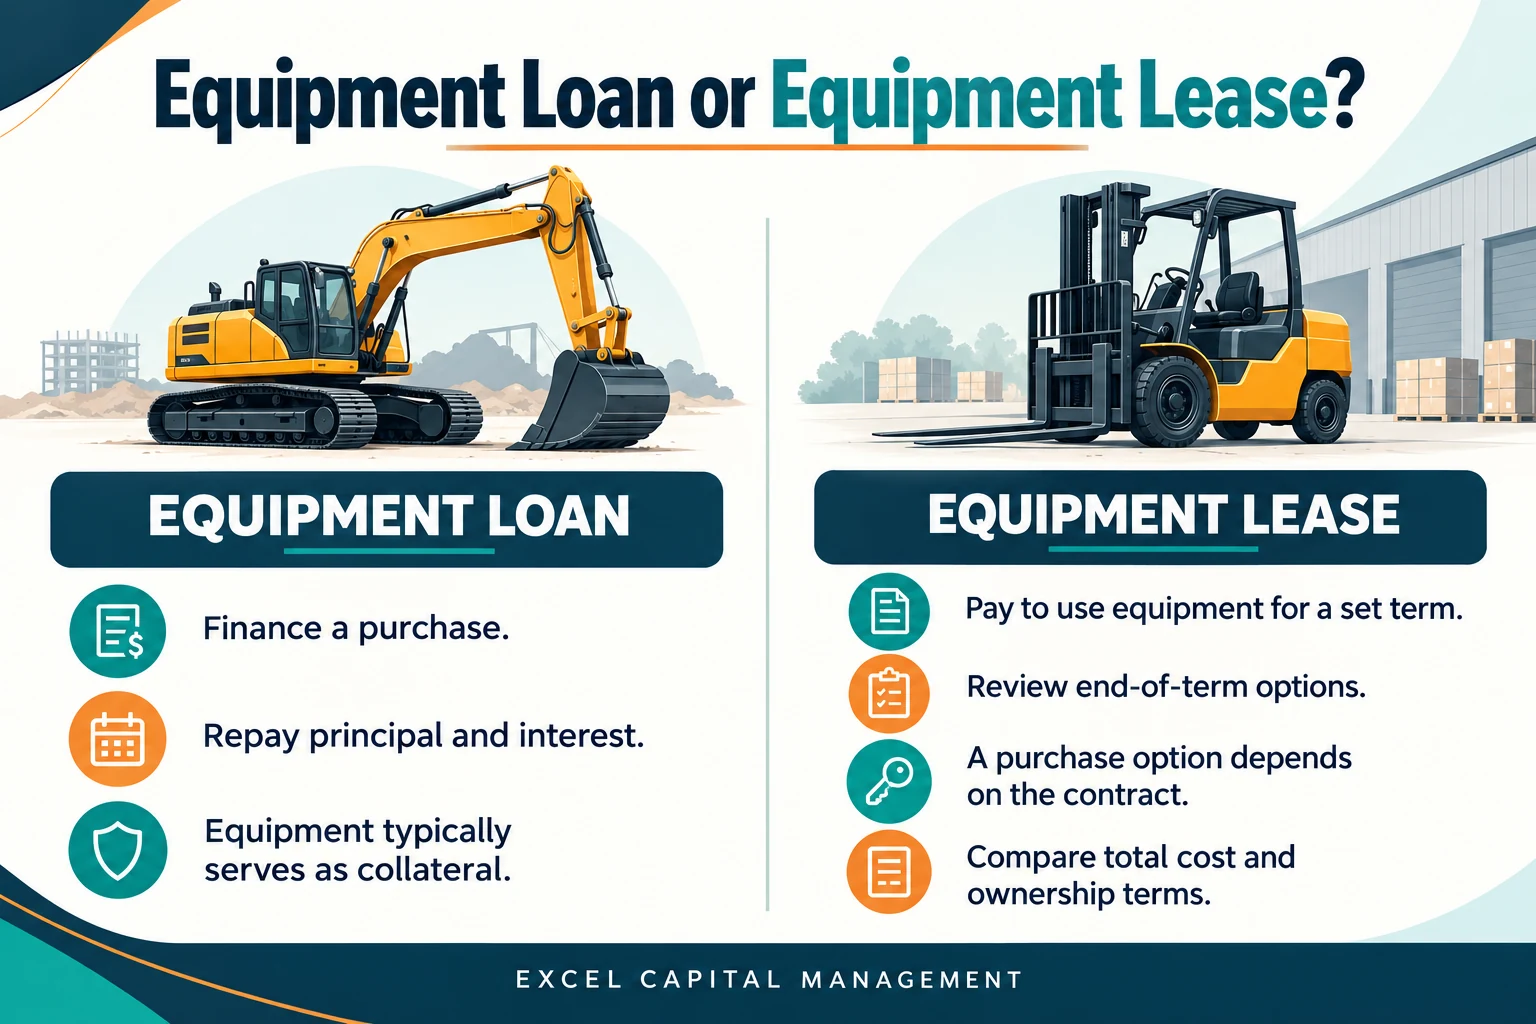
The difference involves ownership, the payment obligation, and what happens when the agreement ends, as well as how long you need the equipment.
With a typical equipment loan, your business owns the equipment subject to the lender's security interest. With a lease, the lessor generally owns it during the agreement, and the contract sets out your rights to use or purchase it.
If it is a critical piece of equipment you need every day, compare the full cost over the period you expect to use it. A lower monthly lease payment may come with an additional purchase price, return requirements, or other end-of-term costs.
Equipment Financing: Pros and Cons
Financing can put equipment to work sooner and keep more cash available for daily expenses. The trade-off is a repayment commitment, often with interest, fees, and a lien on the asset. Compare those costs with paying cash, repairing the equipment you have, or renting for a shorter job.
Pros
- Put equipment to work sooner: Financing can make a purchase possible before you have saved the full price. Funding speed depends on the program and transaction.
- Payment planning: An agreed repayment schedule helps you plan alongside payroll, rent, and other expenses. Confirm whether payments are fixed.
- Equipment as collateral: The equipment you purchase typically secures the loan, although a guarantee or additional security may be required.
- Preserve operating cash: Spreading the purchase cost can leave money available for other business expenses.
- Potential tax benefits: Qualifying equipment may be eligible for depreciation or Section 179 expensing, subject to tax rules and limits. Financing alone does not make a purchase immediately deductible.
Cons
- Borrowing costs: Interest and fees increase the total purchase cost.
- Downtime: Payments usually continue even when a machine is being repaired.
- Default and early exit: Review repossession rights, guarantees, and the cost of paying off or ending the agreement early.
- The equipment could be obsolete by the time you pay it off: Chances are, if you’re investing in equipment now, you can gauge its value to your business in the long-term. However, things may change, so it’s important to know that piece of equipment has a value equivalent to how long it takes for you to pay off its cost.
How to qualify for equipment financing
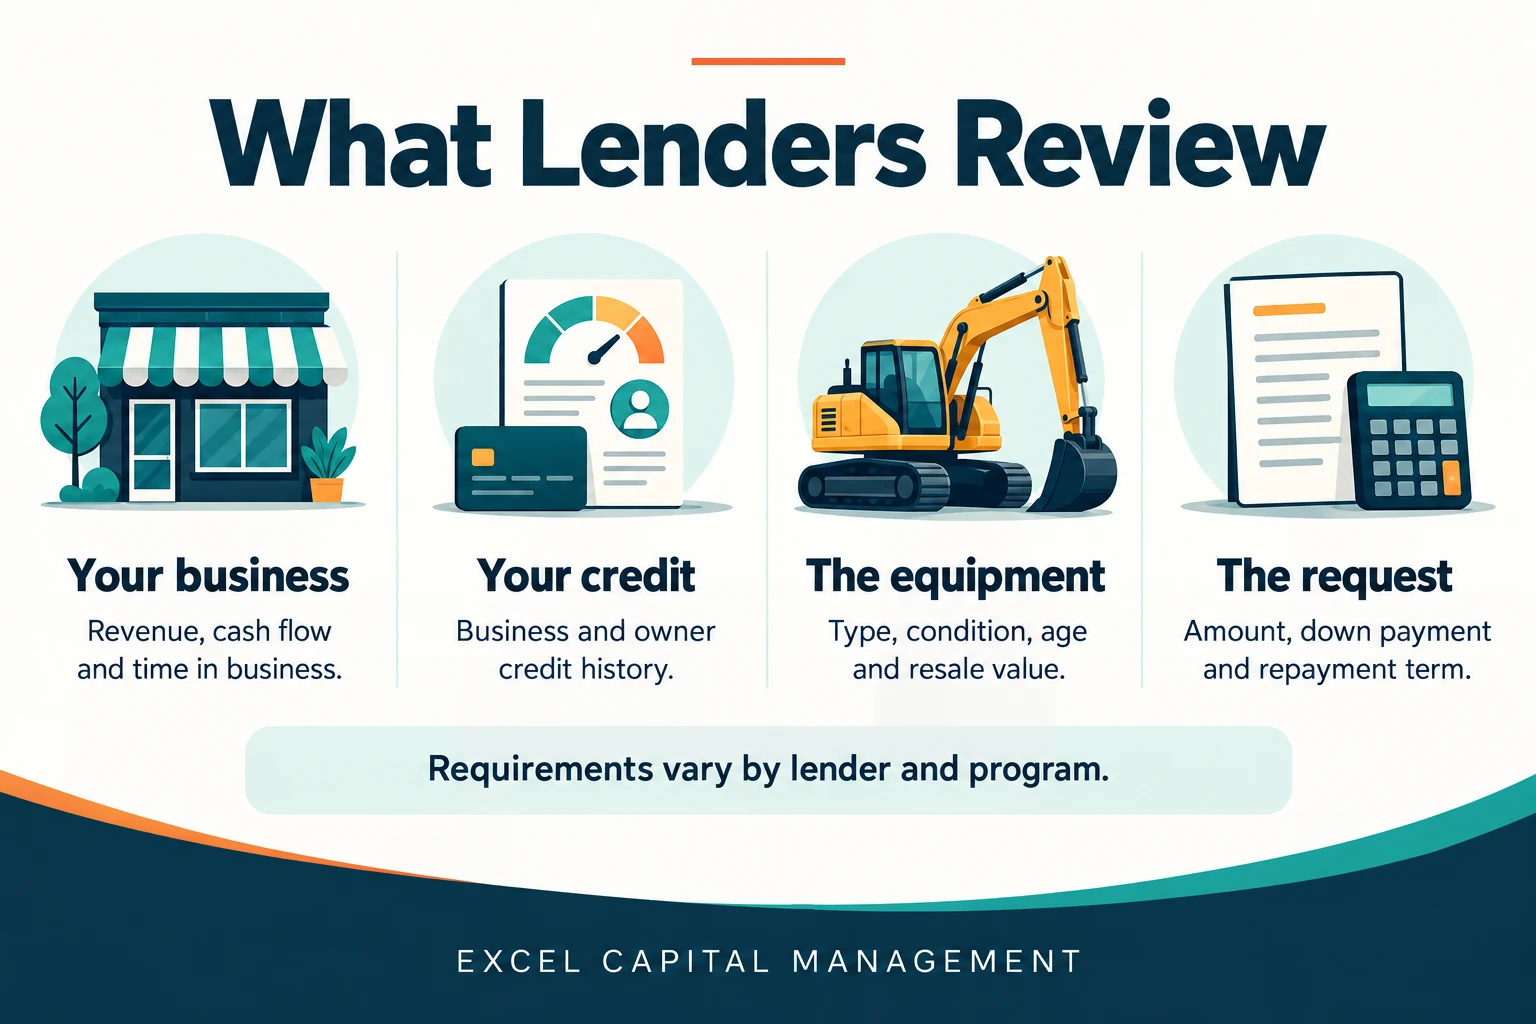
Start with the equipment quote and a payment your business can support. Excel's starting credit consideration is 550 FICO, but lenders also review the business and the asset. Your credit score alone does not establish eligibility, the available amount, or the interest rate.
So, what does it take to qualify for equipment financing?
There is no single credit score or revenue minimum that applies to every equipment financing program. Ask which requirements apply to the offer you are considering.
Equipment financing qualification factors include:
- Personal and business credit history, where relevant to the program
- Revenue, cash flow, and existing debt payments
- Time in business, equipment value, and the proposed financing structure
What documents are needed for approval?
In addition to the above qualification factors, you’ll need a few important documents for approval. Use our business loan application checklist to organize the records your provider requests.
These are used by the lender to obtain an accurate assessment of the health of your business as a whole.
The documents requested may include:
- Business bank and credit card statements (number of months may vary)
- Profit and loss statement and balance sheets
- Completed application
- Equipment quote or invoice and seller details
- For used equipment, condition records and ownership or title documents where applicable
- Other paperwork may be requested after submitting an application
Alternative lenders, who offer equipment financing, generally want to obtain a complete view of the financial health of your company.
With equipment financing, it is about more than just your credit score. Though credit does carry weight as well, so keep that in mind.
Once you have applied for financing, the rate and terms offered can depend upon:
- The value of the equipment
- Your credit and business history, and
- The amount financed, down payment, and repayment term
Equipment Financing for Startups
A new business has less operating history for a financing provider to review. Ask whether a program accepts startups before completing a full application. Be prepared to explain the owner's relevant experience, the equipment's intended use, and how payments will be covered before revenue becomes steady.
Depending on the program, you may need projections, a business plan, a down payment, or a personal guarantee. Equipment collateral does not guarantee approval. Compare the amount due upfront and the total repayment, not just the monthly payment.
Equipment Financing for Bad Credit
A lower credit score does not automatically rule out an equipment purchase. Some equipment financing companies consider bad-credit applications and review the business, the asset, and the proposed down payment together. The important distinction is that accepting an application is not the same as approving it.
For example, Smarter Finance USA describes equipment financing for applicants with challenged credit, including situations where cash flow, equipment quality, or a larger down payment may help. This is an example of another provider's published approach, not an Excel approval policy or a claim of a lending partnership.
Can you apply with a 550 FICO score?
Excel Capital can help explore equipment financing options with starting application consideration at 550 FICO. Available programs still depend on the lender's full review. The 14% starting annual interest rate is not a promised rate for a 550-score applicant. Review the full repayment schedule before accepting an offer.
What can matter beyond your credit score?
Be ready to document business deposits, existing debt payments, and how the equipment will be used. A seller's itemized quote, maintenance records for used equipment, and a realistic purchase budget can help a provider assess the request. Explain past credit problems accurately and provide supporting documents when requested.
A larger down payment may reduce the amount that needs financing, but it also uses cash your business may need for payroll, repairs, or installation. Compare the payment with the income the equipment can realistically support, including slower months. Do not commit to a machine solely because an application has been submitted.
Compare bad-credit equipment financing offers carefully
Request the annual interest rate or APR as applicable, all scheduled payments, and any required final purchase. Ask what you would owe if you paid early. A fixed-charge equipment finance agreement or lease may not reduce future charges the way a conventional amortizing loan does.
Lower credit scores can narrow your options or increase costs. Cash flow and the equipment still matter, but no single factor guarantees approval. Ask whether a preliminary review uses a soft or hard inquiry, and what further checks are required before funding. Our guide to hard inquiries explains the distinction.
What Types of Equipment Can Be Financed?

Business equipment loans can support purchases such as commercial kitchen appliances, manufacturing machinery, medical and dental equipment, computers, and farm or landscaping equipment. Eligible assets and sellers vary by program.
Construction and Heavy Equipment Financing
For excavators, skid steers, loaders, and other construction equipment, bring an itemized quote showing the machine and any attachments. For used machinery, operating hours, condition, service records, and remaining useful life help explain the purchase.
Include transport, setup, insurance, and maintenance in your budget. Consider whether the payment still fits between projects or during a slow season. Confirm private-seller or auction eligibility before paying a deposit, and compare buying with renting if you only need the machine for a short project.
Industrial Equipment Financing
For production machinery, CNC machines, packaging lines, and similar assets, start with the capacity you need and the full cost of putting the equipment to work. Industrial equipment financing should fit the machine's expected useful life and your operating budget. Include freight, installation, testing, and operator training in the quote, then confirm which items the provider will finance.
Commercial Outdoor Power Equipment Financing
Power equipment financing can help businesses plan purchases of commercial mowers, landscaping machinery, and snow-removal equipment. Keep business-use purchases separate from consumer lawn-and-garden offers. Consider the payment during your slower season, and ask how attachments, trailers, and a used machine's condition affect the request.
Medical and Dental Equipment Financing
Medical equipment financing may support diagnostic, imaging, examination, and laboratory purchases. Dental equipment financing focuses on assets such as chairs, scanners, imaging systems, and sterilization equipment. Itemize installation and related costs, and distinguish a single equipment upgrade from financing an entire practice acquisition. Each purchase needs its own eligibility and cost review.
Farm Equipment Financing
Tractors, combines and planters often need payment schedules that fit the farm's income. Check the seller, condition and payment deadline before committing. Our farm equipment financing guide compares agricultural lenders, USDA programs and seasonal payment options. The calculator on this page estimates monthly payments. Ask the lender for an annual or seasonal schedule.
Restaurant and Fitness Equipment
A commercial oven, refrigeration system, or gym equipment package needs a budget that includes delivery and setup. Compare warranties, maintenance, and likely downtime alongside financing costs. Our guides to restaurant equipment financing and gym equipment financing cover these purchases in more detail.
Vehicle, Truck, and Semi-Trailer Financing
Financing a vehicle for business, such as a truck or semi-trailer, can involve different documentation from financing stationary equipment.
Many financing providers finance commercial vehicles and wheeled equipment. Eligibility and down payments vary by program; there is no universal 20% down-payment rule.
For a vehicle purchase, discuss:
- Age, mileage, condition, and intended commercial use
- Title, ownership, and any existing liens
- Insurance requirements and any restrictions on eligible vehicles or sellers
Confirm whether the purchase belongs in an equipment financing program or a dedicated commercial vehicle program.
Keep that in mind if you’re considering financing a new vehicle for business purposes.
How Much Does Equipment Financing Cost?
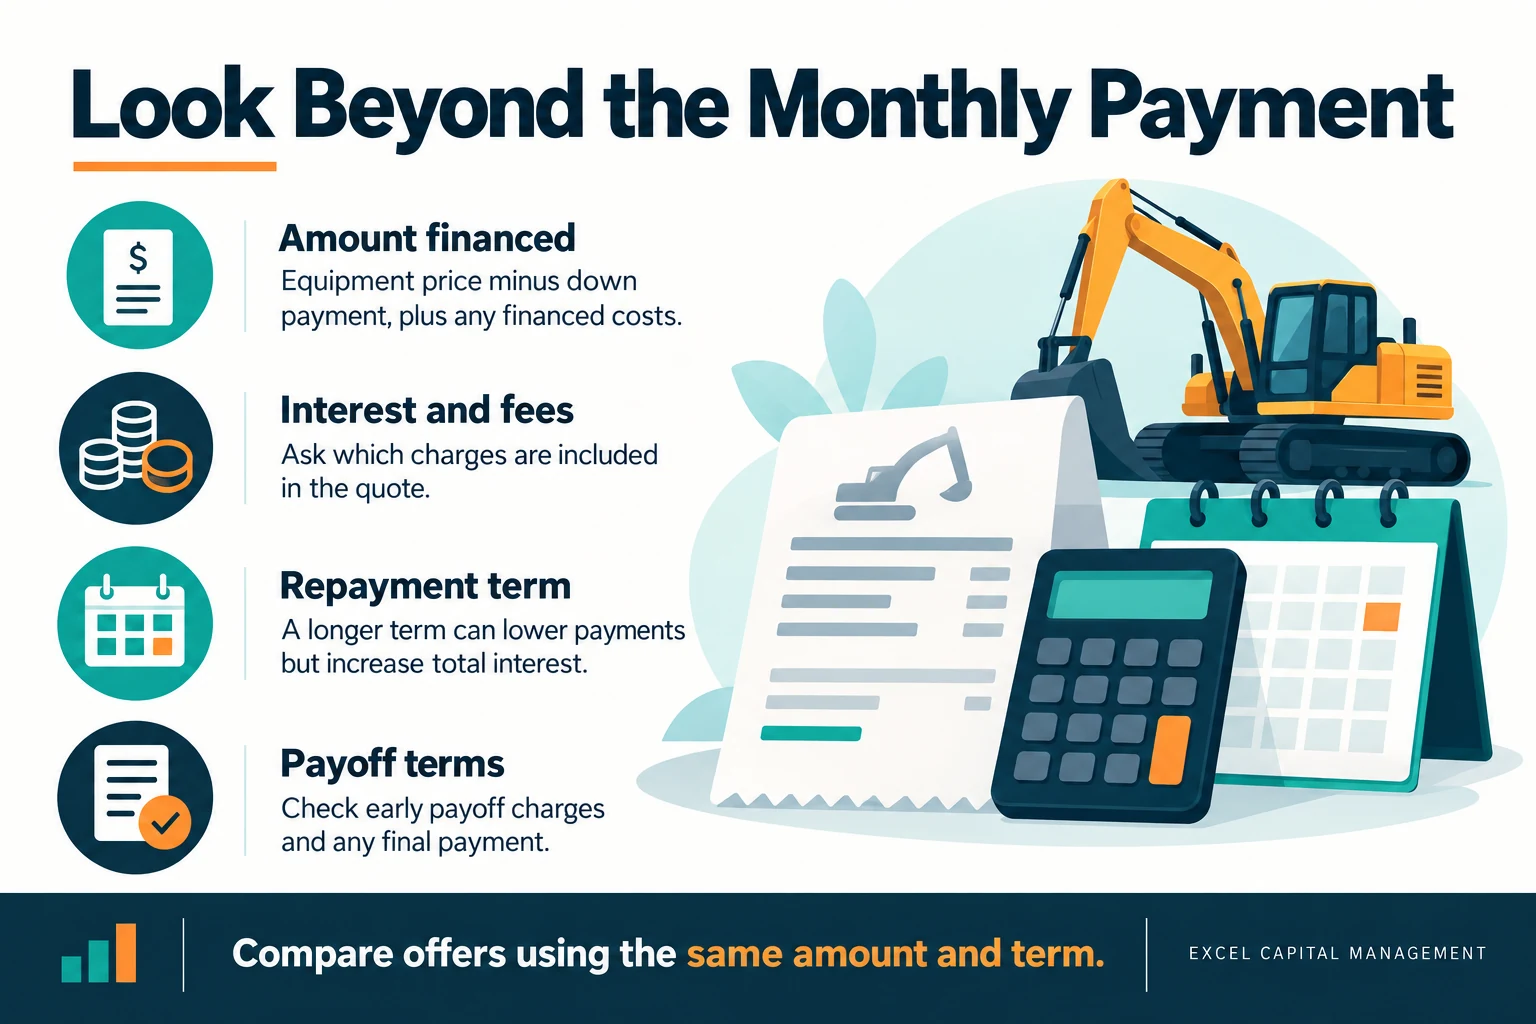
Excel's starting annual interest rate is 14%, before fees, for qualifying transactions. Your rate can be higher, especially when credit, cash flow, or the equipment makes the request harder to finance. This starting rate is not a national average or a fee-inclusive APR.
Commercial equipment financing costs also depend on the repayment term, payment timing, and any final purchase obligation. Include applicable taxes and other purchase costs in your budget. An equipment financing loan with a lower monthly payment can still have a higher total cost if you repay it over more months.
Five Things to Request When Comparing Equipment Financing Offers
Ask each provider for the same information so you can compare the full obligation, not just the starting payment.
- Net cash received or purchase amount funded: Show fees and any existing loan payoffs separately.
- Every scheduled payment: Include payment dates, increases, skipped months, and any deferred period.
- The final obligation: Identify any balloon, required purchase, optional purchase, or return conditions and charges.
- Written early-payoff amounts: Request examples after months 12 and 24, where applicable, including fees and any finance charges that remain payable.
- Collateral and guarantees: Identify the equipment pledged, any claim on other business assets, and any personal guarantee.
However, the general idea is the same:
- You pay off a conventional equipment loan in regular installments over the agreed term
- Interest and fees depend on the financing structure, the equipment, and your business's financial health
- A longer term can reduce the payment while increasing total interest, if other terms stay the same
It is important to understand that interest and fees can make the total paid for financed equipment higher than its cash purchase price.
That’s the trade-off for obtaining the cash you need to purchase the equipment now instead of losing out on the revenue that the equipment helps you obtain.
Compare Equipment Financing Rates and Total Cost
Use the same purchase price and down payment when comparing offers. Ask for:
- The amount financed and the cash due at signing.
- The interest rate and APR, where provided or required, with an explanation of included fees.
- Origination, documentation, filing, appraisal, and other charges.
- The payment amount, frequency, number of payments, and any final larger payment.
- The total of all scheduled payments and any purchase option amount.
- The cost of paying off the agreement early.
A factor rate or fixed finance charge is not the same as an annual interest rate. Request a complete payment schedule if the agreement does not quote APR. Do not assume early repayment removes all remaining finance charges.
Equipment Financing: Example
For clarity, let's go over an example so you can see how equipment financing might work.
Jen owns a small retail clothing company called Jen’s Threads that makes its own items in-house.
One of Jen's specialty sewing machines worth several thousand dollars has broken. She needs to replace it quickly or risk a major slowdown on her production line that will cost both time and money.
And, let’s say that machine costs $5,000.
In this hypothetical example, Jen puts $500 down, or 10%, and finances the remaining $4,500 over 24 months at 14% fixed annual interest. Her estimated monthly payment is $216.06. The example assumes monthly payments and no balloon, with taxes and other purchase costs excluded.
The scheduled loan payments total approximately $5,185.39, including $685.39 in interest. Adding the $500 down payment brings the total purchase outlay to $5,685.39, before taxes and other purchase costs.
This is an illustration, not a financing offer or a typical Excel Capital rate. Totals use the unrounded monthly calculation; the final payment may be adjusted for rounding.
That $685.39 is the interest cost of spreading the financed portion of the purchase over two years. To decide whether financing makes sense, Jen would compare the full borrowing cost with lost sales, repairs, or renting another machine while saving for the purchase.
Ultimately, you’ll have to judge if obtaining that equipment quickly is worth the interest cost for you in your own situation.
Waiting to save the money can also carry a cost, especially if the equipment is essential to filling customer orders. Compare the lost income or rental expense with the cost of borrowing.
So, it’s important to consider what you’re gaining and losing by taking both routes and make the choice you believe is best for your business long-term.
Equipment Financing and 2026 Tax Updates
Section 179: higher limits for tax years beginning in 2026
The maximum Section 179 deduction is $2,560,000 for tax years beginning in 2026. The limit is reduced dollar for dollar when the cost of Section 179 property placed in service during the year exceeds $4,090,000. Certain vehicles have separate limits. See IRS Revenue Procedure 2025-32.
Eligibility still matters. Section 179 generally requires more than 50% business use and is subject to a business-income limit. Ordering a machine or signing financing documents does not by itself establish that the equipment was placed in service. Keep delivery, installation, and business-use records for your tax preparer.
100% bonus depreciation and the January 2026 guidance
The federal law enacted on July 4, 2025, commonly called the One Big Beautiful Bill Act, restored permanent 100% bonus depreciation for qualifying property generally acquired and placed in service after January 19, 2025. The IRS issued Notice 2026-11 with interim guidance in January 2026. Acquisition rules, elections, and the transaction structure can affect eligibility.
Section 179 and bonus depreciation do not allow the same equipment cost to be deducted twice. A deduction reduces taxable income rather than reimbursing the purchase price, and the financing still has to be repaid. Ask your tax adviser to confirm federal and state treatment, including who is treated as the owner under a lease.
Confirm your purchase's tax treatment
Equipment used in your business may qualify for depreciation or, when eligible, Section 179 expensing. The treatment depends on the property, business use, timing, transaction structure, and applicable limits. Financing does not automatically make the entire purchase immediately deductible.
Discuss the purchase with your tax adviser before signing if tax treatment affects your decision. The IRS explains the eligibility rules in Publication 946.
Recent Commercial Financing Disclosure Rules
California's SB 362, signed in October 2025, strengthens rules against misleading use of terms such as interest and rate and requires APR terminology in specified circumstances. California's financial regulator recommends requesting commercial financing disclosures and reviewing the APR before signing. See the DFPI explanation of SB 362.
For covered Florida transactions, Florida Statutes section 559.9613 requires written disclosures that include funding amounts, total payments, dollar cost, payment details, and prepayment costs or discounts. Coverage and exemptions vary by provider and transaction. These are not identical nationwide requirements, and a calculator estimate does not replace applicable written disclosures.
Before you sign: Confirm the cash purchase price, amount financed, every fee, payment schedule, and final ownership obligation. The tax and legal information here is general, not advice for your individual business. Sources reviewed October 13, 2026.
Questions About Equipment Financing and Loans
How long can you finance equipment?
Available terms depend on the financing program, the equipment, and your qualifications. Ask for a term that fits both your payment capacity and the equipment's expected useful life. Compare total cost as well as the monthly payment.
Can I finance used or refurbished equipment?
Yes, some financing programs accept used or refurbished equipment. Confirm the seller and asset requirements, especially for a private sale or auction. Expect questions about condition, ownership, and value.
Can I get used equipment financing with bad credit?
Some providers consider bad credit equipment financing requests for used assets, but approval depends on more than the score. Expect a review of business cash flow, existing debt, the equipment's condition and value, and the proposed down payment. Confirm the seller and asset are eligible before paying a nonrefundable deposit.
Does a 550 FICO score qualify me for the 14% starting rate?
No. A 550 FICO score is the starting point for considering some applications, not a promise of approval or pricing. The 14% starting annual interest rate is available only on qualifying transactions. The lender's written offer establishes your rate, fees, payment schedule, and other conditions.
Can I get equipment financing with no money down?
Some providers offer financing without a down payment for qualifying transactions. That does not necessarily mean nothing is due at signing. Ask about fees, advance payments, taxes, and costs excluded from the financing.
How do I get prequalified for an equipment loan?
Start with the equipment quote, the amount you need, and basic information about your business. Ask what a preliminary review includes and whether it involves a credit inquiry. Prequalification is not final approval; the equipment and supporting documents may still need review.
Is an equipment finance agreement a lease?
Not necessarily. An EFA commonly finances an equipment purchase while the borrower holds title and the provider has a security interest. A lease generally gives you the right to use equipment owned by the lessor. Read the actual agreement for ownership and payment terms.
How should I compare equipment financing companies?
Compare whether each provider accepts your equipment and seller, what documents it needs, and the written cost and terms it offers. Ask who will fund and service the agreement, what security is required, and what must happen before the seller receives payment.
Discover the Best Equipment Financing Options for You with Excel Capital
Equipment financing offers a unique funding solution if you're in need of replacing a critical piece of equipment fast.
If an important piece of equipment has recently broken or become old and less reliable, compare the cost of financing with the cost of waiting, repairing, or renting. The right choice depends on your business and the equipment.