

What is a business term loan?
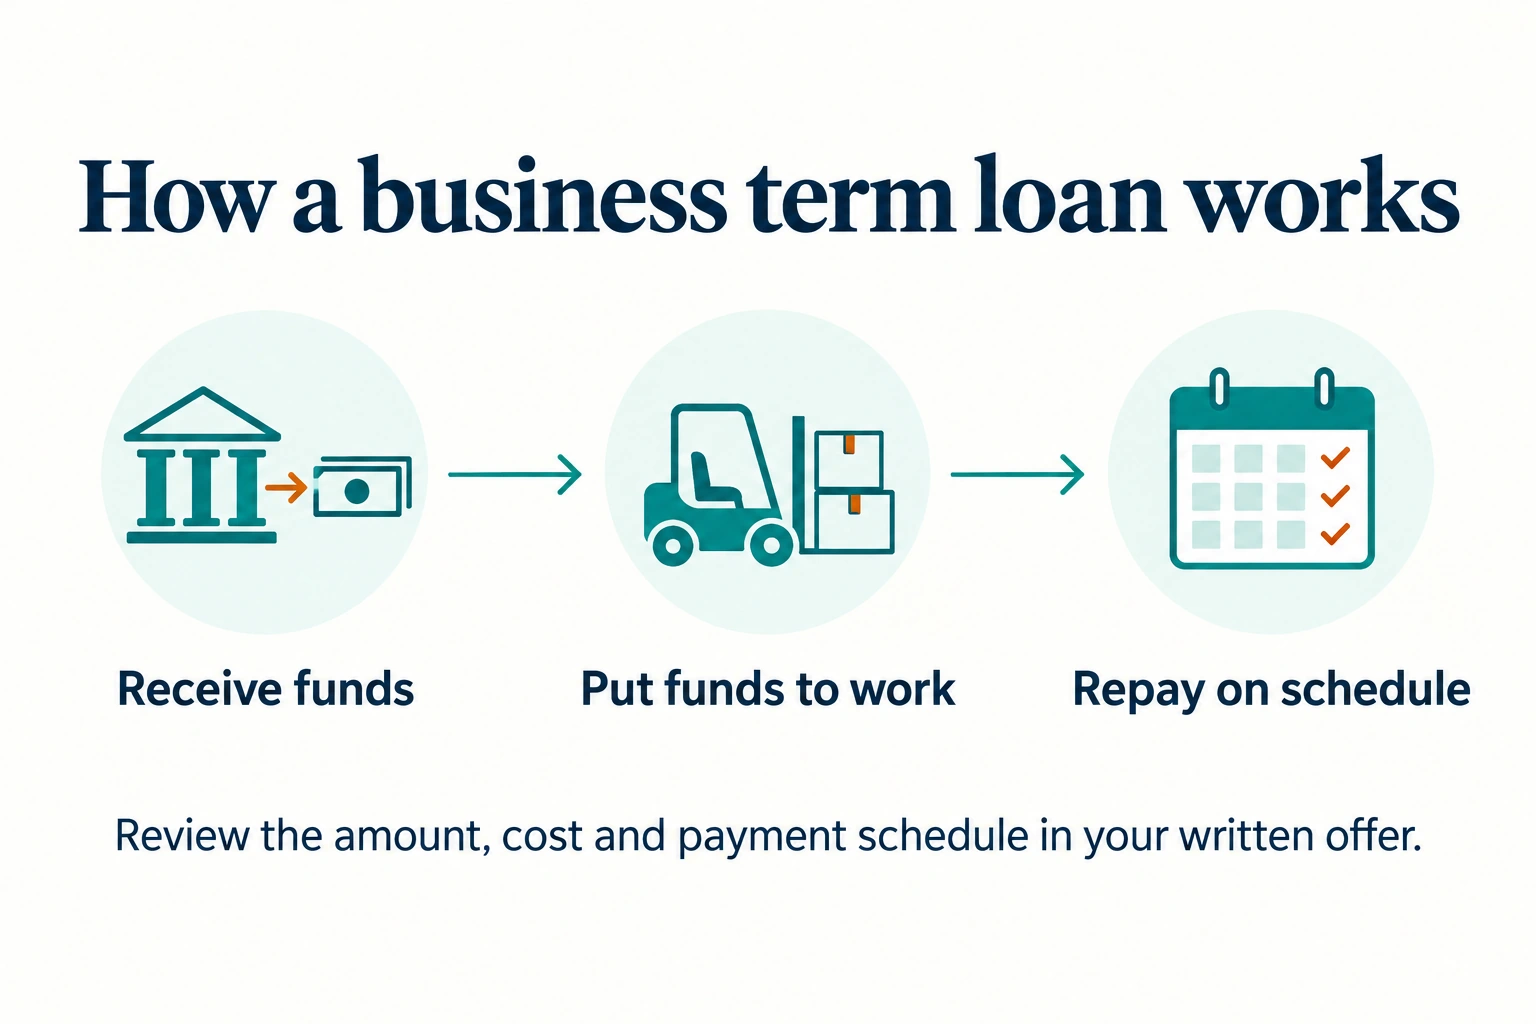
A business term loan provides a lump sum of money that you repay over an agreed period, with interest or other financing charges. Your agreement sets the term, payment frequency and cost. Payments may be daily, weekly or monthly, depending on the product.
A term loan can help you fund a defined expense now and spread repayment over time. Unlike a revolving line of credit, paying down the balance does not automatically replenish an amount you can borrow again. Our guide to revolving vs. installment credit explains how these borrowing structures differ.
Term loans are one type of small business loan. That broader category also includes other borrowing structures. Here, the focus is choosing a lump sum, a repayment period and an offer your cash flow can support.
Put the funding to work
- Purchase inventory for a known sales season.
- Replace equipment or upgrade operations.
- Renovate a location or fund an expansion.
- Bridge a temporary working capital gap with a clear repayment plan.
Start with the expense, when it will generate cash, and the payment your business can carry through a slower month.
Short-, medium- and long-term business loans
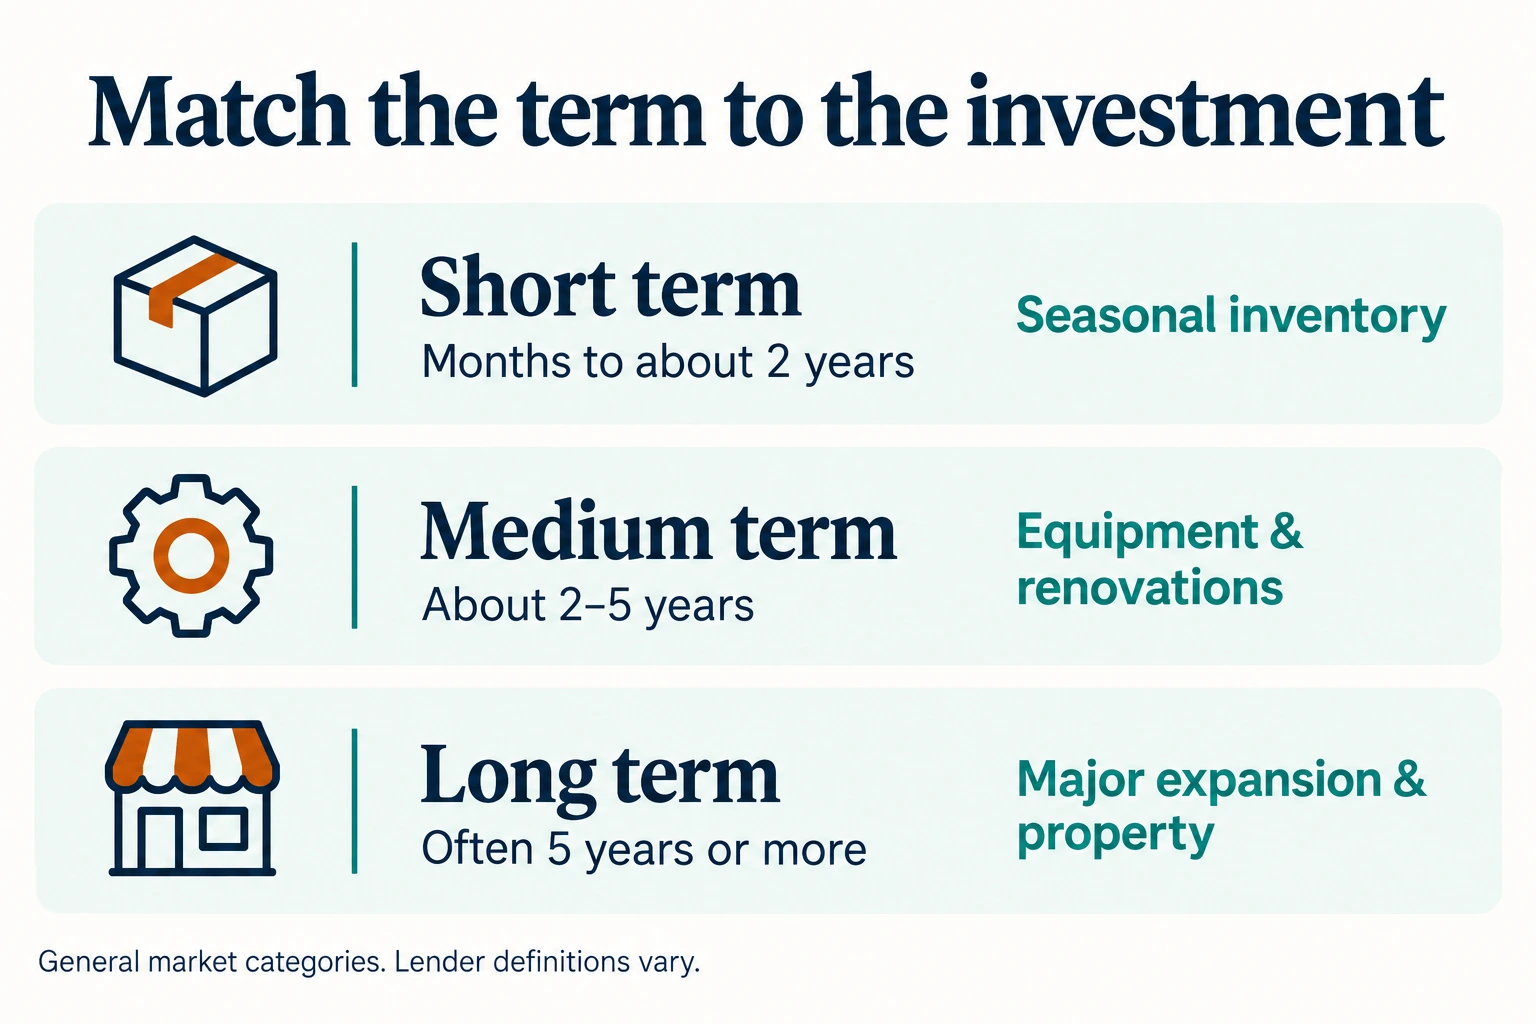
The right term depends on how long you need the money and when the investment should pay off. Lenders use these labels differently, so compare the actual number of months in each offer. The ranges below are a general guide to the market.
Short-term business loans
Usually months to about 2 years
Short-term loans can suit inventory purchases, seasonal expenses or a temporary cash gap with a defined source of repayment. Excel Capital’s available term options start at six months, subject to qualification.
A shorter payoff period concentrates repayment into fewer months. Check the daily or weekly payment against cash available after payroll, rent, taxes and existing debt.
Medium-term business loans
Often about 2 to 5 years
Also called intermediate-term loans, these can suit equipment, renovations or an expansion expected to produce returns over several years. Some lenders classify loans starting at one year as medium-term.
Spreading repayment over a longer period can reduce each payment compared with a shorter loan at the same rate. It can also increase total interest. Match the repayment period to the useful life of the purchase and a realistic cash-flow forecast.
Compare available terms of up to five years with Excel Capital as part of the same application.
Long-term business loans
Often 5 years or longer
In the broader market, long-term financing can support major equipment, acquisitions or commercial property. Certain bank and SBA programs provide terms beyond five years, depending on the use of funds and program rules. See the SBA’s 7(a) loan program guidance for program-specific eligibility and repayment information.
The term options featured on this page run from six months to five years. If your project needs a longer repayment period, compare the relevant bank, SBA or asset-specific program separately, including its documentation and collateral requirements.
Choosing between short- and long-term business loans
The right repayment term depends on what the money will fund and what your business can comfortably repay. Match the repayment period to the expected benefit of the purchase, while leaving room for slower sales or unexpected expenses.
| Consideration | Shorter repayment term | Longer repayment term |
|---|---|---|
| Typical use | Seasonal inventory or a temporary cash-flow gap | Equipment or an investment that delivers value over several years |
| Payment size* | Higher payments | Lower payments |
| Total interest* | Less interest overall | More interest overall |
| Main tradeoff | Greater pressure on near-term cash flow | A longer financial commitment |
*Payment and interest comparisons assume the same loan amount, interest rate, fees, and payment frequency on a fully amortizing loan. Actual offers can differ.
Before choosing, compare the amount received, payment frequency, total repayment, fees, and early-payoff terms. A shorter term does not automatically mean faster funding, and paying early does not always reduce the cost.
Other financing options work differently from term loans. Business lines of credit provide revolving access to funds; merchant cash advances and invoice factoring involve receivables; equity financing exchanges an ownership stake for capital. Compare these separately from loans with a fixed repayment term.
Where does a merchant cash advance fit?
Some short-term financing options use a factor rate or a fixed total payback. Pricing alone does not identify the product. A merchant cash advance is generally structured as a purchase of future business receivables, which differs from a term loan. Check the contract for the financing type, payment or remittance schedule, and any sales-based adjustment provisions.
Choose a term that fits your cash flow
A term loan may fit when…
- You know the amount needed for a specific business expense.
- The investment has a realistic path to generating cash or saving costs.
- Your business can support scheduled payments alongside existing obligations.
Consider another structure when…
- You need to borrow, repay and borrow again for recurring expenses.
- Your cash flow changes significantly from month to month.
- You need a longer term than the available offer provides.
For a seasonal purchase, plan around when inventory becomes collected revenue. For equipment, compare the term with its expected useful life. A low payment is helpful only if the total cost and repayment period also make sense.
Build a cash flow forecast that includes loan payments and seasonal expenses. Iowa State University Extension’s business loan guide explains why cash flow timing should match the loan repayment schedule.
Business term loan rates and costs
Pricing depends on the product, amount, term, credit profile, business performance and existing obligations. An interest rate, APR and factor rate describe different things. Compare offers using the same measures before deciding which costs less.
The FTC’s discussion of small business financing highlights why clear cost and repayment information matters. Request the payment schedule, fees and total repayment in writing.
- Interest rate
- The rate charged on the loan balance under the agreement. Ask whether it is fixed or variable and how interest accrues.
- APR
- An annualized measure that reflects the amount and timing of payments and applicable financing charges. It can help compare loan costs when calculated on a consistent basis.
- Factor rate
- A multiplier used to determine a stated total payback amount. A 1.20 factor is not 20% APR. Fees and the repayment schedule also matter.
- Total cost
- The amount you pay beyond the funds you receive. Compare net proceeds with total repayment, including any fees paid separately.
Business term loan payment example
For illustration, a $50,000 loan with a fixed 12% annual interest rate, no fees and 36 monthly payments would have a payment of approximately $1,660.72 per month. Total repayment would be about $59,785.76, including $9,785.76 in interest.
This is an amortizing loan example, not a financing quote or an advertised rate. It assumes on-time monthly payments; rounding can affect the final payment. Fees, payment frequency and your actual agreement can change the cost.
How factor pricing translates into dollars
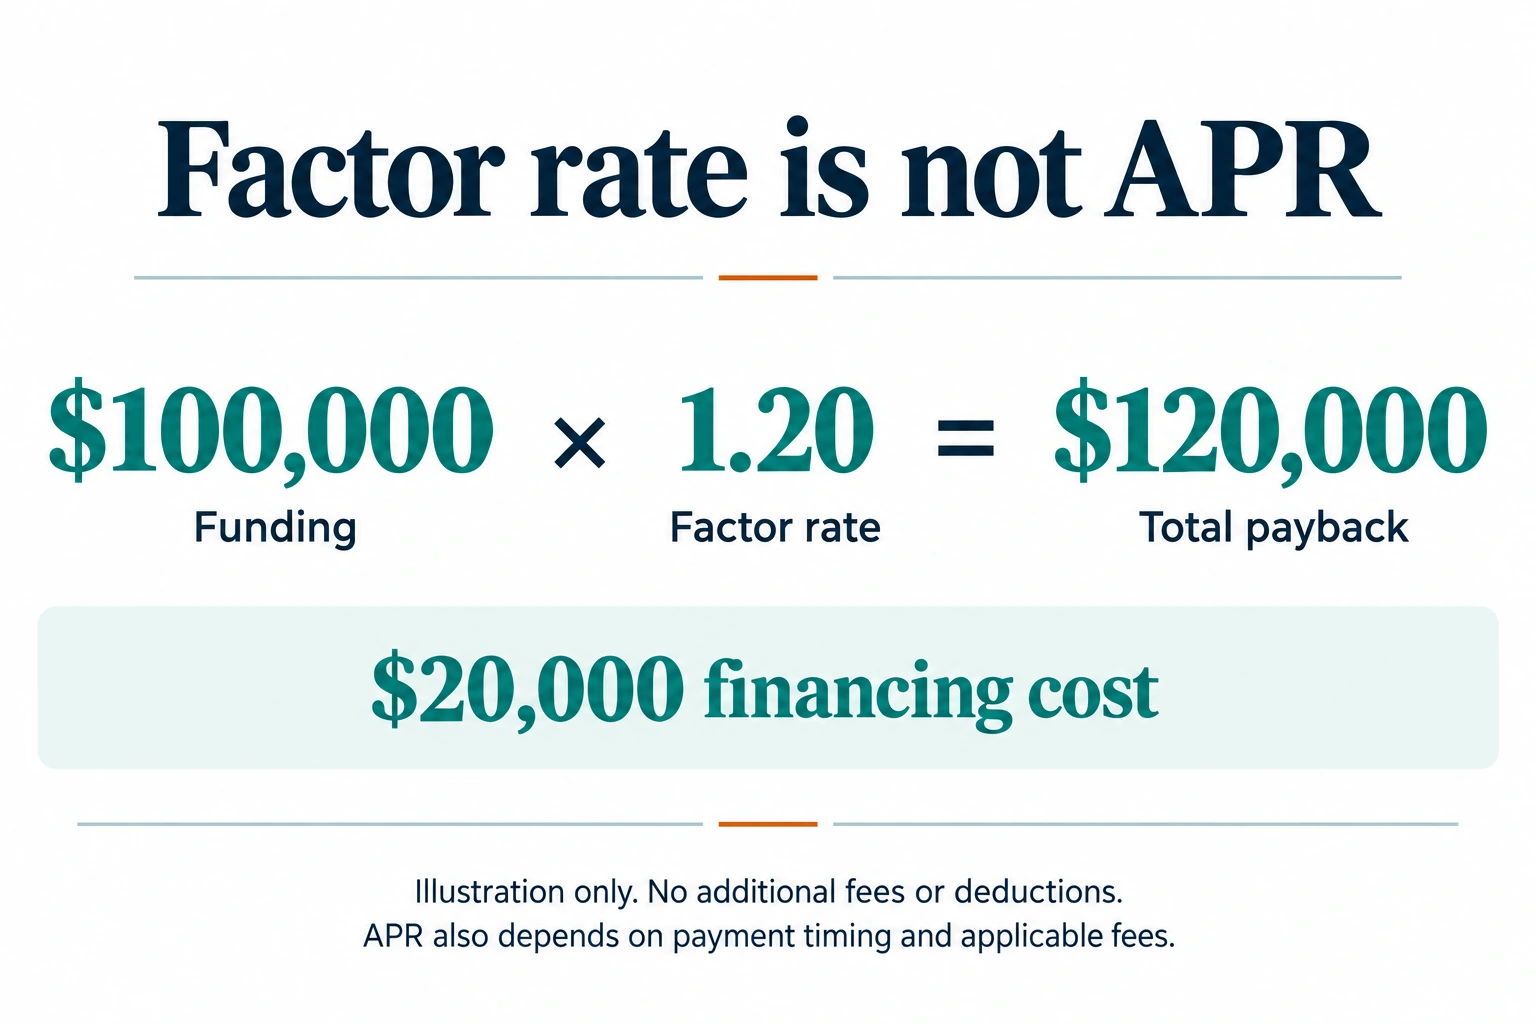
The $20,000 cost is 20% of the original funding amount. It is not a 20% APR. Paying that amount back over six months has a different annualized cost from paying it back over twelve months. The dates and amounts of payments are needed for an APR calculation.
This arithmetic example is not an offer, quoted rate or estimate of eligibility.
Compare these details in every written offer
- Funding amount and net cash deposited after deductions.
- Interest rate or factor rate, plus all applicable fees.
- APR where provided and the assumptions used to calculate it.
- Payment amount, frequency and total repayment.
- Early payoff amount and any actual savings or penalties.
- Collateral, liens, personal guarantees and other obligations.
For an amortizing loan, use our business loan payment calculator to explore how the amount, interest rate and term affect payments. Do not enter a factor rate as an annual interest rate.
Business term loan requirements
Requirements vary by lender and product. These are common areas lenders review, rather than universal minimums:
- Time in business
- Your operating history helps lenders assess stability and whether the program fits your business.
- Revenue and cash flow
- Bank statements and financial records help show whether the business can manage the proposed payments alongside existing expenses.
- Credit and existing debt
- Personal and business credit, current balances and repayment history can affect eligibility and pricing.
- Purpose and amount
- Explain how you will use the funds and how the investment supports repayment. Some programs restrict eligible uses.
- Documents
- Depending on the program, a lender may request business bank statements, identification, ownership details, tax returns, financial statements or a debt schedule.
- Collateral and guarantees
- Ask whether the offer requires specific collateral, a business lien or a personal guarantee, and review those obligations before signing.
Use our business loan requirements checklist to prepare, then confirm the documents needed for your specific application.
How to apply for a business term loan
Start with the amount you need, the purpose of the funds and your preferred repayment period. Qualification varies by product; revenue, cash flow, time in business, personal and business credit, and existing debt can all affect the offer.
Tell us about your funding need
Complete the application with your business details and intended use of funds. Include the timing of the expense and the payment schedule you are seeking.
Provide the requested documents
Be ready with recent business bank statements, ownership information and details of current financing. Depending on the request, underwriting may also require tax returns, financial statements or information about collateral.
Review the offer before accepting
Check the product type, net proceeds, payment schedule, total cost and early payoff terms. Funding and timing depend on approval, completed documentation and the financing agreement.
When another financing option fits better
- Business line of credit
- Consider revolving access when borrowing needs repeat or amounts vary. A term loan provides one lump sum; a line of credit generally allows multiple draws within an approved limit. Compare draw fees, repayment terms and how available credit is replenished.
- Equipment financing
- Compare financing tied to the asset when the purchase is equipment. The equipment may serve as collateral, and its useful life matters when choosing the term.
- SBA financing or bank financing
- Explore programs designed for larger or longer-lived investments when you need terms beyond those available in a standard offer. Eligibility, documentation and timing vary by program.
See the full small business loan comparison to evaluate these options alongside term loans.
Business term loan FAQs
Is a term loan the same as a small business loan?
A term loan is one type of small business loan. “Small business loan” describes the broader borrowing category; “term loan” describes a lump sum repaid over a set period. A small business may also use a revolving line of credit or another financing structure.
How much can I borrow, and for how long?
Excel Capital offers financing options up to $10 million with terms from six months to five years, depending on the product and business qualifications. The maximum amount is not available to every applicant. Your written offer specifies the amount and term available to you.
Are medium-term and intermediate-term loans the same?
The terms are commonly used interchangeably. They usually describe financing that sits between a short payoff period and long-term borrowing, often around two to five years. Lender definitions differ, so use the actual repayment period to compare offers.
Do business term loans have monthly payments?
Some do. Others require daily or weekly payments. The schedule depends on the product and agreement. A fixed interest rate may support level payments, while a variable rate can change your payment or interest cost.
Is a factor rate the same as APR?
No. A factor rate calculates a stated payback amount by multiplying the funding amount. APR expresses borrowing cost on an annualized basis and depends on payment timing and applicable fees. A 1.20 factor rate does not mean 20% APR.
Can I save money by paying off a term loan early?
It depends on the agreement. Some loans reduce future interest when you repay early; other products may retain part or all of a fixed financing charge or impose a prepayment fee. Ask for the exact early payoff amount and compare it with the remaining scheduled payments.
Will I need collateral or a personal guarantee?
Requirements vary. Some products require specific collateral, a business lien or a personal guarantee. Even unsecured business loans can carry a personal guarantee or other contractual obligations. Review these terms before accepting funding.
Find a repayment plan that fits your business
Tell us what you need to fund. Compare the amount, term and cost available to your business before choosing an offer.
See your funding optionsFurther reading: SBA 7(a) program information and the FTC’s overview of small business financing. Product availability, qualifications and terms vary; the financing agreement governs your offer.