

Schedule K-1 reports your share of tax items—but the right version depends on whether you are a partner, shareholder or beneficiary. Compare the forms first, then explore the S corporation K-1. You can switch between all four K-1 versions.
Comparison reviewed September 21, 2026 against IRS guidance. Interactive field explanations cover the four 2025 K-1 versions. General education, not tax, legal or accounting advice.
Own 100% of your business? You can still receive a K-1 if your business is taxed as an S corporation, but your role is shareholder. Sole ownership does not automatically make you a “100% partner.” The tool below starts with the S corporation K-1 and offers all four K-1 versions.
Understand your K‑1, one field at a time
Choose your K-1 form, then select a field to see what it means. Explore all four versions in one guide.
Explore the K-1 tool Educational guide. No tax information required.

What Is IRS Form Schedule K-1?
Schedule K-1 reports a partner’s, shareholder’s or beneficiary’s share of income, deductions, credits and other tax items. The form number identifies which set of rules and instructions applies.
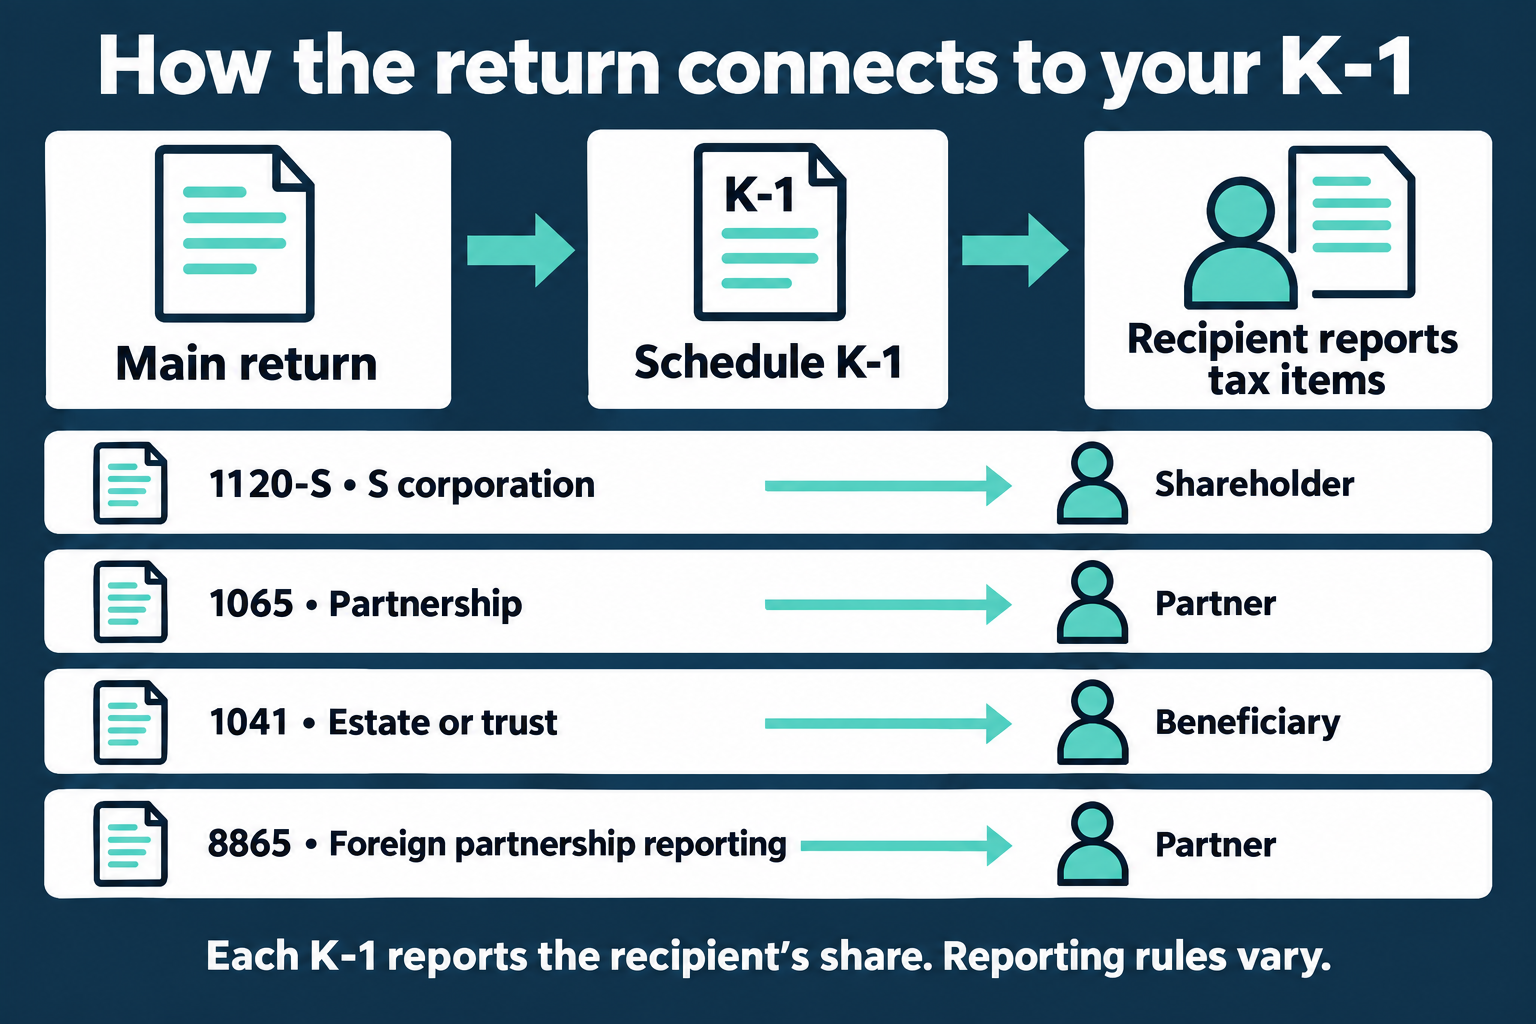
The familiar domestic versions accompany Form 1065 for partnerships, Form 1120-S for S corporations and Form 1041 for estates and trusts. Schedule K-1 (Form 8865) is used in certain foreign partnership reporting. A C corporation’s Form 1120 is not a K-1.
Start with the comparison below. The interactive tool below starts with the 2025 S corporation Schedule K-1 (Form 1120-S) and includes partnership, trust/estate and foreign partnership views.
What Is K-1 Income?
K-1 income is your share of income from a partnership, S corporation, estate or trust. It’s reported on a tax form called Schedule K-1 and can include business profits, rental income, interest, dividends or capital gains. You use that information when preparing your own tax return.
The part that often causes confusion is that K-1 income doesn’t always match the money you received. If you own part of a partnership or S corporation, you may need to report your share of its profits even if the business keeps the cash.
Your K-1 can also show losses, deductions and credits. Each item has its own reporting rules, so you shouldn’t add every number on the form together as one income total. The IRS explains how partnership income is reported.
A Simple K-1 Income Example
Say you’re a partner in a business that earns $100,000 in ordinary business profit. Under the partnership agreement and applicable tax rules, your share is 25%. Your K-1 would report $25,000 in ordinary business income.
Now suppose the business pays you $10,000 and keeps the remaining cash to cover future expenses. You generally still report the full $25,000 allocated to you.
The $10,000 payment is called a distribution. It’s recorded separately from your share of the profit and follows its own tax rules. That’s why it helps to check both your income allocation and your distributions when reviewing a K-1. The IRS partner instructions explain this distinction.
How Is K-1 Income Taxed?
There’s no single tax rate for K-1 income. What you owe depends on the kind of income reported, the entity that issued the form and your tax situation.
Business profits generally follow ordinary income tax rules. Qualified dividends and long-term capital gains may qualify for lower rates.
K-1 income is also separate from a paycheck. If you work for an S corporation you own, you may receive a W-2 for your salary and a K-1 for your share of the company’s income. S corporation pass-through income generally isn’t subject to self-employment tax. Some partnership income is, depending on the income and your status as a partner. See the IRS guidance for S corporation shareholders and partners.
Which Schedule K-1 Form Do You Have?
Look at the form number in parentheses under “Schedule K-1.” There is no single generic K-1: the version depends on the entity’s federal tax treatment and your role.
Partnership K-1
Your role: Partner
A partnership reports each partner’s allocated share of income, deductions, credits and other tax items.
Generally involves at least two tax owners. A sole owner is not simply a “100% partner.”
Read the partnership instructions ↗Explore the 2025 Form 1065 fields ↓
S corporation K-1
Your role: Shareholder
An S corporation reports each shareholder’s share of its tax items. Its K-1 has a different layout from the partnership version.
A sole shareholder who owns 100% of an S corporation still receives this K-1. An LLC with an effective S election follows S corporation reporting.
Trust or estate K-1
Your role: Beneficiary
An estate or trust reports a beneficiary’s share of income, deductions and credits under the applicable distribution rules.
A sole beneficiary can receive a K-1, but that does not automatically put all trust or estate income on that K-1. Grantor-owned portions follow different reporting rules.
Foreign partnership K-1
Your role: Partner / U.S. reporting context
Schedule K-1 (Form 8865) reports a partner’s share of a foreign partnership’s tax items as part of applicable U.S. information reporting.
Form 8865 filing categories and exceptions matter. It is not automatically required of every foreign partner, and some foreign partnerships also file Form 1065.
C corporation: no shareholder K-1
A C corporation generally files Form 1120 and pays its own federal income tax. It does not pass its operating income through to shareholders on a K-1. Reportable dividends and certain other distributions are generally reported on Form 1099-DIV.
Owning 100% of a C corporation does not change that. A C corporation can itself receive a K-1 from an investment, but that is different from issuing K-1s to its shareholders.
IRS corporation guidance ↗ · IRS dividend reporting guidance ↗
LLC is a legal label, not a K-1 type. A disregarded single-member LLC generally does not issue a K-1 to its owner. Partnership or S corporation tax treatment can call for the corresponding K-1. Check the IRS classification guidance.
When Should You Receive Schedule K-1?
Timing depends on the return type, the entity’s tax year and any extension. Do not assume every K-1 arrives on the same date.
- Partnership and S corporation: K-1s are generally furnished by the due date of Form 1065 or Form 1120-S, including extensions. Calendar-year returns are generally due March 15, adjusted for weekends and legal holidays.
- Estate or trust: beneficiary K-1s generally follow the Form 1041 deadline, including extensions. A calendar-year Form 1041 is generally due April 15; fiscal-year estates can follow a different calendar.
- Foreign partnership: Form 8865 generally follows the due date, including extensions, of the U.S. filer’s return to which it is attached. Confirm the applicable reporting and delivery arrangements rather than assuming the domestic partnership schedule.
Check the tax year printed on your form. An extension to file your own return generally does not extend the time to pay tax.
How to Read Your Schedule K-1
Start by matching the form number and tax year. Check the entity and recipient details, then read each income, deduction and credit box together with its codes and attachments.
The tool starts with Schedule K-1 (Form 1120-S) for S corporation shareholders. Switch forms for partnership, trust/estate or foreign partnership definitions. Owning 100% or a smaller percentage does not create a different S corporation K-1 layout.
Interactive Schedule K-1 Field Guide
All four K-1 versions have their own form and explanations. Compare the four K-1 types above.
2025 S corporation K-1 · Form 1120-S
Select a field to see the shareholder explanation. On mobile, use the field menu or scroll across the form.

Browse all 35 S corporation K-1 fields
Expand any field for its definition. All explanations are included below and start closed.
Form header · Tax year
Use the tax year shown on this K-1 when matching the instructions and preparing your return.
However, a fiscal year can differ from the calendar year.
Filing status · Final K-1 / Amended K-1
These checkboxes identify a final or corrected K-1.
If the K-1 is amended, review any return you have already filed.
Item A · Corporation’s employer identification number
Identifies the S corporation that prepared this K-1.
First, check that the EIN belongs to the correct business.
Item B · Corporation’s name and address
Shows the corporation’s identity and mailing address.
For example, use the name to distinguish K-1s from different businesses.
Item C · IRS filing center
Identifies the IRS center where the corporation filed, or electronic filing.
In other words, this identifies the corporation’s filing location.
Item D · Corporation’s total shares
Shows the corporation’s total shares at the beginning and end of the year.
Next, compare this total with your own shares in Item H.
Item E · Shareholder’s identifying number
Identifies the shareholder of record.
However, the copy you receive may show only part of the number.
Item F1 · Shareholder’s name and address
Shows the shareholder of record.
In addition, certain ownership arrangements require Item F2.
Item F2 · Person responsible for reporting
Identifies the reporting person for specified disregarded entities, trusts, estates or nominees.
Because trust-specific rules apply, do not assume this always names a beneficiary.
Item F3 · Shareholder entity type
Identifies the type of shareholder of record.
However, the entity type changes the reporting context, not the K-1 layout.
Item G · Current year allocation percentage
Shows the percentage used to allocate this shareholder’s annual tax items.
If you own 100% throughout the year, the allocation is generally 100%. However, midyear changes require time-weighting or applicable special rules.
Item H · Shareholder’s shares
Shows your shares at the beginning and end of the year.
For an LLC taxed as an S corporation, use equivalent units or ownership interests instead.
Item I · Loans from shareholder
Reports debt owed directly by the corporation to this shareholder.
However, a guarantee is not a direct loan. Also, the reported balance may differ from your adjusted debt basis.
Box 1 · Ordinary business income (loss)
Your share of ordinary business profit or loss.
However, this is neither gross revenue nor your salary. Also, limits may reduce your loss deduction.
Box 2 · Net rental real estate income (loss)
Your share of rental real estate results.
In addition, check the activity details and passive-loss rules.
Box 3 · Other net rental income (loss)
Your share of rental results other than rental real estate.
For each activity, also keep its attached statements with the K-1.
Box 4 · Interest income
Your allocated interest income.
On partnership Form 1065, Box 4 means guaranteed payments instead.
Box 5a · Ordinary dividends
Your allocated ordinary dividends.
In particular, qualified dividends in Box 5b are generally included here.
Box 5b · Qualified dividends
The qualified-dividend portion of Box 5a.
Therefore, do not add it to Box 5a a second time.
Box 6 · Royalties
Your allocated royalty income.
Next, use the shareholder instructions to find the reporting details.
Box 7 · Net short-term capital gain (loss)
Your allocated short-term capital result.
Therefore, keep it separate from long-term gains and ordinary income.
Box 8a · Net long-term capital gain (loss)
Your allocated long-term capital result.
In addition, Boxes 8b and 8c identify amounts needing special treatment.
Box 8b · Collectibles (28%) gain (loss)
The collectibles-related capital amount.
However, the label does not mean everyone pays a flat 28% tax.
Box 8c · Unrecaptured section 1250 gain
A real-property-related gain category.
However, special tax-rate rules can apply.
Box 9 · Net section 1231 gain (loss)
Your allocated section 1231 result.
However, its final treatment depends on shareholder-level rules.
Box 10 · Other income (loss)
Additional income or loss identified by codes.
Next, read every code and its supporting statement.
Box 11 · Section 179 deduction
Your allocated section 179 expense deduction.
However, shareholder-level deduction limits still apply.
Box 12 · Other deductions
Separately stated deductions identified by codes.
Because the rules differ by code, check each deduction separately.
Box 13 · Credits
Your share of tax credits, identified by codes.
However, you may not be able to use the full reported credit.
Box 14 · Schedule K-3 attachment
Flags an attached Schedule K-3 with international tax information.
If an attachment is present, also review it.
Box 15 · Alternative minimum tax items
Reports adjustments and preferences relevant to AMT.
However, these items are not automatically extra ordinary income.
Box 16 · Items affecting shareholder basis
Codes report items such as tax-exempt income, nondeductible expenses, distributions and loan repayments.
Track stock and debt basis separately because the K-1 alone may not establish your complete basis.
Box 17 · Other information
Codes and statements supply additional tax information.
For example, this can include section 199A information. It is not a single income total.
Box 18 · Multiple activities: at-risk rules
Signals more than one activity for at-risk purposes.
Therefore, use the attached activity breakdown.
Box 19 · Multiple activities: passive rules
Signals more than one activity for passive-activity purposes.
Therefore, apply the rules to the appropriate activity information.
2025 Trust / estate K-1 · Form 1041
Select a field to see the beneficiary explanation. On mobile, use the field menu or scroll across the form.

Browse all 27 trust / estate K-1 fields
Expand a field to read its explanation. Fields start closed.
Form header · Tax year
Match the tax year to the beneficiary’s reporting instructions.
However, the estate or trust may use a fiscal year.
Filing status · Final / amended K-1
Indicates a final or corrected beneficiary schedule.
However, final K-1 and final Form 1041 are separate indicators.
Item A · Estate or trust EIN
Identifies the estate or trust.
By contrast, the beneficiary’s identifying number appears in Part II.
Item B · Estate or trust name
Names the entity reporting the tax items.
For example, check the source if you receive multiple K-1s.
Item C · Fiduciary name and address
Identifies the person or institution administering the estate or trust.
If information is missing or incorrect, contact the fiduciary for clarification.
Item D · Form 1041-T election
Reports whether and when Form 1041-T was filed to allocate estimated tax payments.
Any related beneficiary credit is reported in Box 13 using its code.
Item E · Final Form 1041
Marks the estate’s or trust’s final income tax return.
Also, review the final-year items and statements.
Item F · Beneficiary identification number
Identifies the beneficiary receiving this schedule.
Check the recipient details.
Item G · Beneficiary name and address
Names the beneficiary whose tax items are reported.
However, a beneficiary is not a business partner.
Item H · Domestic or foreign beneficiary
Indicates the beneficiary’s domestic or foreign status.
In addition, foreign-beneficiary reporting can involve other rules.
Box 1 · Interest income
Taxable interest allocated to the beneficiary.
Next, use the beneficiary instructions to check where to report this amount.
Box 2a · Ordinary dividends
Ordinary dividends allocated to the beneficiary.
Next, use the beneficiary instructions to check where to report this amount.
Box 2b · Qualified dividends
The qualified portion of ordinary dividends; do not count it twice.
Next, use the beneficiary instructions to check where to report this amount.
Box 3 · Net short-term capital gain
Short-term capital gain passed through to the beneficiary.
Next, use the beneficiary instructions to check where to report this amount.
Box 4a · Net long-term capital gain
Long-term capital gain passed through to the beneficiary.
Next, use the beneficiary instructions to check where to report this amount.
Box 4b · 28% rate gain
A gain category subject to special rate rules, not a flat rate for every beneficiary.
Next, use the beneficiary instructions to check where to report this amount.
Box 4c · Unrecaptured section 1250 gain
Real-property-related gain subject to special tax treatment.
Next, use the beneficiary instructions to check where to report this amount.
Box 5 · Other portfolio and nonbusiness income
Other nonbusiness income allocated to you.
Also, review the attached statements and beneficiary-level rules.
Box 6 · Ordinary business income
Your share of business income from the estate or trust.
Also, review the attached statements and beneficiary-level rules.
Box 7 · Net rental real estate income
Your share of rental real estate income.
Also, review the attached statements and beneficiary-level rules.
Box 8 · Other rental income
Your share of other rental income.
Also, review the attached statements and beneficiary-level rules.
Box 9 · Directly apportioned deductions
Coded depreciation, depletion or amortization deductions.
Also, review the attached statements and beneficiary-level rules.
Box 10 · Estate tax deduction
An applicable deduction for estate tax attributable to income in respect of a decedent.
Also, review the attached statements and beneficiary-level rules.
Box 11 · Final year deductions
Coded final-year excess deductions and loss carryovers.
Because the treatment differs by code, not every expense becomes deductible.
Box 12 · AMT adjustments
Coded items relevant to alternative minimum tax.
Therefore, review each code separately.
Box 13 · Credits and credit recapture
Reports credits, withholding or recapture using codes.
However, you may not be able to use the full credit.
Box 14 · Other information
Additional coded tax information, including possible foreign-tax and section 199A details.
Next, check the code list on the reverse and the attached statements.
2025 Foreign partnership K-1 · Form 8865
Select a field to see the foreign partnership explanation. On mobile, use the field menu or scroll across the form.
Form 8865 filing categories and exceptions determine who reports. Not every foreign partnership interest requires the same filing. This guide explains the schedule, not whether you must file it.

Browse all 38 foreign partnership K-1 fields
Expand a field to read its explanation. Fields start closed.
Form header · Tax year
Identifies the foreign partnership reporting period.
First, match the instructions to that tax year.
Filing status · Final / amended K-1
Flags final or corrected partner information.
If the schedule is amended, first review the reason for the correction.
Item A1 · Partnership EIN
Identifies the partnership’s employer identification number, when applicable.
In addition, foreign reporting may use a reference ID.
Item A2 · Reference ID number
Identifies the foreign partnership under the Form 8865 reference-ID rules.
However, this is not the partner’s taxpayer ID.
Item B · Partnership name and address
Identifies the foreign partnership.
First, check the entity and country information.
Item C · Partner SSN or TIN
Identifies the partner under the IRS beneficial-owner rules.
However, do not substitute a disregarded entity’s TIN here.
Item D1 · Partner name and address
Identifies the partner listed in Item C.
Also, review the applicable owner-identification instructions.
Item D2 · Disregarded entity
Identifies a disregarded entity through which the interest is owned.
This supplements the partner details in C and D1.
Item E · Profit, loss, capital and deductions
Shows beginning and ending percentage interests, including applicable constructive ownership.
Part III reports allocations for the direct interest; these percentages are not one universal multiplier.
Item F · Capital account analysis
Summarizes contributions, income, other changes and withdrawals in the capital account.
However, the capital account balance is not automatically the partner’s complete outside basis.
Item G · Unrecognized section 704(c) gain or loss
Tracks beginning and ending net unrecognized built-in gain or loss.
However, this is not simply current taxable income.
Box 1 · Ordinary business income (loss)
Box 1 is the partner’s allocated share of ordinary profit or loss from the partnership’s trade or business activities.
However, this is not the business’s total revenue or the cash paid to you. Also, loss limitations may restrict your deduction.
Box 2 · Net rental real estate income (loss)
Box 2 pulls the partner’s share of rental real estate income or loss out of the ordinary business result.
Passive activity rules often apply, although exceptions exist. Also, check the attached statement for separate rental activities.
Box 3 · Other net rental income (loss)
Box 3 covers rental income or loss other than the rental real estate activity shown in Box 2.
If there is more than one activity, check the attached statement. Also, review the reporting rules and loss limits.
Box 4a · Guaranteed payments for services
Box 4a covers payments to a partner for services when the amount does not depend on the partnership’s income.
Therefore, report them separately from the ordinary income allocation in box 1.
Box 4b · Guaranteed payments for capital
Box 4b covers guaranteed payments other than for services, including payments for the use of capital.
However, guaranteed payments differ from a routine cash distribution.
Box 4c · Total guaranteed payments
Box 4c adds the partner’s guaranteed payments for services and capital into one total.
Do not count this total again in addition to the amounts in boxes 4a and 4b.
Box 5 · Interest income
Box 5 lists the partner’s share of interest income separately from the partnership’s ordinary business result.
Separate reporting preserves the character of this income rather than combining it with box 1.
Box 6a · Ordinary dividends
Box 6a shows the partner’s share of ordinary dividends.
Qualified dividends in box 6b are generally included in this amount, not an additional dividend total.
Box 6b · Qualified dividends
Box 6b pulls out the portion of Box 6a that may qualify for lower tax rates if the requirements are met.
Therefore, do not add this to box 6a as though it were separate additional income.
Box 6c · Dividend equivalents
Box 6c covers dividend-equivalent amounts under the applicable rules. These are distinct from the ordinary and qualified dividend lines.
Next, review the IRS instructions and any partnership statement for the required treatment.
Box 7 · Royalties
Box 7 is the partner’s share of royalty income, such as income earned by allowing someone else to use certain property rights.
The tax treatment depends on the nature of the income and the supporting information.
Box 8 · Net short-term capital gain (loss)
Box 8 shows the partner’s share of net short-term capital gain or loss.
Therefore, keep it separate from ordinary business income and long-term capital gain or loss.
Box 9a · Net long-term capital gain (loss)
Box 9a shows the partner’s share of net long-term capital gain or loss.
For example, other boxes identify collectibles and section 1250 gain that need special treatment.
Box 9b · Collectibles (28%) gain (loss)
Box 9b isolates the collectibles portion needed for the applicable capital-gain calculation.
However, the 28% label does not mean every partner automatically pays a flat 28% tax.
Box 9c · Unrecaptured section 1250 gain
Box 9c isolates certain real-property gain tied to depreciation that needs a separate capital-gain calculation.
Do not treat it as an extra amount to add automatically to all other gains. Follow the supporting statement and IRS worksheet instructions.
Box 10 · Net section 1231 gain (loss)
Box 10 carries the partner’s share of section 1231 gain or loss, which is generally connected with certain business property.
Section 1231 treatment can depend on other gains, losses and prior-year history.
Box 11 · Other income (loss)
Box 11 catches separately stated types of income or loss that do not belong in the earlier income boxes.
Read the letter code and any attached statement because the amount alone does not identify its tax treatment.
Box 12 · Section 179 deduction
Box 12 shows the partner’s allocated section 179 deduction for eligible property.
Because partner-level limits can apply, the reported amount is not automatically the deduction you may claim.
Box 13 · Other deductions
Box 13 groups other separately stated deductions under letter codes.
Read each code and supporting statement because deductions have different eligibility rules and limits.
Box 14 · Self-employment earnings (loss)
Box 14 contains coded amounts used when calculating self-employment tax.
However, it is not necessarily identical to box 1. Partner status, the code and the applicable rules matter.
Box 15 · Credits
Box 15 lists the partner’s share of tax credits under letter codes.
Credits and deductions are different. A credit’s use can be limited by partner-level rules.
Box 16 · Schedule K-3 attachment
A check in Box 16 tells you that Schedule K-3 is attached with more detail, including international tax items.
This is a checkbox, not a dollar amount. Review the attachment when it is provided.
Box 17 · Alternative minimum tax (AMT) items
Box 17 carries the separately coded information used in alternative minimum tax calculations.
However, an entry does not by itself mean you owe AMT. You also need other information from your return.
Box 18 · Tax-exempt income and nondeductible expenses
Box 18 separates tax-exempt income from expenses that are not deductible.
However, these items can still affect the adjusted basis of your partnership interest.
Box 19 · Distributions
Box 19 records distributions and uses codes to distinguish cash, property and deemed distributions.
A distribution is not the same as an income allocation. Cash distributions can trigger gain when they exceed outside basis; property distributions have additional rules.
Box 20 · Other information
Box 20 is a catchall for coded details needed in other tax calculations. Code Z, for example, can carry section 199A information.
Read the attached statements. Do not treat every entry as extra income or assume a code Z entry guarantees a deduction.
Box 21 · Foreign taxes paid or accrued
Box 21 identifies foreign taxes paid or accrued for review under the relevant international tax rules.
However, a foreign tax credit is not automatic. You may also need Schedule K-3 and additional information.
2025 Partnership K-1 · Form 1065
Select a field on the 2025 form to see its explanation, or expand a field in the directory below.
Explore the actual 2025 Schedule K-1 (Form 1065) layout. Select a field to read its explanation alongside the form. On a phone, choose from the menu or scroll across the form.

Expand any field to read its explanation, or use the menu to jump directly to one.
Form checks
Start with the year and filing status.
2 fields
Form headerTax year
The dates identify the partnership tax year covered by this K-1. It can be a calendar year or a fiscal year.
This explorer uses the 2025 form layout. Always use the instructions for the tax year on your actual K-1.
Filing statusFinal K-1 / Amended K-1
Final identifies a final K-1 for the partner. Amended identifies a corrected K-1.
Ask the partnership about a suspected error. Do not change the numbers on your copy yourself.
Part I: Information about the partnership
Identify the partnership that prepared the form.
4 fields
Item APartnership employer identification number
The EIN identifies the partnership issuing the K-1, not the individual partner.
The partner’s own identifying number belongs in item E. This guide never asks you to enter an EIN or SSN.
Item BPartnership name and address
The legal name and mailing address identify the business issuing this Schedule K-1.
Compare this with the entity that issued the form, especially if you own interests in several businesses.
Item CIRS center where the return was filed
Item C names the IRS center where the partnership filed its return.
The partnership or its tax preparer completes this information.
Item DPublicly traded partnership (PTP)
A checked box means the partnership is publicly traded. Special rules can apply to its income and losses.
Do not assume a PTP loss can offset income from another partnership. Consult the PTP instructions.
Part II: Information about the partner
Review the partner, ownership, liabilities and capital details.
14 fields
Item EPartner SSN or taxpayer identification number
Item E lists the partner’s tax identification number. An individual generally uses an SSN or ITIN, while another type of partner generally uses an EIN.
For a disregarded entity, item E generally identifies the beneficial owner, while item H2 identifies the disregarded entity. Special rules apply to IRAs.
Item FPartner name and address
Item F gives the name and address of the partner identified in Item E.
For a disregarded entity, review the beneficial-owner instructions rather than assuming the LLC name belongs here.
Item GGeneral or limited partner / LLC member
The checkboxes show whether the owner is a general partner or LLC member-manager, or a limited partner or other LLC member.
Partner status is relevant to several tax rules. The checkbox alone does not resolve every tax treatment question.
Item H1Domestic or foreign partner
Item H1 marks the partner as domestic or foreign for federal tax purposes.
However, a mailing address alone does not determine the classification.
Item H2Disregarded entity information
Item H2 is used when the partner is disregarded as separate from its owner for federal income tax purposes, as can happen with a single-member LLC.
This field identifies the disregarded entity; items E and F generally identify its beneficial owner.
Item I1Type of entity
The entity type identifies who owns the partnership interest, such as an individual, corporation, partnership, estate or trust.
This describes the partner, not the partnership issuing the K-1.
Item I2Retirement plan partner
The checkbox identifies a partner that is a retirement plan, such as an IRA, SEP or Keogh plan.
Retirement-account ownership has special reporting considerations. Review the applicable IRS instructions.
Item JShare of profit, loss and capital
Beginning and ending percentages show the partner’s share of profit, loss and capital, generally based on the partnership agreement.
A 100% figure in one profit, loss or capital field does not by itself establish sole ownership of the business. These interests can differ. A business with only one owner for federal tax purposes generally is not a partnership; a 100% S corporation owner instead receives the shareholder version, Schedule K-1 (Form 1120-S). For an LLC, compare the tax records with the operating agreement when ownership, voting or distribution rights differ.
Because these percentages can differ, do not use one percentage as a universal multiplier for every K-1 item.
Item K1Share of partnership liabilities
Item K1 breaks the partner’s beginning and ending shares of liabilities into nonrecourse, qualified nonrecourse financing and recourse categories.
Liabilities can affect outside tax basis. Their treatment under the at-risk rules is not identical. Item K1 is a field on Schedule K-1, not a separate form.
Item K2Lower-tier partnership liabilities
A checked box indicates that item K1 includes liability amounts from partnerships owned by this partnership.
Next, review the supporting information to see which liabilities are included.
Item K3Guarantees or payment obligations
A checked box indicates that reported liabilities are subject to guarantees or other payment obligations by the partner.
The IRS directs partners to the instructions for box 20, code X, for additional information.
Item LPartner’s capital account analysis
Item L walks through the year’s tax-basis capital activity, from beginning capital through contributions, income or loss, other changes, withdrawals and distributions, and ending capital.
Capital account is not the same as outside tax basis. In particular, tax-basis capital excludes the partner’s share of partnership liabilities.
Item MProperty contributed with built-in gain or loss
Item M flags property contributed during the year when its fair market value differed from its adjusted tax basis on the contribution date.
A supporting statement provides more information. However, this is not simply the cash contributed to the partnership.
Item NUnrecognized section 704(c) gain or loss
Item N shows the partner’s beginning and ending shares of net unrecognized section 704(c) gain or loss.
However, these balances are not automatically current-year taxable income or deductible loss.
Part III: Income, deductions, credits and other items
Open any box to see what it reports and what can be easy to miss.
29 fields
Box 1Ordinary business income (loss)
Box 1 is the partner’s allocated share of ordinary profit or loss from the partnership’s trade or business activities.
However, this is not the business’s total revenue or the cash paid to you. Also, loss limitations may restrict your deduction.
Box 2Net rental real estate income (loss)
Box 2 pulls the partner’s share of rental real estate income or loss out of the ordinary business result.
Passive activity rules often apply, although exceptions exist. Also, check the attached statement for separate rental activities.
Box 3Other net rental income (loss)
Box 3 covers rental income or loss other than the rental real estate activity shown in Box 2.
If there is more than one activity, check the attached statement. Also, review the reporting rules and loss limits.
Box 4aGuaranteed payments for services
Box 4a covers payments to a partner for services when the amount does not depend on the partnership’s income.
Therefore, report them separately from the ordinary income allocation in box 1.
Box 4bGuaranteed payments for capital
Box 4b covers guaranteed payments other than for services, including payments for the use of capital.
However, guaranteed payments differ from a routine cash distribution.
Box 4cTotal guaranteed payments
Box 4c adds the partner’s guaranteed payments for services and capital into one total.
Do not count this total again in addition to the amounts in boxes 4a and 4b.
Box 5Interest income
Box 5 lists the partner’s share of interest income separately from the partnership’s ordinary business result.
Separate reporting preserves the character of this income rather than combining it with box 1.
Box 6aOrdinary dividends
Box 6a shows the partner’s share of ordinary dividends.
Qualified dividends in box 6b are generally included in this amount, not an additional dividend total.
Box 6bQualified dividends
Box 6b pulls out the portion of Box 6a that may qualify for lower tax rates if the requirements are met.
Therefore, do not add this to box 6a as though it were separate additional income.
Box 6cDividend equivalents
Box 6c covers dividend-equivalent amounts under the applicable rules. These are distinct from the ordinary and qualified dividend lines.
Next, review the IRS instructions and any partnership statement for the required treatment.
Box 7Royalties
Box 7 is the partner’s share of royalty income, such as income earned by allowing someone else to use certain property rights.
The tax treatment depends on the nature of the income and the supporting information.
Box 8Net short-term capital gain (loss)
Box 8 shows the partner’s share of net short-term capital gain or loss.
Therefore, keep it separate from ordinary business income and long-term capital gain or loss.
Box 9aNet long-term capital gain (loss)
Box 9a shows the partner’s share of net long-term capital gain or loss.
For example, other boxes identify collectibles and section 1250 gain that need special treatment.
Box 9bCollectibles (28%) gain (loss)
Box 9b isolates the collectibles portion needed for the applicable capital-gain calculation.
However, the 28% label does not mean every partner automatically pays a flat 28% tax.
Box 9cUnrecaptured section 1250 gain
Box 9c isolates certain real-property gain tied to depreciation that needs a separate capital-gain calculation.
Do not treat it as an extra amount to add automatically to all other gains. Follow the supporting statement and IRS worksheet instructions.
Box 10Net section 1231 gain (loss)
Box 10 carries the partner’s share of section 1231 gain or loss, which is generally connected with certain business property.
Section 1231 treatment can depend on other gains, losses and prior-year history.
Box 11Other income (loss)
Box 11 catches separately stated types of income or loss that do not belong in the earlier income boxes.
Read the letter code and any attached statement because the amount alone does not identify its tax treatment.
Box 12Section 179 deduction
Box 12 shows the partner’s allocated section 179 deduction for eligible property.
Because partner-level limits can apply, the reported amount is not automatically the deduction you may claim.
Box 13Other deductions
Box 13 groups other separately stated deductions under letter codes.
Read each code and supporting statement because deductions have different eligibility rules and limits.
Box 14Self-employment earnings (loss)
Box 14 contains coded amounts used when calculating self-employment tax.
However, it is not necessarily identical to box 1. Partner status, the code and the applicable rules matter.
Box 15Credits
Box 15 lists the partner’s share of tax credits under letter codes.
Credits and deductions are different. A credit’s use can be limited by partner-level rules.
Box 16Schedule K-3 attachment
A check in Box 16 tells you that Schedule K-3 is attached with more detail, including international tax items.
This is a checkbox, not a dollar amount. Review the attachment when it is provided.
Box 17Alternative minimum tax (AMT) items
Box 17 carries the separately coded information used in alternative minimum tax calculations.
However, an entry does not by itself mean you owe AMT. You also need other information from your return.
Box 18Tax-exempt income and nondeductible expenses
Box 18 separates tax-exempt income from expenses that are not deductible.
However, these items can still affect the adjusted basis of your partnership interest.
Box 19Distributions
Box 19 records distributions and uses codes to distinguish cash, property and deemed distributions.
A distribution is not the same as an income allocation. Cash distributions can trigger gain when they exceed outside basis; property distributions have additional rules.
Box 20Other information
Box 20 is a catchall for coded details needed in other tax calculations. Code Z, for example, can carry section 199A information.
Read the attached statements. Do not treat every entry as extra income or assume a code Z entry guarantees a deduction.
Box 21Foreign taxes paid or accrued
Box 21 identifies foreign taxes paid or accrued for review under the relevant international tax rules.
However, a foreign tax credit is not automatic. You may also need Schedule K-3 and additional information.
Box 22More than one activity: at-risk purposes
A check in Box 22 means the partnership reported more than one activity for purposes of the at-risk rules.
Use the attached statement to consider the activities separately where required.
Box 23More than one activity: passive activity purposes
A check in Box 23 means the partnership reported more than one activity for passive activity purposes.
The attached statement supplies the detail needed to apply the passive activity limitations.
Educational field guide, not an IRS filing form. Based on the 2025 partnership Schedule K-1 (Form 1065). The S corporation version uses different boxes. No tax data is entered or collected. Explanations are general education, not tax, legal or accounting advice.
The full field directory remains available without JavaScript. Open any field name to read its explanation.
What Is Each Tax Return Used For—and How Does Schedule K-1 Fit In?
The main return reports the entity’s tax activity or fulfills an information-reporting obligation. A related Schedule K-1 reports a particular partner’s, shareholder’s or beneficiary’s share. Match both the return number and your role before using the figures.
What Is Form 1120-S Used For?
Form 1120-S reports an S corporation’s income, gains, losses, deductions and credits. An eligible corporation—or an LLC with an effective S corporation election—uses this return for years covered by that election. The corporation prepares Schedule K-1 (Form 1120-S) for each shareholder to report that shareholder’s share of tax items.
A shareholder can receive business income, rental income, investment income, deductions and credits on the same K-1. Those items retain their separate tax treatment; they are not one payment total. A sole shareholder who owns 100% still receives a shareholder K-1. Ownership changes during the year can affect the allocation.
Example: a shareholder may report allocated business profit even when the corporation keeps the cash. Wages paid to a shareholder-employee are reported separately on Form W-2. IRS Form 1120-S overview · Shareholder instructions.
What Is Form 1065 Used For?
Form 1065 is the federal partnership information return. It reports the partnership’s income, deductions, gains, losses and other tax items. The partnership generally passes those items through to its partners instead of paying federal income tax on its operating income itself. Each partner’s Schedule K-1 (Form 1065) identifies that partner’s allocated share.
Partnership reporting can apply to general partnerships, limited partnerships, LLPs and LLCs taxed as partnerships. These legal structures do not each have a separate federal K-1 layout. The partnership agreement and tax rules determine allocations; profit, loss and capital percentages are not necessarily identical.
Example: a partner may receive business income and a separately reported guaranteed payment. The form also provides ownership, liability and capital information that an S corporation K-1 does not report in the same way. IRS Form 1065 overview · Partner instructions.
What Is Form 1041 Used For?
A fiduciary uses Form 1041 to report an estate’s or trust’s income, deductions and tax liability when filing is required. Schedule K-1 (Form 1041) reports a beneficiary’s share of income, deductions and credits. The beneficiary’s role differs from a business owner’s: the trust document, estate administration and tax distribution rules determine what is reported.
Some income may be taxed to the estate or trust, while other income is carried out to beneficiaries. A cash distribution is not automatically all taxable income, and a beneficiary’s K-1 is not a statement of their entire inheritance.
Example: a beneficiary may receive interest or dividends through the K-1 even though the estate also distributes principal. Grantor-owned portions follow special reporting rules and do not use this K-1 to report the owner’s items. IRS Form 1041 overview · Beneficiary instructions.
What Is Form 8865 Used For?
Form 8865 is a U.S. information return for certain foreign partnership interests and transactions. Depending on the filing category, a U.S. person may report control or ownership of a foreign partnership, contributions of property, or changes in an interest. The required schedules depend on the filer’s circumstances and applicable exceptions.
Schedule K-1 (Form 8865) reports a partner’s share of income, deductions, credits and other items when required. It resembles partnership reporting, but it is part of a distinct international reporting framework. A foreign partnership can also have Form 1065 obligations; a foreign connection alone does not tell you which return or K-1 applies.
Example: a U.S. person’s ownership in a foreign partnership may trigger information reporting in addition to reporting taxable income. The K-1 alone does not establish all filing obligations. IRS Form 8865 overview · Filing categories and instructions.
What Is Form 1120 Used For—and Why Is There No Shareholder K-1?
A C corporation generally uses Form 1120 to report its income, deductions and credits and calculate its own federal income tax. Unlike an S corporation, it does not allocate its operating income directly to shareholders on Schedule K-1. Reportable shareholder dividends and certain distributions are generally reported on Form 1099-DIV.
Owning all of the company’s stock does not change this distinction. A 100% C corporation shareholder does not receive a shareholder K-1 simply because they are the sole owner. A C corporation can, however, receive a K-1 from an investment it holds.
Example: retained corporate profit is reported by the corporation; a later dividend is a separate shareholder reporting event. IRS Form 1120 overview · Corporation and distribution guidance.
Check the Entity That Prepared Your K-1
Start with the entity’s name, address and tax identification number. Match them to the investment, business, trust or estate you expect. If you receive multiple K-1s, keep each form with its own statements.
- 1120-S: Part I identifies the S corporation.
- 1065: Part I identifies the partnership, including whether it is publicly traded.
- 1041: Part I identifies the estate or trust and its fiduciary.
- 8865: Part I identifies the foreign partnership.
The entity’s EIN is different from the recipient’s identifying number. Our EIN lookup guide explains where a business tax ID appears.
Check Your Role: Shareholder, Partner or Beneficiary
The recipient information tells you whose tax items the K-1 reports. Confirm your name and identifying number, then review the information specific to your role.
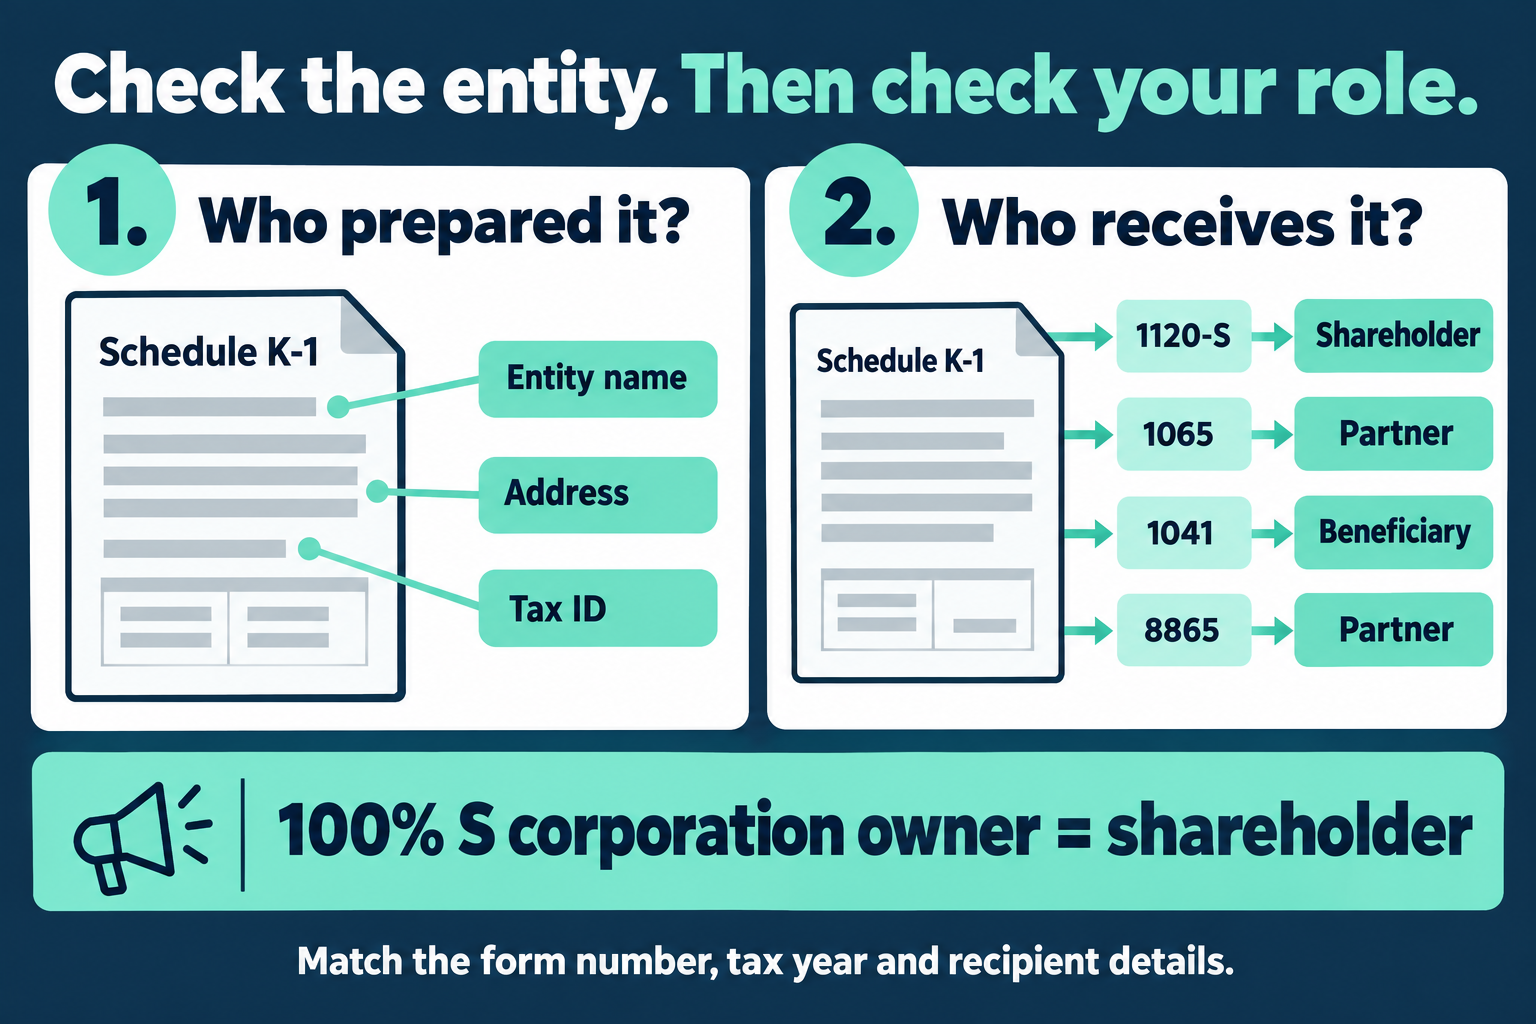
- S corporation shareholder: review the allocation percentage, shares and shareholder-loan information. A 100% owner is still a shareholder.
- Domestic partnership partner: review partner status, profit/loss/capital percentages, liabilities and capital activity. These figures can affect calculations beyond the K-1 itself.
- Estate or trust beneficiary: review beneficiary identification and the information supplied by the fiduciary. Beneficiary status is not the same as a business ownership percentage.
- Foreign partnership partner: review the partner details and ownership information alongside the Form 8865 reporting context. Ownership information does not by itself resolve all filing requirements.
Ask the preparer about incorrect recipient details. Do not change the numbers on the K-1 yourself or assume a percentage alone determines every reported amount.
Read Income, Deductions and Credits Using the Right Box Definitions
All four K-1 versions separate tax items, but their box numbers and letter codes differ. Keep each amount with its label, code and supporting statement. There is no universal K-1 total to copy onto your return.
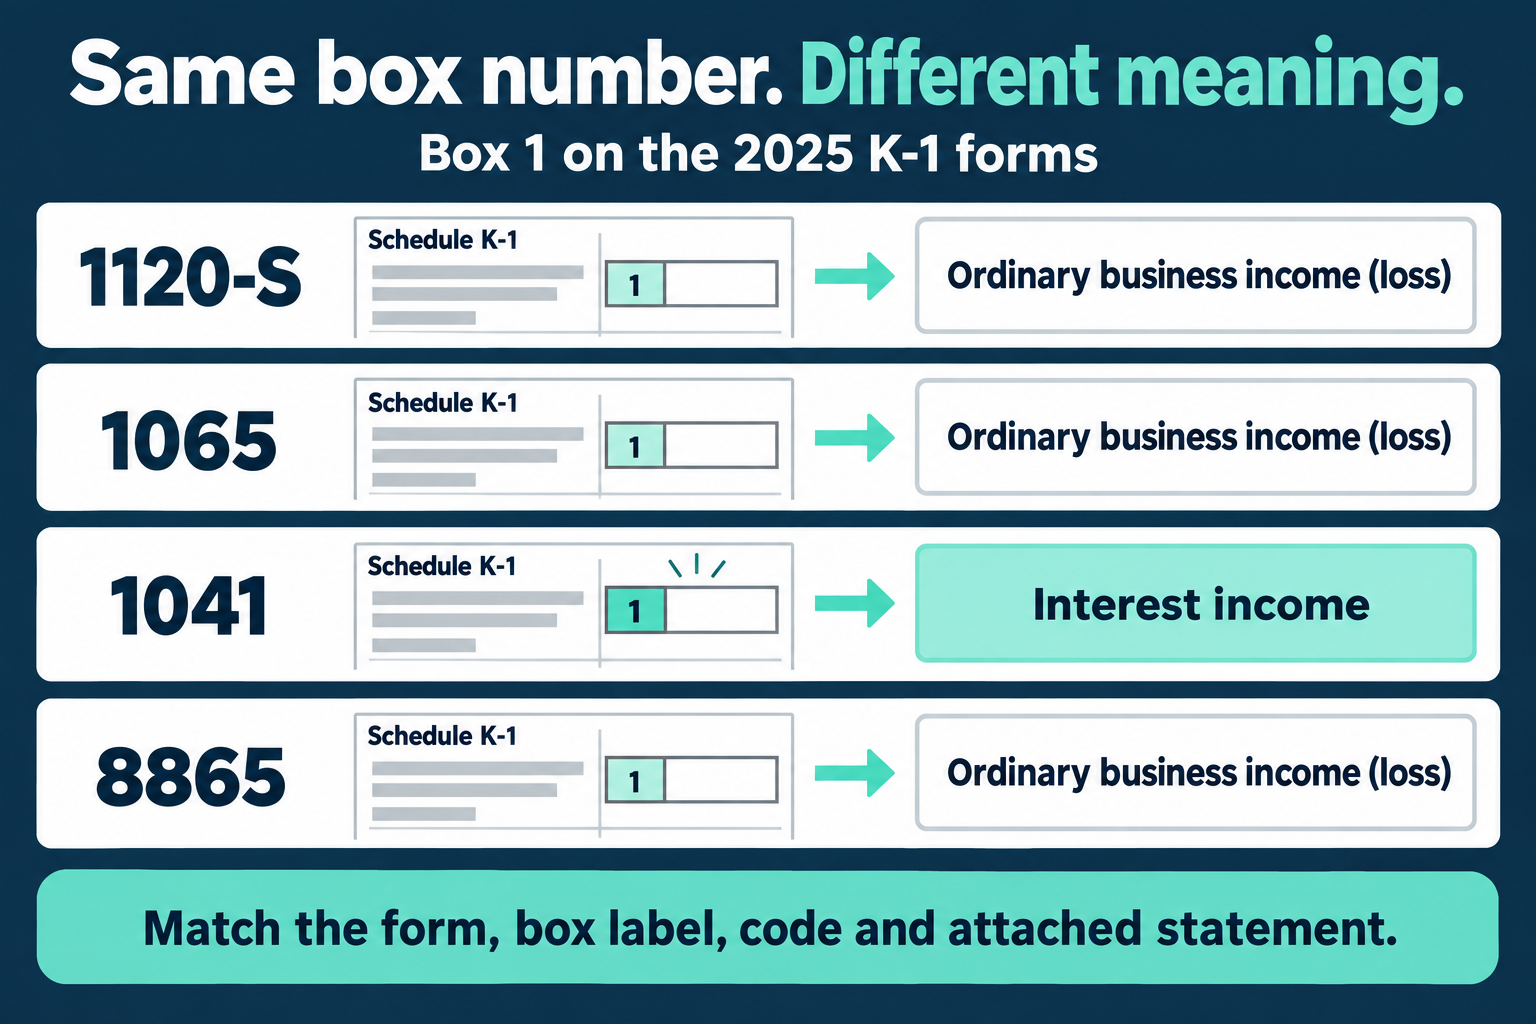
| K-1 version | Box 1 | Box 4 |
|---|---|---|
| 1120-S | Ordinary business income (loss) | Interest income |
| 1065 | Ordinary business income (loss) | Guaranteed payments, split into 4a–4c |
| 1041 | Interest income | Long-term capital-gain categories, split into 4a–4c |
| 8865 | Ordinary business income (loss) | Guaranteed payments, split into 4a–4c |
Use the matching option in the interactive guide to check a field. Attached statements and, where applicable, Schedule K-3 may provide information that does not fit on the face of the K-1. Always follow the instructions for the actual tax year shown on your form.
Income and Distributions: What Changes by K-1 Type?
A K-1 is not a bank statement. The tax items it reports do not necessarily equal cash received. The reason—and the calculation you need—depends on the form.
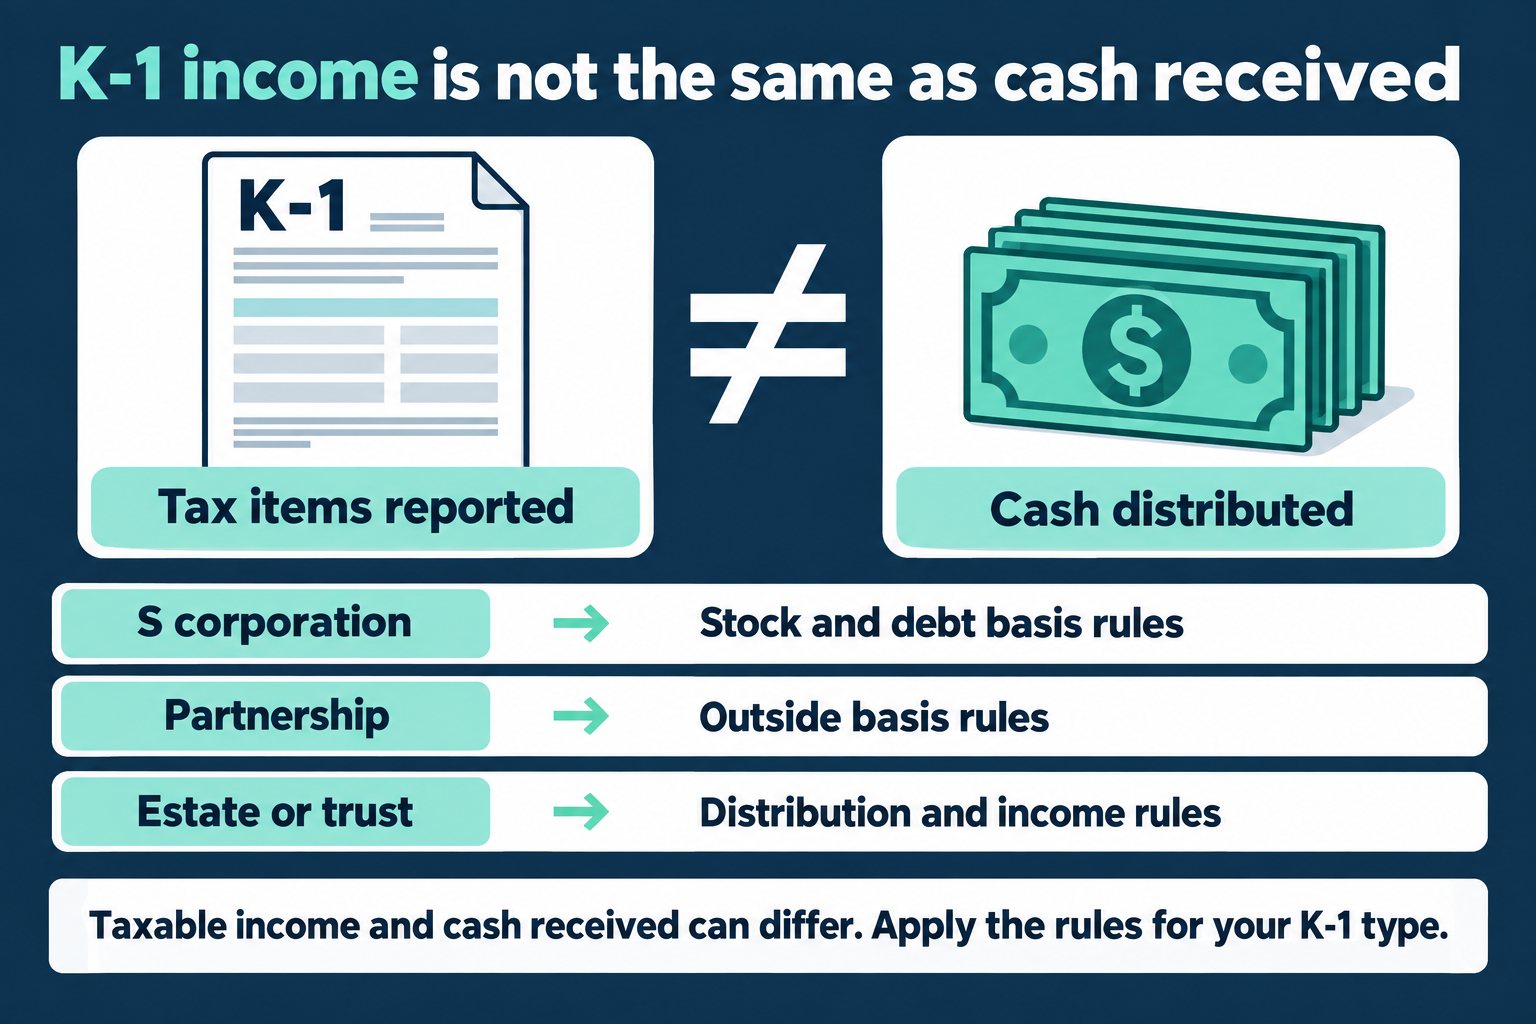
S corporations: stock and debt basis
A shareholder can be taxed on allocated income without receiving cash. Stock basis and qualifying debt basis are separate calculations that can limit loss deductions. For nondividend distributions, stock basis matters; shareholder debt basis does not make those distributions tax-free. IRS stock and debt basis guidance.
Partnerships: outside basis and capital accounts
A partner’s allocated income can differ from distributions. Item L capital on Form 1065 is not a complete outside-basis calculation: liabilities and other transactions can matter. Basis, at-risk and passive activity rules can limit losses. Foreign partnership reporting also requires the applicable U.S. partnership analysis; do not infer basis from a cash distribution or ownership percentage alone. IRS partner guidance.
Estates and trusts: income carried out to beneficiaries
A beneficiary’s taxable share follows estate and trust distribution rules, including distributable net income rules where applicable. Cash or property received may include principal as well as income. Do not apply shareholder stock-basis or partnership capital-account rules to a beneficiary K-1. IRS estate and trust guidance.
Common Schedule K-1 Mistakes Across All Four Forms
- Using box definitions from a different K-1 version or tax year.
- Adding all amounts together instead of keeping income, deductions and credits separate.
- Assuming taxable income always equals cash received.
- Ignoring letter codes, statements or an applicable Schedule K-3.
- Applying partnership capital-account rules to an S corporation shareholder or trust beneficiary.
- Claiming a reported loss without checking the limitations that apply to the recipient.
- Assuming 100% ownership always means “partner,” or that a C corporation issues shareholder K-1s.
- Overlooking foreign reporting obligations because income has already been reported.
- Editing an incorrect K-1 instead of contacting the responsible preparer.
Schedule K-1 Questions for Owners and Beneficiaries
Who prepares Schedule K-1?
An S corporation prepares shareholder K-1s; a partnership prepares partner K-1s; and an estate or trust fiduciary prepares beneficiary K-1s. Form 8865 schedules are prepared as part of the applicable U.S. foreign partnership reporting. Contact the responsible preparer if details are incorrect.
Does a 100% owner receive a K-1?
A sole S corporation shareholder does. A sole C corporation shareholder does not receive a shareholder K-1 from that corporation. A disregarded single-member LLC generally does not issue a K-1 to its owner. Sole ownership does not automatically create a partnership.
Is Schedule K-1 the same as a 1099?
No. A K-1 reports a partner’s, shareholder’s or beneficiary’s share of tax items. Forms 1099 report specified payments or transactions under their own rules. Receiving both can be appropriate; do not assume one replaces the other.
Can I owe tax without receiving cash?
Yes, partners and S corporation shareholders can have taxable allocations without matching cash distributions. Estates and trusts follow different distribution rules; use the beneficiary K-1 and fiduciary’s explanation rather than assuming all cash received is taxable income.
Do all K-1s use the same box numbers?
No. For example, Box 1 on the 2025 Form 1041 K-1 is interest income, while Box 1 on the other three versions is ordinary business income or loss. Always use the matching form instructions.
Is partnership capital the same as S corporation basis?
No. A partnership’s tax-basis capital account, a partner’s outside basis, and an S corporation shareholder’s stock and debt basis are different measures. None should be substituted for another.
Does every foreign partnership interest require Form 8865?
No. Filing depends on the U.S. person’s filing category, ownership or transactions and applicable exceptions. Reporting taxable income does not by itself satisfy every international information-reporting requirement.
What if my K-1 is late or incorrect?
Contact the entity, fiduciary or responsible preparer. Request clarification or a corrected K-1 as appropriate. If a correction arrives after you file, ask your tax professional whether your own return needs to be amended.
Official IRS Sources
Use the instructions for your form and tax year. The interactive guide illustrates the 2025 forms.

