
What is gross profit?
If you’re just starting to dig into the accounting metrics of your business, gross profit is easily one of the most important of those metrics to understand.
Put simply, gross profit is the revenue left after subtracting the cost of goods sold.
By understanding what gross profit is and how to calculate it, you can identify where your costs may be higher than they need to (or should) be, leaving you with a small margin of profit.
That then allows you to make adjustments that can improve profitability and support your business’s cash flow.
Let’s dive into the gross profit formula so you understand everything that goes into it and can make full use of this useful financial metric.
What is the gross profit formula?
The gross profit formula is a simple equation with big implications for your business.
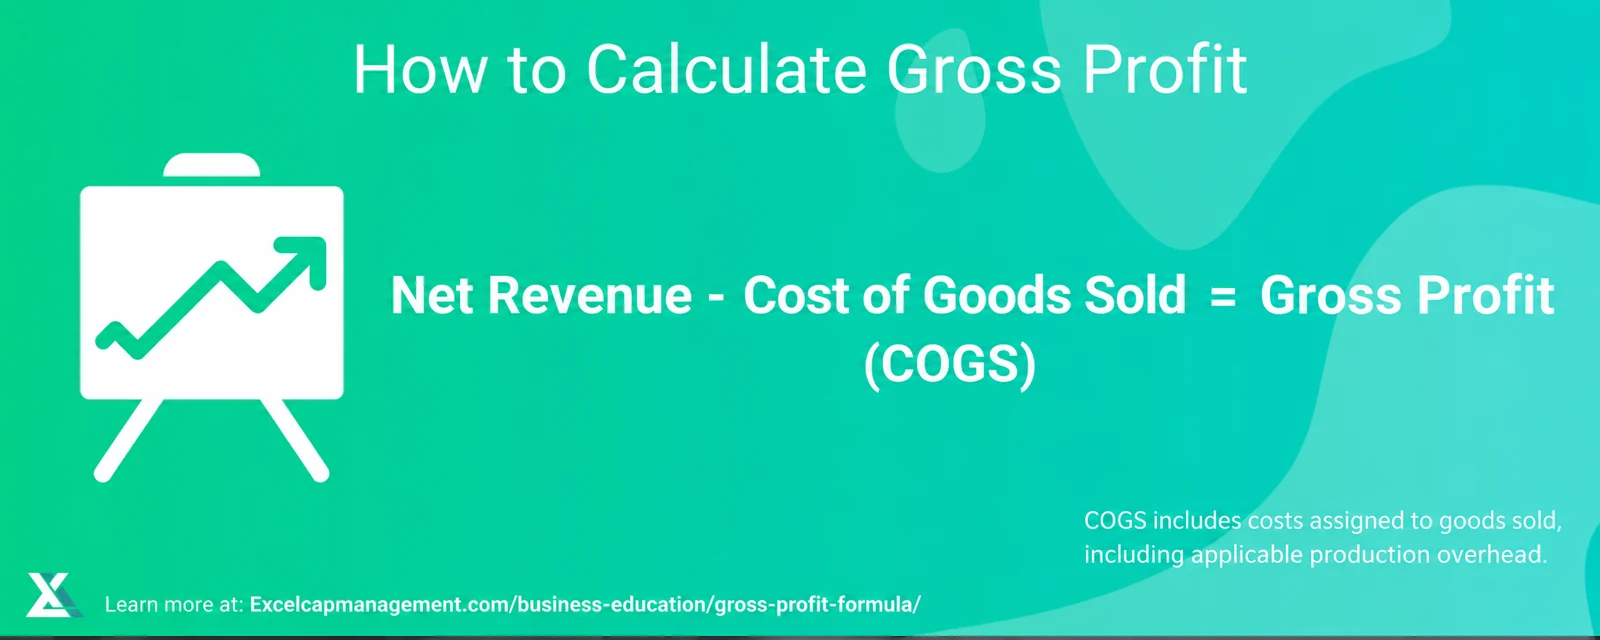
The gross profit equation is as follows:
Net revenue – Cost of goods sold (COGS) = Gross profit
Revenue refers to the amount you earned when a client or customer purchased your product or service. Use net revenue after returns, allowances and sales discounts, and use revenue and costs from the same reporting period.
Cost refers to cost of goods sold (or COGS), the costs assigned to the products sold during that period. A service business may use the label cost of services or cost of revenue for the costs of delivering its work.
When you take the revenue from your product or service and subtract those related costs, you have gross profit.
Gross profit calculator
Enter net revenue and COGS for the same period, or a sale price and the cost of that one sale. Use cost of services for a service business. Amounts are in US dollars.
This calculator estimates gross profit, not net income, taxes or available cash. Calculations run in your browser; this tool does not submit your entries.
Enable JavaScript to use the calculator. You can also subtract COGS from net revenue, then divide the result by net revenue and multiply by 100 for gross margin. Margin is undefined when revenue is zero.
What costs are included in calculating gross profit?
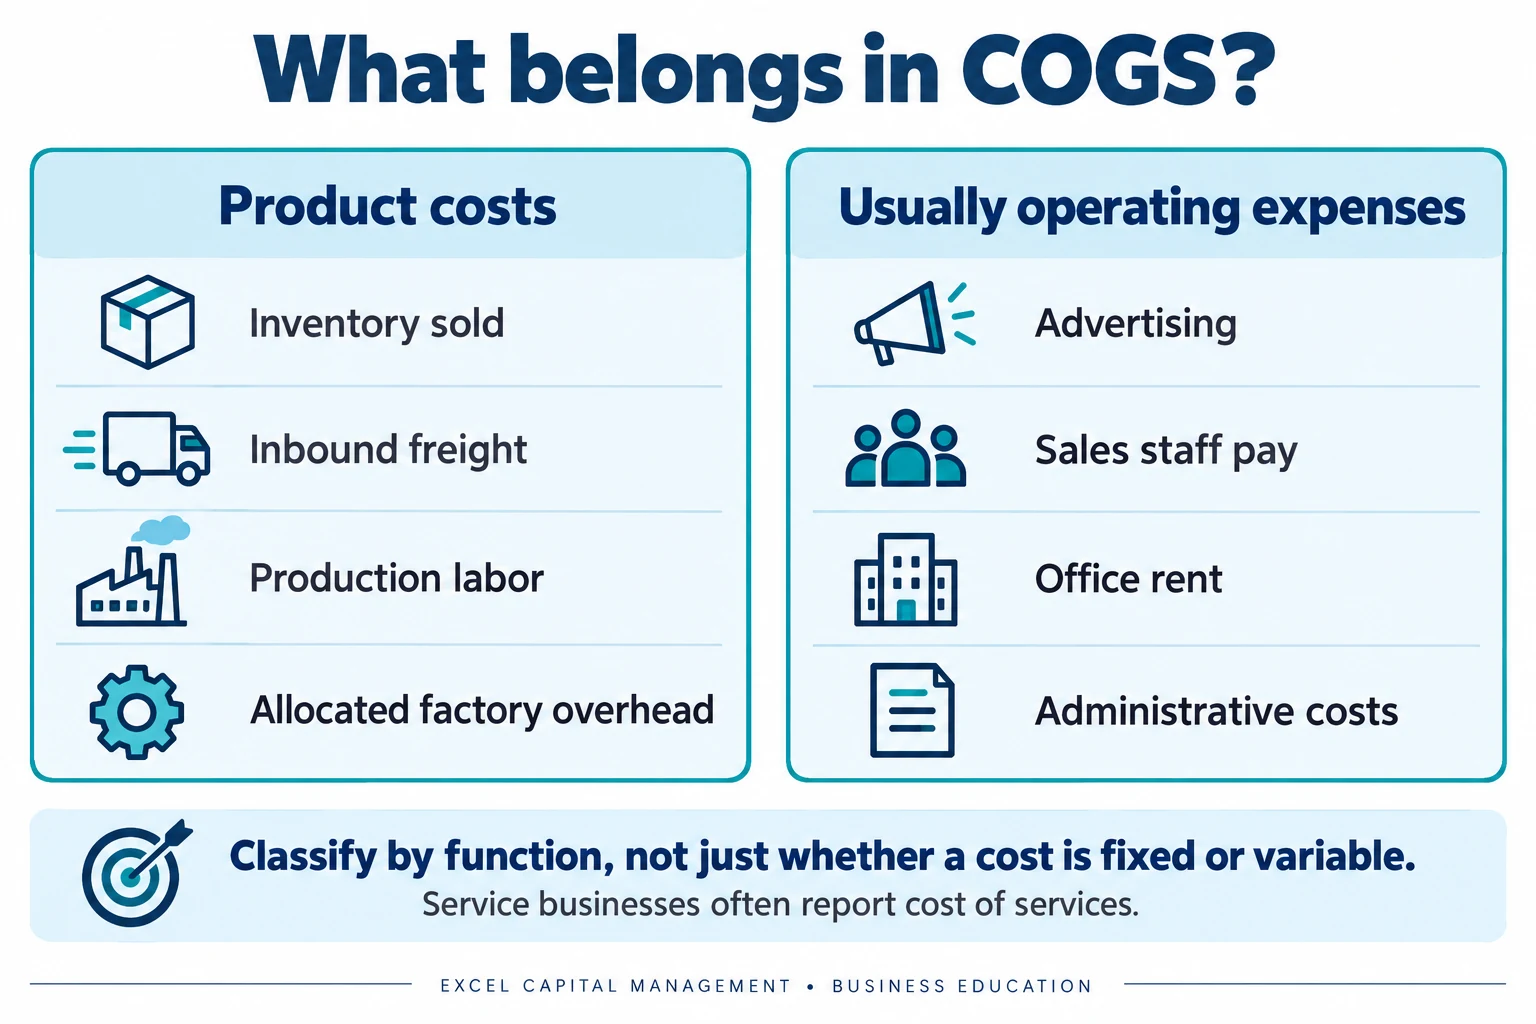
It’s important to understand that your cost of goods sold includes the costs of acquiring or producing the goods you sold. It does not automatically include every expense associated with selling them.
That refers to both fixed and variable costs.
What that means is your cost of goods sold includes variable expenses (expenses that change frequently and depending on the product or service) such as:
- Materials used in products sold
- Direct production labor
- Inbound freight on inventory purchased for resale
- Merchandise purchased for resale and sold during the period
But it can also include certain fixed expenses, including:
- Payroll for employees whose jobs are associated with production quality
- Depreciation of production equipment allocated to the goods sold
What about other fixed expenses?
Fixed expenses are where gross profit gets tricky (and where it’s generally best to leave it to an accountant).
That’s because some fixed expenses can be considered a part of your cost of goods sold while many aren’t.
Costs associated with sales and general administration are usually operating expenses and aren’t included in the gross profit formula:
- Retail store or administrative office rent
- Payroll of non-production-related employees
- Payroll taxes and benefits for sales or administrative staff
- Advertising
- Office expenses
- General business insurance unrelated to production
Factory rent, production-related insurance, and factory employee benefits may instead be part of production overhead. Credit card processing fees and outbound delivery costs need careful classification; do not automatically treat them as inventory costs.
Use a consistent accounting policy that fits your business and applicable accounting rules. Moving costs between COGS and operating expenses can change gross margin without changing total profit. The IRS guide to cost of goods sold explains merchandise, freight-in, production labor and overhead for tax reporting.
How inventory changes the COGS calculation
For a retailer using an inventory-based method, the basic calculation is Beginning inventory + Net purchases and included acquisition costs – Ending inventory = COGS. Unsold stock remains in ending inventory rather than becoming the cost of this period’s sales.
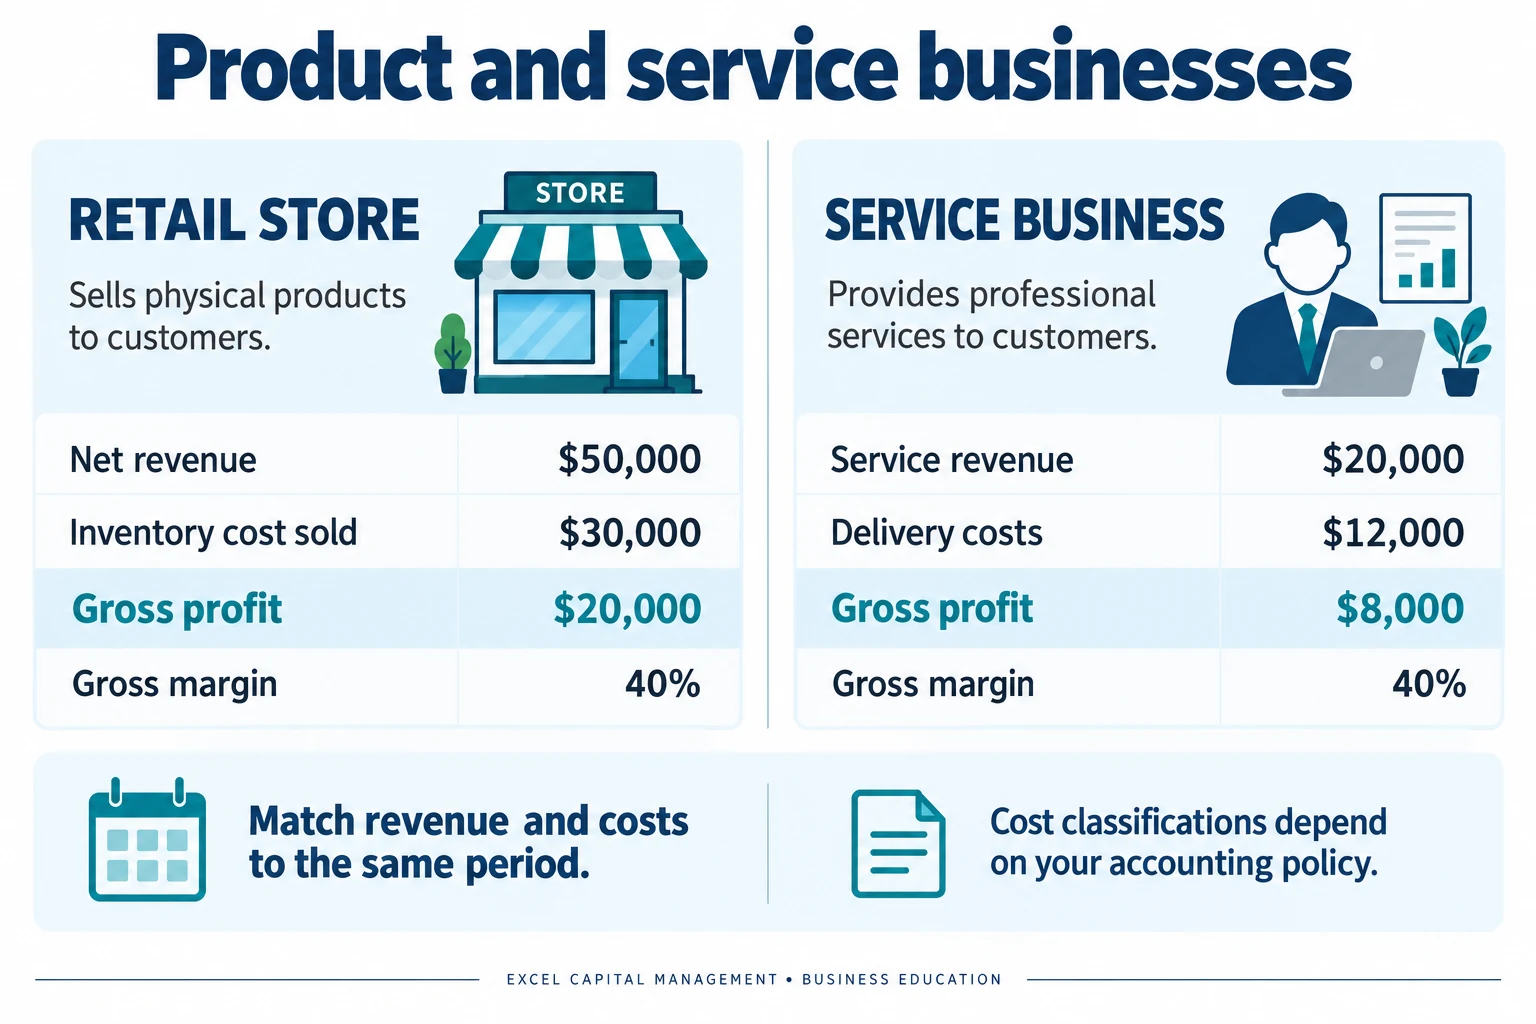
For example, $20,000 of beginning inventory plus $45,000 of net purchases and included costs, less $35,000 of ending inventory, gives $30,000 of COGS. With $50,000 of net revenue, gross profit is $20,000 and gross margin is 40%.
Manufacturers also account for production costs and changes in work in process and finished goods. Tax inventory methods can differ, including small-business exceptions. See the IRS Schedule C instructions, Part III, for the tax reporting framework.
Why is knowing gross profit important?
Both fixed and variable expenses together are used in calculating your cost of goods sold.
For that reason, it’s important to know exactly what you’re paying for all variable and fixed expenses and how that balances out with your revenue (your sales).
Knowing your gross profit is critical because it shows what is left to cover operating expenses and contribute to profit.
All those sales you’re making aren’t truly (or fully) yours because you’re paying to produce the product or create and offer the service to your customers.
Not until you subtract all of the costs associated with that can you fully understand the health of your business in terms of profit.
Higher gross profit can leave more room for your business goals, but profit is not the same as cash in the bank. Customer payment timing, inventory purchases and debt payments also affect cash flow.
Those goals include creating a cushion in case of an unexpected slowdown, putting money aside in anticipation of your next busy season, or investing in new products, hires, or an additional location.
How to calculate gross profit
Because gross profit may include both fixed and variable expenses, it’s a bit trickier than it at first appears to calculate gross profit.
However, nowadays accounting programs like QuickBooks help greatly in mostly automating this calculation (and the rest can be taken care of by an in-house accountant).
But if you’re just getting started and aren’t set up on an accounting program such as this yet, or would rather carefully calculate your gross profit yourself, let’s go over an example to see how you’d do it.
Gross profit formula example: How to find your gross profit
J.R. owns a retail clothing store in a busy strip of downtown Dallas, Texas.
As a retail store, he doesn’t produce the clothing himself. Rather, he purchases clothing from various wholesale brands and then sells them at a markup.
Let’s say the average T-shirt at his location costs $10 to purchase. For this simplified example, another $5 per shirt covers inbound freight and other properly included inventory acquisition costs. Store displays, sales staff pay and advertising are excluded.
That brings his COGS to $15 for every T-shirt. With an average price of $25 per T-shirt, his gross profit is $10:
$25 REVENUE – $15 COGS = $10 GROSS PROFIT
It’s important at this point to keep in mind that the $10 in gross profit from each T-shirt sale isn’t all his to keep.
Gross profit doesn’t include operating expenses such as advertising and store rent, as mentioned earlier.
Gross profit is calculated before operating expenses and other deductions. For the later steps, see our net income formula guide and the SEC’s financial statement guide.
Gross profit for a service business
A service business can use the same basic formula: Service revenue – Cost of services = Gross profit. Its management accounts may group delivery staff wages, project subcontractors and directly attributable project costs as cost of services. General administration and marketing usually sit below gross profit.
Suppose a design firm earns $20,000 from client work in a month. It assigns $9,000 of delivery wages, $2,000 of project subcontractor costs and $1,000 of project-specific costs to that work. Gross profit is $8,000, and gross margin is 40%. Do not deduct those same costs again as operating expenses.
A service provider without merchandise may have no COGS on its tax return, even when management reports track a cost-of-services subtotal. Keep your reporting basis consistent and reconcile it with your accountant.
Expressing gross profit as a percentage
Now that you know how to find your gross profit, that leads us to another important financial metric: your gross profit margin.
What is your gross profit margin?
Gross profit margin is gross profit expressed as a percentage of net revenue. It shows how much of each sales dollar remains after COGS.
The gross profit margin calculation is:
Gross profit / Net revenue × 100 = Gross profit margin (%)
So, going back to our example, J.R.’s gross margin is:
$10 Gross profit / $25 Revenue × 100 = 40% Gross profit margin
That is 40 cents of gross profit for every dollar of revenue, before operating expenses. Markup uses a different denominator: $10 / $15 × 100 = 66.7%. A 40% markup and a 40% gross margin are not interchangeable.
Reading your gross profit result
Gross profit tells you how much revenue remains after COGS, but that number can be deceiving.
It is possible for your gross profit to increase from one quarter or year to the next, particularly during a period of growth, while technically you became less efficient.
Let’s say your operating expenses increased in sync with your level of growth but your gross profit margin went down.
While you might be bringing in more money, you’d actually be in worse shape and could even have a hard time paying those operating expenses if your profit margin drops low enough.
By knowing your profit margin, you know much more than how much money your business is bringing in. You know how effectively your business produces and sells its goods and/or services.
For a fuller explanation of margin formulas, see our profit margin guide. Use the SBA’s market research and competitive analysis guidance to put product pricing and competition in context.
Gross profit formula in Excel
If net revenue is in cell B2 and COGS is in C2, enter =B2-C2 for gross profit. For gross margin, use =IF(B2=0,"",(B2-C2)/B2) and format the result as a percentage. Do not also multiply by 100 when using Excel’s percentage format. The blank result avoids dividing by zero.
Common gross profit questions
Can gross profit be negative? Yes. If COGS exceeds net revenue, the result is a gross loss. Check pricing, discounts, waste and cost allocation before drawing conclusions.
Does gross profit show cash available to spend? No. Review payment timing, receivables, inventory and cash obligations alongside your P&L. The SBA’s guidance on managing business finances provides a broader financial-management framework.
Learn more about your profit & loss
Understanding gross profit and how to calculate it is important.
When reviewing your profit & loss report, the more you know, the easier it becomes to spot trends and identify areas of concern long before they become a real issue.
By understanding your gross profit, you’re now able to spot more of those clues and better identify important financial patterns in your business.

