
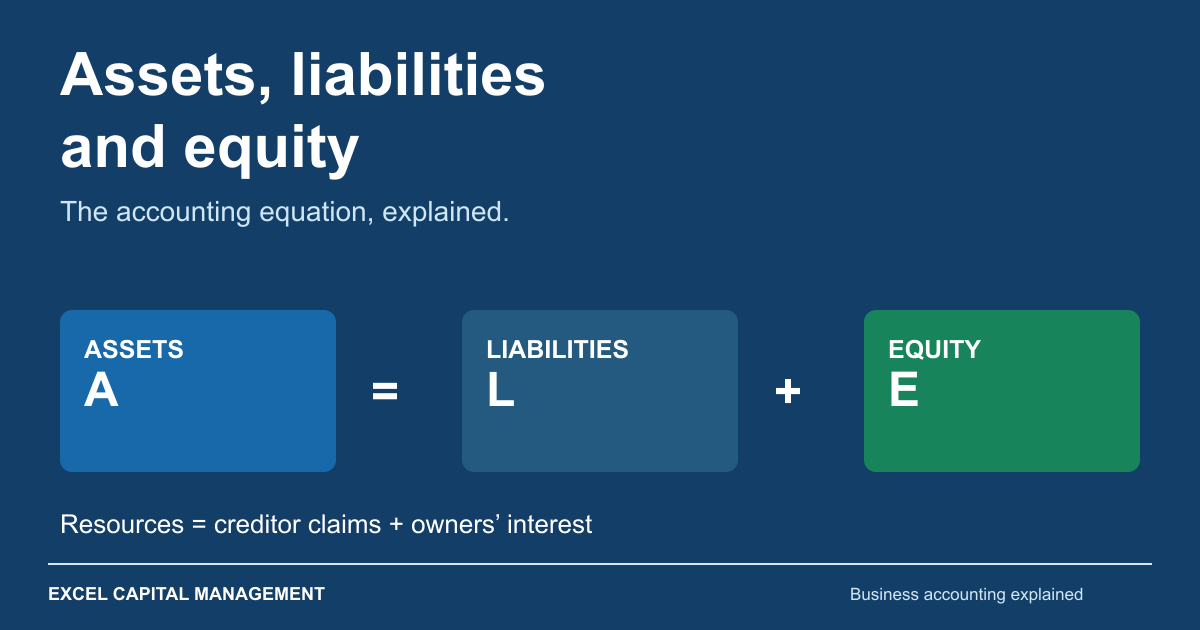
Assets, liabilities and equity are the three main parts of a balance sheet. Assets are the resources a business controls, liabilities are its obligations, and equity is the owners’ remaining interest after liabilities are subtracted from assets.
Quick answer: The accounting equation is Assets = Liabilities + Equity. If a business has $100,000 in assets and $50,000 in liabilities, its equity is $50,000. The equation explains how the balance sheet fits together; it does not, by itself, prove that a business is profitable or has enough cash.

What are assets, liabilities and equity?
| Category | Meaning | Business examples |
|---|---|---|
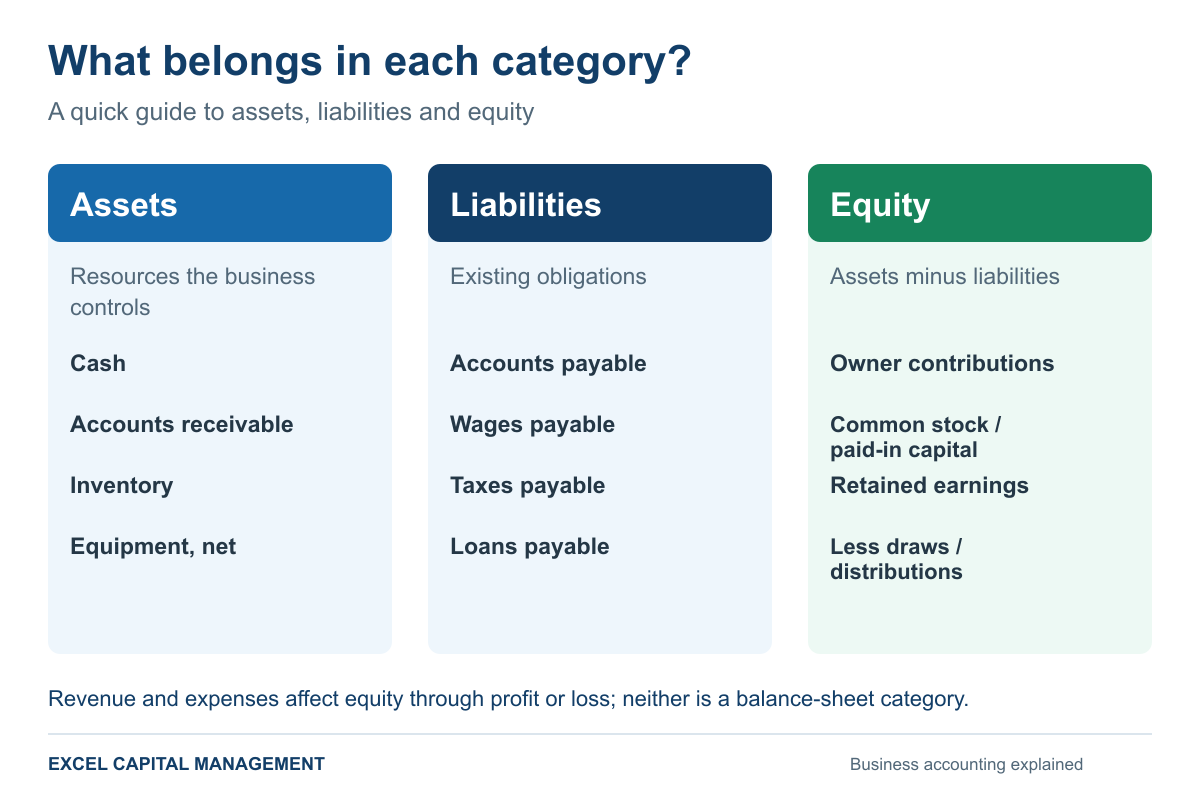
| Assets | Resources the business controls that can provide economic benefits. | Cash, receivables, inventory, equipment and property. |
| Liabilities | Existing obligations to transfer resources or provide goods or services. | Supplier invoices owed, loans, wages payable and customer advances. |
| Equity | The residual interest in assets after deducting liabilities. | Owner contributions, share capital and retained earnings, reduced by losses and distributions. |
Assets: the resources available to the business
Cash is an asset, but assets also include amounts customers owe you and resources you use to operate. An invoice you expect to collect belongs in accounts receivable; products held for sale are inventory. Equipment is usually reported at its carrying amount after accumulated depreciation and any applicable impairment.
Current assets generally include cash and assets expected to be sold, consumed or converted to cash within a year or the normal operating cycle, if longer. Noncurrent assets include longer-lived resources such as equipment, buildings and certain intangible assets. Investments can be current or noncurrent; they are not automatically long-term.
Liabilities: what the business owes
A liability exists when the business has an obligation. Accounts payable represent unpaid supplier bills. Loans payable represent borrowed money that must be repaid. Wages and taxes payable are amounts owed but not yet paid. Unearned revenue is commonly a liability because the business has received money before delivering the promised goods or services.
Current liabilities generally fall due within a year or the normal operating cycle, if longer. Noncurrent liabilities are longer-term obligations. A long-term loan may have both a current portion and a noncurrent portion.
Equity: the owners’ residual interest
Equity is calculated as Assets − Liabilities. Depending on the entity, it may be called owner’s equity, partners’ capital, members’ equity or shareholders’ equity. Contributions and retained profits can increase equity. Losses, owner draws and distributions can reduce it.
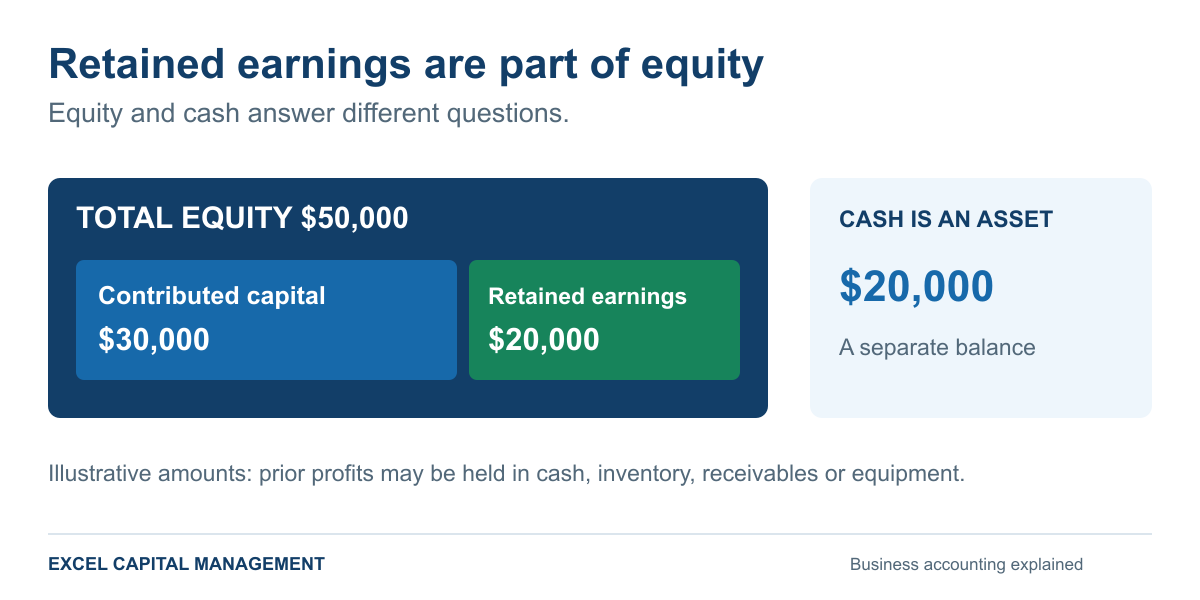
Retained earnings are generally one component of equity, not the whole balance. Equity is a book accounting amount; it is not necessarily the sale price or market value of the company.
What is the accounting equation?
The accounting equation, also called the balance sheet equation, states that total assets equal total liabilities plus total equity. The same resources are viewed from two angles: the assets themselves and the claims against those assets.
Use the version that matches the missing number:
- Assets = Liabilities + Equity: $50,000 + $50,000 = $100,000.
- Liabilities = Assets − Equity: $100,000 − $50,000 = $50,000.
- Equity = Assets − Liabilities: $100,000 − $50,000 = $50,000.
Use balances from the same business and reporting date. Do not subtract liabilities from equity to calculate assets, and do not treat all liabilities as expenses.

Is it an asset, a liability or equity?
Classify the account by what it represents, not simply by whether money came in or went out. Receiving a loan adds cash, but it also creates a liability. Buying equipment uses cash, but it can create another asset instead of an immediate expense.
| Account or transaction | Classification | Why |
|---|---|---|
| Cash | Asset | Money available to the business. |
| Accounts receivable | Asset | Customers owe money to the business. |
| Inventory | Asset | Goods held for sale; their cost is recognized as expense when sold. |
| Prepaid insurance or rent | Asset initially | The payment covers future periods; expense is recognized as the benefit is used. |
| Accounts payable | Liability | The business owes suppliers. |
| Loans payable | Liability | Borrowed principal remains repayable. |
| Unearned revenue | Liability | The business still owes goods or services. |
| Common stock and paid-in capital | Equity | Owners’ contributed capital. |
| Retained earnings | Equity | Accumulated profits retained after losses and applicable distributions. |
| Owner draws or dividends | Reduce equity | Distributions to owners are not operating expenses. Declared, unpaid dividends may also create a liability. |
| Revenue | Income statement account | Increases profit and therefore equity, with other factors unchanged. |
| Expenses | Income statement accounts | Reduce profit and therefore equity. An unpaid expense can also create a liability. |
Assets, liabilities and equity: a balance sheet example
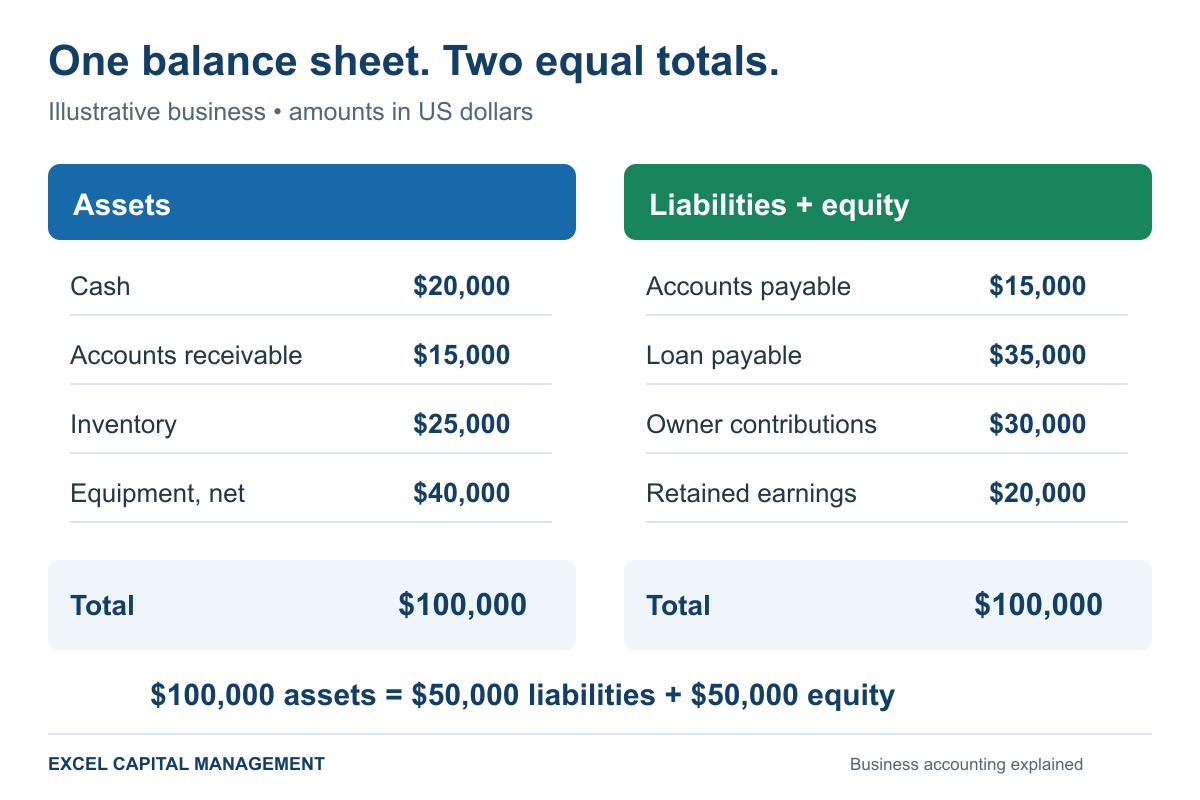
Suppose a business reports the following balances on one date. These illustrative numbers are not an actual Excel Capital client’s financial statements.
| Balance-sheet item | Amount | Category |
|---|---|---|
| Cash | $20,000 | Asset |
| Accounts receivable | $15,000 | Asset |
| Inventory | $25,000 | Asset |
| Equipment, net | $40,000 | Asset |
| Total assets | $100,000 | |
| Accounts payable | $15,000 | Liability |
| Loan payable | $35,000 | Liability |
| Total liabilities | $50,000 | |
| Owner contributions | $30,000 | Equity |
| Retained earnings | $20,000 | Equity |
| Total equity | $50,000 |
The check is $100,000 = $50,000 + $50,000. If you only knew assets and liabilities, you could calculate equity as $100,000 − $50,000. Notice that $50,000 of equity does not mean $50,000 is available in the bank: cash is only $20,000.
See the original balance sheet layout

For the process of building the report, use our guide to creating a balance sheet.
How business transactions change the accounting equation
Double-entry accounting records each transaction in at least two accounts, with equal total debits and credits. Those accounts do not have to belong to different categories. A cash purchase of equipment affects two asset accounts.
Here is a separate illustrative sequence starting from zero balances. It assumes cash service revenue with no related costs except the stated current-period rent, and omits taxes, depreciation and other adjustments.
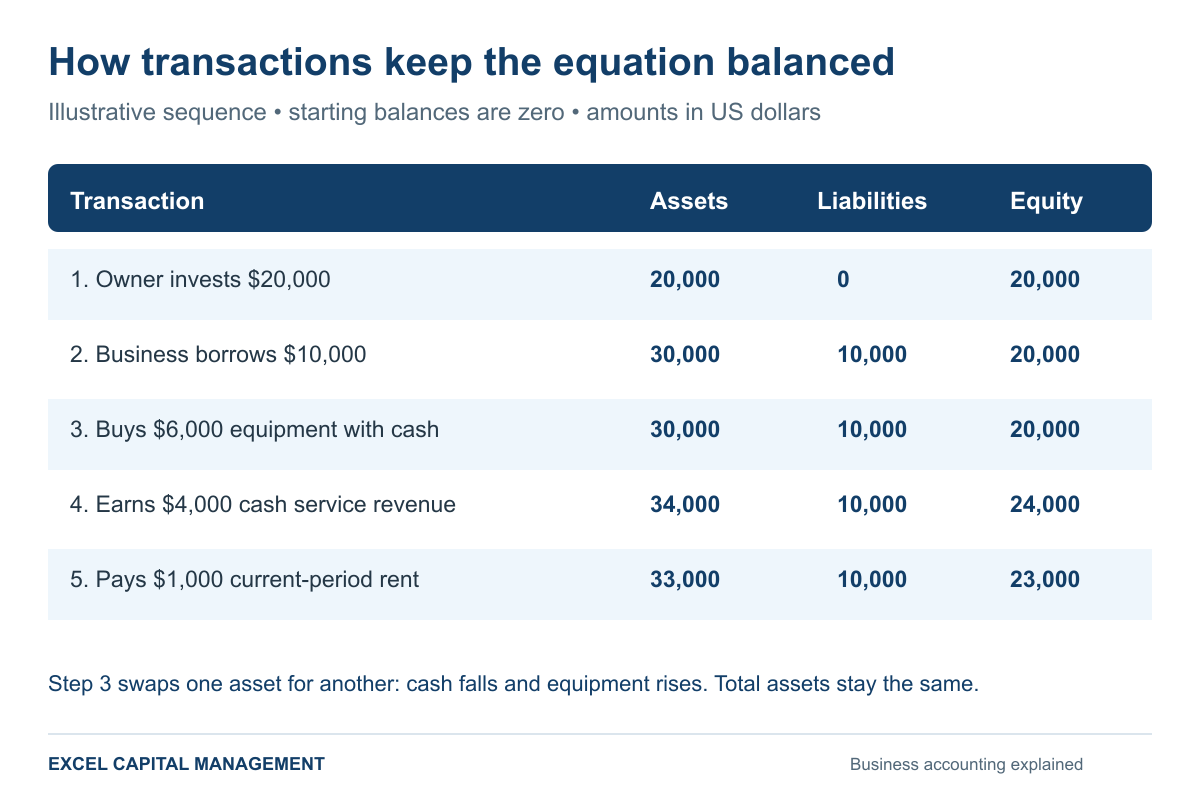
- The owner invests $20,000. Cash and contributed equity each increase by $20,000: $20,000 = $0 + $20,000.
- The business borrows $10,000. Cash and loans payable rise: $30,000 = $10,000 + $20,000. Borrowing is not revenue.
- It buys equipment for $6,000 cash. Cash falls by $6,000 and equipment rises by $6,000. Total assets remain $30,000.
- It earns $4,000 from cash services. Cash and equity increase: $34,000 = $10,000 + $24,000.
- It pays $1,000 rent for the current period. Cash and equity decrease: $33,000 = $10,000 + $23,000.
Loan repayments work differently from rent. Paying $1,000 of loan principal reduces cash and the loan liability by $1,000. Interest is a separate expense that generally reduces profit and equity. A payment can contain both principal and interest.
How the expanded accounting equation fits in
The basic equation uses a single equity total. An expanded version shows why that total changes. For a simplified owner-operated business over one period:
This version assumes no other equity adjustments. Corporations may use share capital and dividends instead of owner capital and withdrawals. Do not add current-period revenue and expenses to an ending retained earnings balance that already includes the period’s profit; that would count the profit twice.
To understand the earnings part, see the net income formula and the retained earnings formula and examples.
What these balances tell you about your business
The equation is an accounting relationship, not a financial-health score. A business can have a balanced balance sheet while losing money, collecting invoices slowly or facing debt payments it cannot comfortably meet.
- Liquidity: How much of the asset balance is cash or likely to become cash soon? Inventory and equipment cannot always cover tomorrow’s payroll.
- Obligations: Which liabilities are due next month, and which are due over several years? Review a debt schedule alongside the balance sheet.
- Equity trend: Are retained profits building equity, or are losses and distributions reducing it? Compare several reporting dates.
- Repayment capacity: Review cash flow and earnings alongside debt payments. Our debt service coverage ratio guide explains a related repayment measure.
If liabilities exceed assets, equity is negative. For example, $80,000 of assets minus $100,000 of liabilities equals −$20,000 of equity. The equation still balances: $80,000 = $100,000 + (−$20,000). Investigate the cause, the asset values and the cash-flow outlook rather than drawing a conclusion from this number alone.
For a broader view, combine the balance sheet with a profit and loss statement and cash-flow information. Funding providers may also consider credit, business history, collateral and product requirements.
Frequently asked questions
Are assets equal to liabilities plus equity?
Yes. The basic accounting equation is Assets = Liabilities + Equity. Rearranging it gives Equity = Assets − Liabilities and Liabilities = Assets − Equity.
What is the difference between assets and equity?
Assets are the business’s resources. Equity is the residual interest after liabilities are deducted. A business with $100,000 of assets and $60,000 of liabilities has $40,000 of equity.
Is accounts payable an asset, liability or equity?
Accounts payable is a liability because it represents amounts the business owes suppliers. Accounts receivable is an asset because it represents amounts customers owe the business.
Are expenses liabilities?
They are different concepts. An expense measures a cost recognized in a period; a liability is an outstanding obligation. Unpaid wages can create both wage expense and wages payable. Paying the liability later does not create that expense a second time.
Is revenue an asset or equity?
Revenue is an income statement account. Earning revenue can increase an asset such as cash or receivables, or reduce a liability such as unearned revenue. It increases profit and therefore equity, with other factors unchanged.
Are dividends assets, liabilities or equity?
For the company paying them, dividends are distributions that reduce equity, not operating expenses. A declared cash dividend that has not yet been paid is generally recorded as dividends payable, a liability.
Does a balanced balance sheet mean the books are correct?
No. Both sides can balance even when a transaction is omitted, posted to the wrong accounts or recorded at the wrong amount on both sides. Reconciliations and a review of supporting records still matter.
Reviewing your balance sheet before seeking funding?
Use these definitions to organize your financial records, then compare financing options for your business’s needs.
Compare business funding optionsFinancing is subject to underwriting, approval, product availability and provider requirements.
Sources and further reading
SEC: Beginners’ Guide to Financial Statements explains the balance-sheet relationship. Principles of Accounting: The Accounting Equation covers the components, and its transaction examples explain changes in accounts. Examples in this guide are illustrative. This article provides general accounting education.

